
Market Overview
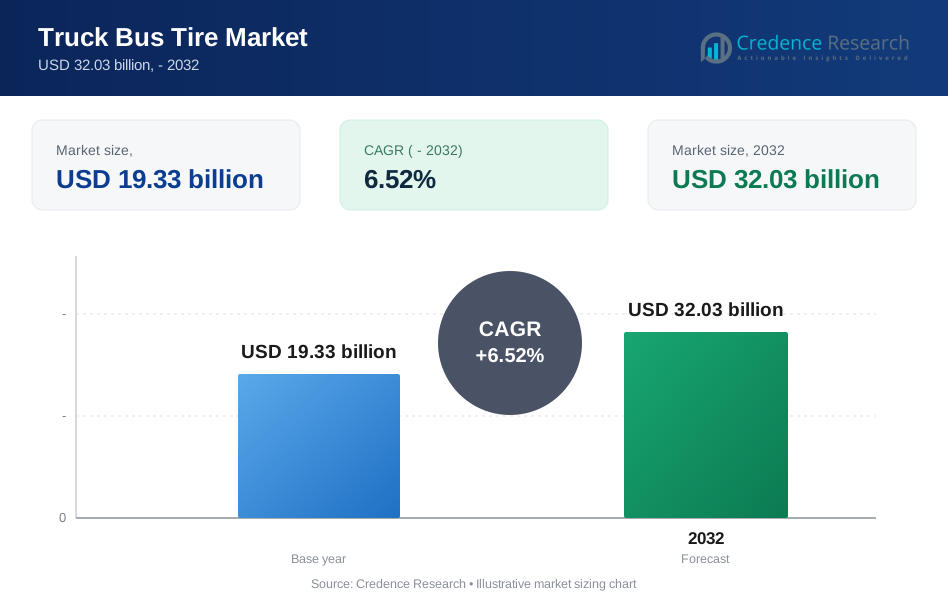
Truck Bus Tire Market was valued at USD 19.33 billion in 2024 and is anticipated to reach USD 32.03 billion by 2032, growing at a CAGR of 6.52 % during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Truck Bus Tire Market Size 2024 | USD 19.33 Billion |
| Truck Bus Tire Market, CAGR | 6.52 % |
| Truck Bus Tire Market Size 2032 | USD 32.03 Billion |
The competitive landscape of the truck and bus tire market features top players such as BRIDGESTONE Corporation, MICHELIN, The Goodyear Tire & Rubber Company, Continental AG, Yokohama Rubber Corporation, Sumitomo Rubber Industries, Ltd., Apollo Tyres, Giti Tire, Kumho Tire and Balkrishna Industries Limited (BKT). These firms compete globally through strong OEM channels, wide aftermarket networks and continuous innovation in fuel‑efficient, low‑rolling resistance tyres. Regionally, the leading market is North America, which holds an estimated 20 % share of the global truck & bus tire market.
Market Insights
- The global truck and bus tire market reached USD 19.33 billion in 2023 and will grow at a CAGR of 6.52 % from 2024‑2032.
- Asia‑Pacific led regionally with a 39% market share in 2023, while the radial tyre segment held a dominant share in the market.
- Major growth drivers include rising e‑commerce logistics, urbanisation boosting commercial vehicle fleets, and infrastructure expansion across emerging economies.
- Market trends highlight adoption of low‑rolling resistance tyres, smart sensors for fleet operations, and increasing shift from tube‑type to tubeless tyres in commercial segments.
- Key restraints stem from raw material cost volatility and pricing pressures in mature markets, limiting margin expansion for tyre manufacturers.
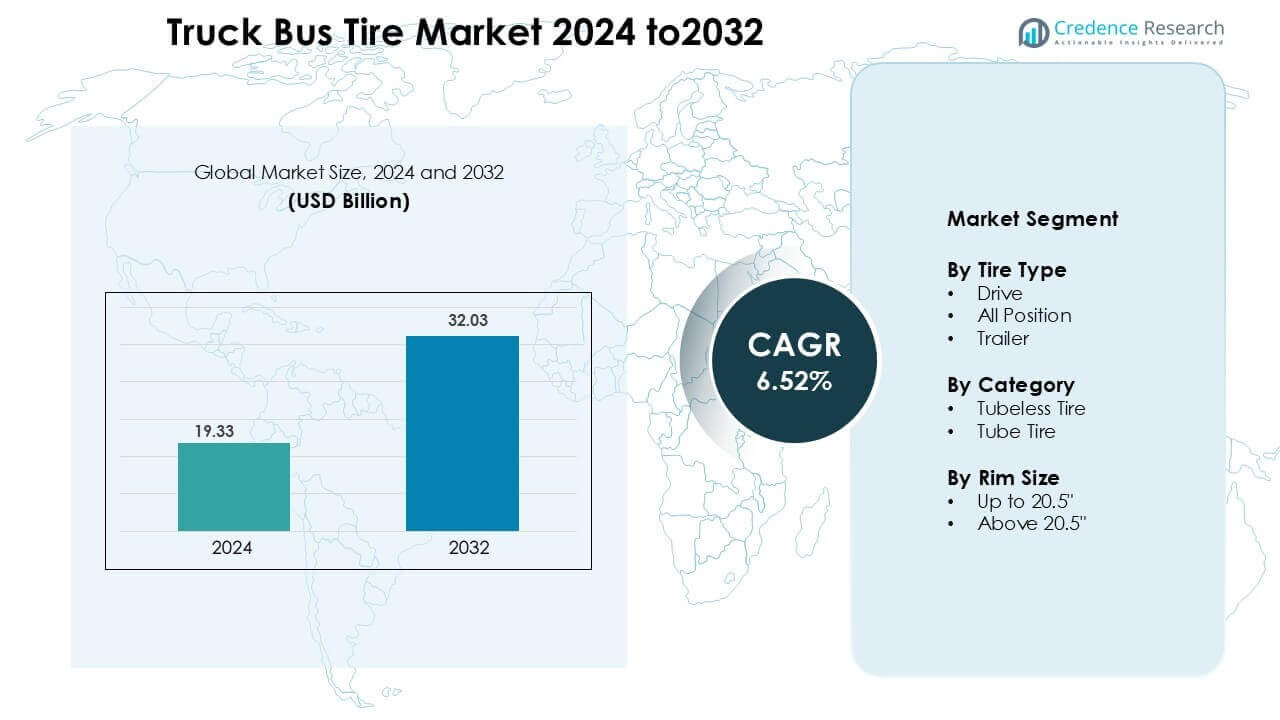
Market Segmentation Analysis:
By Tire Type
Within the tire‑type segmentation, the Drive sub‑segment holds dominance in the global truck and bus tire market, capturing the largest share in 2024. This leadership stems from the drive tire’s critical function in traction and power transmission, especially in heavy‑duty trucks operating long‑haul and regional freight routes. The key drivers include rising logistics and e‑commerce volumes, increasing commercial vehicle mileage, and fleet owners’ demand for high‑durability drive‑axle tires. In contrast, the All‑Position and Trailer segments exhibit faster relative growth as fleets increasingly standardise inventory and opt for flexible tyre usage across axles.
- For instance, the Bridgestone Ecopia tire line, which includes models designed as all-position tires for commercial vehicles, delivers improved fuel economy through low rolling resistance while maintaining durability. This makes it a preferred choice for fleet operators aiming for greater flexibility across multiple axles.
By Category
In the category segmentation, the Tubeless tire segment emerged as the dominant share‑holder in 2024 and continues to expand most rapidly. Market preference for tubeless designs is driven by improved safety (less risk of blow‑outs), lower maintenance costs, rising adoption of smart‑sensor enabled tyres, and regulatory emphasis on durability in commercial vehicles. Tube tires remain relevant in niche or legacy fleets in select markets, but tubeless formats capture most new original‑equipment and replacement demand globally.
- For instance, Continental’s ContiPressureCheck system, which integrates tire pressure monitoring sensors in tubeless tires, helps reduce maintenance costs by detecting pressure issues in real-time, thus improving safety and extending tire life.
By Rim Size
For rim‑size segmentation in the truck and bus tire market, the “Above 20.5″” category dominates share in 2024 and is forecast to maintain leadership. The larger rim‑sized tyres align with heavy‑duty commercial vehicles, long‑haul freight trucks and intercity buses that demand higher load‑bearing capacity, enhanced stability and extended service life. Key growth drivers include growth in global freight transport, heavier vehicle axle loads, and infrastructure upgrades that support larger vehicles. The “Up to 20.5″” segment retains presence in medium‑duty trucks and regional haulage but grows more modestly compared to the larger‑rim cohort.
Key Growth Drivers
Expansion of Freight and Bus Fleet Activity
The global truck and bus tire market has been significantly propelled by the growth in freight transportation and passenger bus services. The expansion of e-commerce, coupled with burgeoning international trade, has led to increased road freight volumes and the consequent demand for heavy-duty commercial vehicles. Meanwhile, urbanisation and public transportation expansion in emerging markets are boosting the number of passenger buses in operation. As each truck and bus represents multiple tire sets over its lifetime, the overall tire replacement and OEM demand rises accordingly. Infrastructure investments such as highway construction and national transport corridors further strengthen vehicle fleet growth, thereby augmenting tire demand across both new builds and replacement cycles.
- For instance, in India, government initiatives promoting public transport expansion, such as the PM e-Bus Sewa scheme, have led to significant bus orders for manufacturers like Tata Motors, which in turn boosts demand for durable bus tires and components.
Technological Advancement & Efficiency Requirements
Manufacturers in the truck and bus tire sector are increasingly driven by performance criteria such as low rolling resistance, extended tread life, and improved durability under heavy loads. Regulatory mandates and fleet-operator demand for fuel economy have encouraged adoption of radial tire constructions and advanced compounds. Additionally, the introduction of smart tire technologies-embedded sensors for pressure, temperature and wear monitoring-adds value and differentiates offerings, thereby fostering growth of premium tire segments. As fleet operators shift toward total cost of ownership models, higher-efficiency tires gain traction, supporting growth in the segment.
- For instance, Michelin’s X-Line Energy tire range, designed for long-haul trucking, offers enhanced fuel efficiency by reducing rolling resistance, helping fleets comply with stringent fuel economy regulations.
Growth in Emerging Markets & Infrastructure Development
Emerging economies, especially in Asia-Pacific and Latin America, are major engines for market growth in the truck and bus tire space. Rapid urbanisation, expanding logistics networks, and government investment in transport infrastructure are driving fleet expansion in these regions. The Asia-Pacific region stands out with approximately half of the global demand in recent years. As new highways, bus rapid transit systems and logistics hubs are established, the need for reliable commercial vehicle tire solutions increases, offering scale opportunities for manufacturers and aftermarket service providers alike.
Key Trends & Opportunities
Smart Tire Integration and Predictive Maintenance
A pronounced trend in the truck and bus tire market is the integration of sensing technologies and predictive maintenance capabilities. Fleet operators are increasingly looking for tires that not only deliver durability but also generate real-time data about wear, pressure and road conditions, enabling proactive maintenance and reducing downtime. Smart tires equipped with embedded sensors support this shift, making them an opportunity for OEMs and aftermarket players to offer value-added services and lifetime support. This trend dovetails with the digitization of fleet operations and connected vehicle ecosystems, offering manufacturers a pathway to higher margin offerings.
- For instance, Goodyear's SightLine platform, which uses smart tire sensors to monitor tire pressure and temperature in real-time, allows fleet operators to take preventive actions before issues arise, reducing the likelihood of tire failure.
Sustainability, Retreading and Eco-friendly Materials
Environmental concerns and regulatory pressures are compelling a transition toward sustainable tire solutions in the commercial segment. There is growing demand for low rolling-resistance tires, recycled rubber compounds, and retreadable casings which extend lifecycle and reduce waste. Retreading in particular offers fleet operators a cost-effective alternative without compromising performance, whilst enabling tire manufacturers to capture aftermarket value streams. As circular economy principles become more mainstream, investment in eco-friendly manufacturing and materials innovation represents a distinct opportunity in the truck and bus tire market.
- For instance, Goodyear’s “Endurance” tire series uses eco-friendly materials such as soybean oil-based rubber compounds, aiming to reduce environmental impact while maintaining high performance and durability.
Specialty Tires for Electric and Urban Commercial Vehicles
Though still nascent, an important emerging opportunity lies in the development of tires tailored for electric trucks and buses, and urban commercial fleets that face unique operating conditions. For example, electric powertrains impose different torque characteristics and drive cycles, which in turn require optimized tire designs. Urban delivery vehicles and last-mile fleets also create demand for tires capable of frequent stop-start cycles, high mileage, and constrained urban roads. By targeting these niche but growing segments, manufacturers can differentiate their offerings and capture first-mover advantage.
Key Challenges
Raw Material Price Volatility and Supply Chain Risks
Tire manufacturing is heavily dependent on raw materials such as natural rubber, synthetic rubber, steel cord, and carbon black. Fluctuations in natural rubber prices triggered by supply disruptions, climate variability and geopolitical factors impose significant cost pressures on tire producers. Moreover, the complexity of global supply chains for tire components makes the sector vulnerable to logistics disruptions, which can increase lead times and inventories. These cost and supply uncertainties constrain margin stability and may force manufacturers to pass on higher prices, which fleet operators may resist.
Intense Competition and Price Sensitivity in the Aftermarket
The aftermarket for truck and bus tires constitutes a significant share of market volumes, but it is characterized by high price sensitivity and competitive fragmentation. Manufacturers face pressure from low-cost regional producers and generic brands, which can erode pricing power and margin performance. At the same time, innovation cycles (smart tires, eco-materials) demand significant R&D investment, which may be difficult to recoup if the market remains cost-driven. Balancing the need for technological advancement with affordability, especially among fleet operators in emerging markets, remains a persistent strategic challenge.
Regional Analysis
Asia Pacific
The Asia Pacific region commanded the largest share of the truck & bus tire market in 2024, estimated at roughly 39% of global revenue Strong growth stemmed from expanding freight transport, major infrastructure spend in China and India, and rising commercial‑vehicle fleets in Southeast Asia. Additionally, domestic tyre manufacturing hubs and competitive pricing boosted aftermarket replacement demand. The robust logistics network, heavy‑duty operations and regulatory push for durability in tyres further strengthened this region’s leadership position.
North America
North America accounted for an estimated 20% of the global truck & bus tire market revenue in 2024. The region benefits from established long‑haul trucking infrastructure, a mature aftermarket replacement cycle and fleet operators adopting advanced tyre technologies. Demand is driven by fuel‑efficiency regulations and smart‑fleet management trends. Although growth is more moderate compared with emerging regions, technology adoption and premium‑segment tyres raise average selling prices.
Europe
Europe held around 15‑18% of global market share for truck & bus tyres in 2024, supported by robust commercial‑vehicle usage and retrofit markets. Infrastructure modernisation, stringent emissions and tyre performance standards, and replacement cycles of heavy commercial fleets underpin demand. Growth is stable, driven by regional logistics consolidation and premium product uptake, though market maturity limits the pace of expansion compared to Asia‑Pacific.
Latin America
Latin America represented approximately 10% of the global truck & bus tire market in 2024. A surge in regional freight, infrastructure upgrades and fleet renewal in Brazil, Argentina and Mexico underlie this share. Still, weaker replacement cycles, currency volatility and lower average selling prices constrain volume growth. Opportunities lie in aftermarket expansion and increasing usage of tubeless and larger rim‑sized tyres.
Middle East & Africa (MEA)
The MEA region captured roughly 8% of the global truck & bus tyre market in 2024. Growth is driven by rising logistics in oil‑and‑gas, mining operations and road‑transport infrastructure expansion across GCC and African markets. However, challenging terrain, high import duties, limited local manufacturing and slower fleet replacement hinder faster growth. Nonetheless, the region offers opportunity for premium tyres and retreading services as fleet durability demands rise.
Market Segmentations
By Tire Type
- Drive
- All Position
- Trailer
By Category
- Tubeless Tire
- Tube Tire
By Rim Size
- Up to 20.5"
- Above 20.5"
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the global truck & bus tire market features a moderately concentrated structure in which the top ten players command approximately 60 % of global sales, underscoring significant scale advantages. Bridgestone Corporation, MICHELIN and The Goodyear Tire & Rubber Company maintain leading positions through strong brand recognition, extensive global manufacturing networks, and large fleets of commercial‑vehicle customers. Regional entrants particularly Chinese manufacturers are expanding rapidly, leveraging cost‑efficient production and rising export capabilities to challenge legacy brands. Innovation in product technologies such as low‑rolling‑resistance compounds, smart sensors and tubeless constructions serves as a key differentiator. Meanwhile, firms pursue vertical integration of raw materials, strategic acquisitions and channel expansion to strengthen margins amid raw‑material volatility and pricing pressures. The combined effect of global scale, technological leadership and regional adaption shapes competitive dynamics for new entrants and incumbent firms alike.
Key Player Analysis
- Bridgestone Corporation
- Yokohama Rubber Corporation
- Continental AG
- MICHELIN
- Apollo Tires
- Giti Tire
- The Goodyear Tire & Rubber Company
- Sumitomo Rubber Industries, Ltd.
- Kumho Tire
- Balkrishna Industries Limited (BKT)
Recent Developments
- In September 2025, Continental unveiled the Conti Urban HA 5 NXT city-bus tire. Up to 60% renewable/recycled materials, and 25% lower rolling resistance. Continental cites up to 15% more range for e-buses
- In July 2025, Yokohama launched the BluEarth 718L long-haul drive tire. Sizes include 295/75R22.5, 11R22.5, 285/75R24.5, and 11R24.5.
Report Coverage
The research report offers an in-depth analysis based on Tire Type, Category, Rim Size and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Truck and bus tire demand will expand steadily as global freight and logistics networks grow and commercial vehicle fleets increase.
- Adoption of smart tyres and IoT sensors will advance significantly, enabling real‑time monitoring of pressure, wear and temperature across fleets.
- Demand for low rolling resistance and fuel‑efficient tyres will rise as fleet operators focus on cost reduction and regulatory compliance.
- Radial tyres will continue to replace bias‑ply types in commercial vehicles, especially in heavy‑duty applications.
- Emerging markets (Asia‑Pacific, Africa, Latin America) will capture a larger share of the market as infrastructure investment and vehicle penetration accelerate.
- After‑market replacement demand will strengthen as older commercial vehicles reach end of tyre life and fleet operators opt for upgraded tyre formats.
- Tyre manufacturers will face increased pressure to integrate sustainable materials and retreading solutions to meet environmental and circular‑economy mandates.
- Larger rim‑size segments and heavy‑duty tyre formats will grow faster due to heavier axle loads and longer haulage operations in global trade
- The OEM channel will maintain importance, but the aftermarket segment will grow faster and drive volume increases in mature markets.
- Competitive pressure will escalate from cost‑efficient regional and Chinese manufacturers, forcing global players to differentiate via premium products, technology and global service‑networks.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Truck Bus Tire Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is Truck Bus Tire Market projected to grow between 2025 and 2032?
Which Truck Bus Tire Market segment held the largest share in 2024?
What are the primary factors fueling the growth of Truck Bus Tire Market?
Who are the leading companies in Truck Bus Tire Market?
Which region commanded the largest share of Truck Bus Tire Market 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 19.33 billion → 2032: USD 32.03 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Truck Bus Tire Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Truck Bus Tire Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Truck Bus Tire Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Truck Bus Tire Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Truck Bus Tire Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Truck Bus Tire Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Truck Bus Tire Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Truck Bus Tire Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 19.33 billion → 2032: USD 32.03 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Truck Bus Tire Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Truck Bus Tire Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Truck Bus Tire Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Truck Bus Tire Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

