
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| UAE Hummus Market Size 2023 | USD 10.03 million |
| UAE Hummus Market, CAGR | 8.81% |
| UAE Hummus Market Size 2032 | USD 19.70 million |
Market Overview
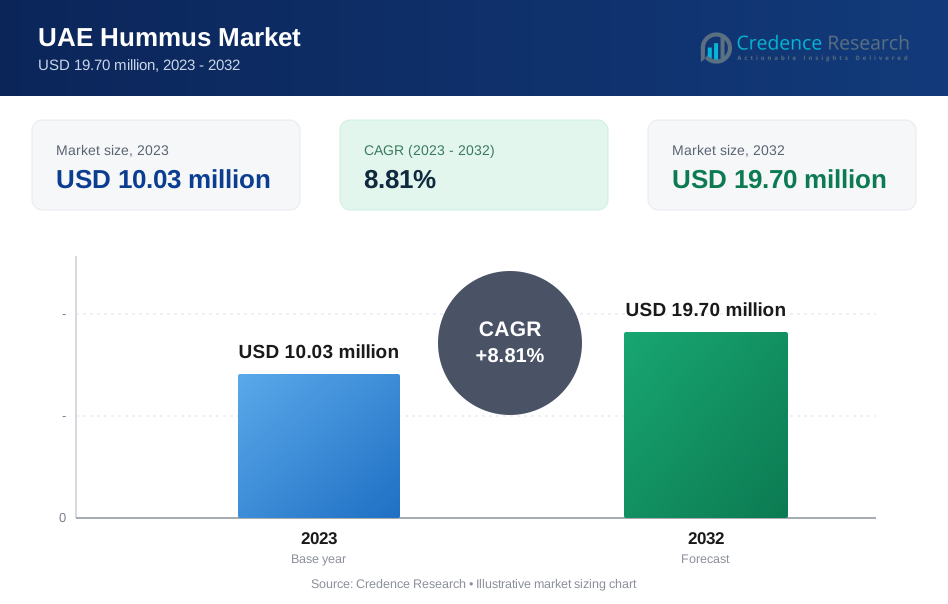
The UAE Hummus Market is projected to grow from USD 10.03 million in 2023 to an estimated USD 19.70 million by 2032, reflecting a compound annual growth rate (CAGR) of 8.81% from 2024 to 2032. This robust growth underscores the increasing popularity of hummus as a versatile and nutritious food option among consumers in the UAE.
The market's growth is bolstered by several drivers, including the growing awareness of health benefits associated with hummus, such as being a rich source of protein, fiber, and essential nutrients. The rising prevalence of veganism and vegetarianism aligns well with hummus as a preferred dietary choice. Furthermore, trends like clean-label and organic food consumption positively influence the market. Technological advancements in food processing and improved cold-chain logistics also support market expansion by ensuring product quality and availability.
Geographically, the UAE's major urban centers, including Dubai and Abu Dhabi, dominate the market due to higher disposable incomes and a thriving multicultural population that fosters demand for diverse cuisines. Key players like Sabra Dipping Company, Al Wadi Al Akhdar, and Freshly Foods are instrumental in shaping the market through continuous product innovations and strategic distribution networks. Their focus on quality, taste, and convenience positions them as leaders in the UAE hummus market.
Market Insights
- The UAE hummus market is projected to grow from USD 10.03 million in 2023 to USD 19.70 million by 2032, with a CAGR of 8.81%, reflecting strong demand for versatile and nutritious food options.
- Rising health awareness and the adoption of plant-based diets are major drivers, as consumers increasingly seek nutrient-rich and vegan-friendly options like hummus.
- Manufacturers focus on flavor innovation, clean-label offerings, and convenient packaging formats to cater to diverse consumer preferences and boost market appeal.
- Limited shelf life and reliance on imported ingredients, such as chickpeas and tahini, pose logistical and cost challenges for manufacturers in the UAE market.
- Dubai and Abu Dhabi lead the market due to their multicultural populations, higher disposable incomes, and advanced retail infrastructure, driving higher hummus consumption.
- Untapped potential in smaller emirates, coupled with the growth of online grocery platforms, offers opportunities for market expansion and consumer outreach.
- Key players like Sabra Dipping Company and Al Wadi Al Akhdar dominate through robust distribution networks and continuous product innovation, fostering intense competition.
Market Drivers
Rising Health Consciousness and Preference for Plant-Based Diets
The increasing awareness of health and wellness among UAE consumers is a pivotal driver for the hummus market. Hummus, recognized for its high nutritional value, aligns well with the growing demand for functional foods that promote health. For instance, it is rich in protein, fiber, vitamins, and essential minerals, making it particularly appealing to health-conscious individuals seeking nutritious options. The global shift toward plant-based diets has further amplified this demand; hummus serves as an excellent alternative protein source for vegetarians and vegans. Its versatility in pairing with various dishes enhances its appeal among diverse consumer groups. Moreover, the UAE faces significant health challenges, such as obesity and diabetes, prompting a focus on healthier dietary options. Hummus stands out as a nutrient-dense food choice that meets the needs of consumers looking to improve their dietary habits. As individuals become more educated about nutrition and the benefits of plant-based eating, the popularity of hummus continues to rise. This trend reflects a broader movement towards healthier lifestyles, where consumers prioritize foods that not only taste good but also contribute positively to their overall well-being.
Expanding Multicultural Population and Culinary Influences
The UAE's demographic composition, marked by a significant expatriate population, is a key factor driving hummus consumption. For instance, the presence of individuals from diverse cultural backgrounds has led to an exponential growth in the adoption of Middle Eastern cuisine, including hummus. This multicultural environment fosters culinary fusion that boosts the popularity of hummus among both locals and expatriates. As hummus is already a staple in Middle Eastern cuisine, it resonates deeply with these diverse groups.Foodservice outlets, including restaurants and cafes, have capitalized on this trend by incorporating hummus into their menus in innovative ways. This not only enhances the dining experience but also reinforces hummus's status as a versatile dish suitable for various palates. The integration of hummus into modern culinary practices reflects the UAE's dynamic food culture and highlights its role as a bridge between traditional Middle Eastern flavors and contemporary dining preferences.
Innovation in Flavors, Packaging, and Product Formats
Manufacturers are actively leveraging product innovation to capture a wider consumer base in the UAE hummus market. Traditional hummus, while still popular, is now available in a variety of flavors such as roasted red pepper, garlic, jalapeño, and beetroot, catering to evolving consumer preferences. These innovations enhance product appeal and encourage repeat purchases among customers looking for novel culinary experiences. Moreover, advancements in packaging technology, such as resealable tubs and single-serving portions, have improved product convenience and shelf life. These features cater to the fast-paced lifestyles of UAE consumers, particularly in urban areas, making hummus a convenient snacking option.
Growth of Retail and E-commerce Channels
The proliferation of modern retail outlets and the rapid adoption of e-commerce platforms have significantly contributed to the growth of the UAE hummus market. Supermarkets, hypermarkets, and specialty stores provide consumers with easy access to a wide variety of hummus products. E-commerce platforms have further expanded market reach, allowing consumers to order hummus online for home delivery. This shift toward digital purchasing is driven by the UAE's high internet penetration rate and the increasing preference for convenience. Retailers and online platforms have also adopted promotional strategies such as discounts and combo offers, further driving consumer engagement and market growth.
Market Trends
Increased Demand for Organic and Clean-Label Products
One of the prominent trends in the UAE hummus market is the growing preference for organic and clean-label products. Consumers are increasingly prioritizing food items that are free from artificial additives, preservatives, and genetically modified ingredients. This trend is driven by heightened health awareness and the demand for transparency in food production. For instance, a significant number of consumers in the UAE are actively seeking hummus products that prioritize natural ingredients and transparency in labeling. This shift is evident as local brands adopt clean label practices, ensuring their products are free from synthetic chemicals. Reports indicate that awareness about organic food consumption has risen sharply, reflecting a strong consumer inclination towards healthier options. Organic hummus, often made with premium-quality chickpeas, tahini, and olive oil, caters to this demand. Leading manufacturers are now labeling their products to highlight their organic and preservative-free status, appealing to health-conscious segments. The growing health consciousness among consumers has led to a surge in demand for organic variants, encouraging local producers and artisanal brands to enter the market with unique offerings that emphasize sustainability and natural ingredients.
Expansion of Flavors and Fusion Variants
The UAE’s multicultural demographic has influenced a trend toward innovative flavors and fusion variants in the hummus market. While traditional hummus remains a staple, consumers are showing interest in bold and unconventional flavors such as sun-dried tomato, basil pesto, spicy harissa, and even dessert-inspired sweet hummus. For instance, manufacturers are introducing unique flavors to appeal to adventurous eaters. This diversification reflects a broader trend where traditional hummus is being reimagined with global influences—such as Asian-inspired sesame hummus or Indian masala hummus—attracting expatriates and younger consumers eager to explore new taste experiences. The introduction of dessert-inspired hummus flavors further exemplifies this trend, showcasing how brands are creatively expanding their product offerings. These innovative offerings not only cater to adventurous palates but also keep the product appealing to a broader audience, ensuring that hummus remains relevant in a competitive market.
Growth in Foodservice Integration and On-the-Go Formats
The integration of hummus into foodservice menus is a significant trend shaping the UAE market. Restaurants, cafes, and quick-service establishments are increasingly incorporating hummus into diverse dishes, including wraps, salads, and mezze platters. Its versatility makes it a popular choice in both casual dining and high-end culinary settings. For example, restaurants are enhancing their menus by incorporating hummus into various dishes, which showcases its adaptability as a meal component. Additionally, the emergence of on-the-go formats has catered to the fast-paced lifestyles of urban consumers. Single-serving hummus cups paired with vegetable sticks or pita chips have gained popularity among working professionals seeking convenient yet nutritious snack options. This trend aligns with the growing demand for healthy snacks that can be consumed quickly without compromising on quality or taste.
Surge in E-commerce and Online Grocery Platforms
The rapid digitalization of the UAE retail sector has significantly impacted the hummus market, with e-commerce and online grocery platforms playing a vital role. High internet penetration and the adoption of online shopping habits have led to an increase in the availability and visibility of hummus products online. For instance, many consumers now prefer shopping online for groceries, including niche brands of hummus that may not be available in traditional stores. E-commerce platforms have expanded their offerings to include a wide variety of hummus flavors and organic options, making it easier for health-conscious consumers to access these products from home. Reports indicate that online grocery shopping habits have surged post-pandemic, further solidifying e-commerce as a critical channel for hummus sales. Many platforms also offer discounts, subscription services, and bundled deals that enhance consumer engagement while encouraging manufacturers to partner with online retailers to strengthen their market presence.
Market Challenges
Intense Market Competition and Price Sensitivity
The UAE hummus market faces significant challenges due to intense competition among both local and international players. Established brands, artisanal producers, and private-label products all vie for consumer attention, creating a crowded marketplace. This heightened competition has led to price sensitivity among consumers, with many prioritizing cost over brand loyalty. Smaller manufacturers often struggle to compete with larger players that have the advantage of economies of scale, enabling them to offer competitive pricing. Additionally, the influx of private-label products from retail chains adds further pressure by offering lower-cost alternatives. The need to balance affordability with product quality and innovation remains a persistent challenge for market players.
Limited Shelf Life and Supply Chain Complexities
Hummus, being a perishable product, has a limited shelf life, which poses logistical and supply chain challenges. Maintaining the freshness and quality of hummus products during storage and transportation is crucial to meet consumer expectations and regulatory standards. In the UAE, where temperatures can be extreme, ensuring proper cold-chain logistics is particularly critical. Any disruption in refrigeration during transit or storage can lead to spoilage, resulting in financial losses and reputational damage for brands. Furthermore, the reliance on imported ingredients such as chickpeas and tahini makes the market vulnerable to fluctuations in global supply chains. Challenges like rising freight costs, delays, and ingredient shortages can directly impact production timelines and pricing strategies.
Market Opportunities
Growing Demand for Health-Oriented and Innovative Products
The UAE hummus market offers significant opportunities driven by the increasing demand for health-oriented and innovative food products. Consumers are becoming more health-conscious and seeking options that align with dietary preferences, such as organic, vegan, and clean-label products. This trend opens doors for manufacturers to expand their portfolios with fortified hummus variants enriched with superfoods like flaxseed, quinoa, or spirulina, catering to niche health-focused segments. Moreover, innovation in flavor profiles, such as spicy, sweet, or global fusion flavors, can attract diverse consumer groups, including younger demographics and expatriates who value unique culinary experiences. Capitalizing on this trend allows brands to differentiate themselves and build consumer loyalty.
Expansion Through E-commerce and Strategic Partnerships
The rapid growth of e-commerce platforms in the UAE presents a lucrative opportunity for hummus manufacturers to broaden their reach and engage with tech-savvy consumers. By establishing strong online presences through partnerships with leading grocery delivery services and investing in direct-to-consumer platforms, companies can tap into the convenience-driven shopping habits of modern consumers. Additionally, collaborations with foodservice providers, such as restaurants, cafes, and catering services, can boost product visibility and foster brand recognition. Expanding distribution networks to include retail giants and specialty stores ensures accessibility across urban and suburban markets, further driving growth in the hummus sector.
Market Segmentation Analysis
By Product
The UAE hummus market is segmented into Classic Hummus, Roasted Garlic Hummus, White Bean Hummus, Black Olive Hummus, and Others. Among these, classic hummus dominates due to its traditional appeal and widespread acceptance among consumers. However, flavored variants like roasted garlic and black olive hummus are witnessing growing demand as consumers seek innovative and diverse options. These variants cater to evolving taste preferences, particularly among younger demographics and expatriates seeking novel culinary experiences.
By Packaging Type
The market is categorized into Tubs & Cups, Jars & Bottles, and Others based on packaging type. Tubs and cups hold the largest share, offering convenience and portion control, which align with modern consumer lifestyles. Jars and bottles, often associated with premium products, are gaining popularity among health-conscious and gourmet-focused consumers. Innovative packaging solutions that improve shelf life and portability further drive demand in this segment.
Segments
Based on product
- Classic Latin America Hummus
- Roasted Garlic Latin America Hummus
- White Bean Latin America Hummus
- Black Olive Latin America Hummus
- Others
Based on Packaging type
- Tubs & Cups
- Jars & Bottles
- Others
Based on Ingredient type
- Chickpeas
- Tahini
- Olive Oil
- Garlic
- Others
Based on Distribution channel
- Supermarkets & Hypermarkets
- Convenience Stores
- Grocery Stores
- Online Retailers
- Others
Based on region
- Dubai
- Abu Dhabi
Regional Analysis
Dubai (40%):
Dubai accounts for the largest share of the UAE hummus market, contributing approximately 40% of the overall revenue in 2023. Its cosmopolitan population, composed of expatriates and locals, has fostered widespread adoption of hummus as a versatile and healthy food option. Dubai’s vibrant foodservice industry, with its extensive network of fine dining establishments, quick-service restaurants, and cafes, significantly supports the market. Additionally, the region’s strategic position as a global tourism hub ensures consistent demand for hummus from both residents and international visitors.
Abu Dhabi (30%):
Abu Dhabi captures an estimated 30% of the market share, driven by its affluent population and high per capita income. The capital city's growing awareness of health and wellness trends, coupled with rising preferences for plant-based diets, has led to increased consumption of hummus. The presence of premium retail outlets and the promotion of traditional Middle Eastern cuisine in upscale dining establishments further enhance its market potential. Abu Dhabi’s investments in food production and distribution infrastructure also contribute to the market's growth.
Key players
- Sabra Dips
- Almarai
- Kraft Heinz
- Strauss Group
- Bakkavor
- Tribe Hummus
- Cedar's Mediterranean Foods
- Athenos
- Amara Foods
- Al Watanieh International Co.
- Lantana Foods
- Pelpac Inc.
- Haliburton International Foods Inc.
- Finnish Cheese Company
- Hope Foods
- Beirut Hummus
- Shukran Foods
- Alwadiah Food Industries
- Karaman
- SAVENCIA SA
Competitive Analysis
The UAE hummus market is characterized by a mix of global and regional players competing to capture consumer interest through product differentiation, quality, and affordability. Leading companies such as Sabra Dips, Almarai, and Kraft Heinz hold significant market shares due to their strong brand recognition, extensive distribution networks, and innovative product offerings. Regional players like Al Watanieh International Co. and Alwadiah Food Industries leverage their local expertise and cultural relevance to appeal to Middle Eastern consumers.Smaller, artisanal brands also play a vital role by offering organic, clean-label, and unique flavor profiles, catering to niche market segments. The competition is further intensified by private-label products introduced by major retailers, providing cost-effective options. Companies in the market focus on expanding their product portfolios, enhancing supply chain efficiency, and leveraging digital retail channels to maintain competitiveness and address evolving consumer preferences.
Recent Developments
- In August 2023, Sabra Dips launched a new line of flavored hummus in collaboration with Frank's RedHot and Stubb's, introducing flavors such as Buffalo Hummus and BBQ Hummus. This expansion aims to cater to the growing demand for innovative and bold flavors in the hummus market, particularly among younger consumers seeking exciting snack options.
- On December 4, 2024, Almarai announced its acquisition of Hammoudeh Food Industries for approximately $70 million. Although Hammoudeh primarily focuses on dairy products, this acquisition is part of Almarai's broader strategy to diversify its product offerings, which may include expanding into the hummus segment as part of its commitment to enhance its presence in the Middle East food market.
- In early 2024, Kraft Heinz announced plans to introduce a range of organic and plant-based dips, including hummus variants, to align with the increasing consumer preference for healthier snack options. This initiative reflects Kraft Heinz's strategy to tap into the growing health-conscious demographic in the UAE.
- In December 2023, Strauss Group reported that their Sabra brand is unlikely to regain its previous market share in the U.S. due to increased competition. This acknowledgment has prompted Strauss Group to focus on enhancing its product offerings globally, including potential expansions into the UAE market where hummus consumption is on the rise.
- On January 16, 2025, Bakkavor Group announced strong revenue growth for FY24, driven by increased demand for fresh prepared foods, including hummus. The company plans to leverage this momentum by expanding its distribution channels in the UAE, aiming to meet the rising consumer demand for convenient and healthy snack options.
- In January 2024, Cedar's Mediterranean Foods announced plans to increase production capacity at its facilities. This expansion will allow Cedar's to better serve markets like the UAE, where demand for high-quality hummus products continues to grow amidst rising health consciousness among consumers.
- In December 2024, Al Watanieh International Co. expanded its distribution network for hummus products across major retail outlets in the UAE. This move is designed to increase accessibility for consumers looking for traditional and innovative hummus varieties.
- On August 20, 2024, Lantana Foods rebranded its hummus line with a focus on "Fusion Hummus" flavors. The new packaging emphasizes sustainability and aims to attract environmentally conscious consumers in markets like the UAE where unique flavor combinations are gaining popularity.
- In early 2024, Haliburton International Foods announced plans to enhance their online sales strategy for hummus products targeting the UAE market. This initiative aims to capitalize on the growing trend of online grocery shopping among consumers seeking convenient access to healthy food options.
- As of January 2025, Beirut Hummus has expanded its distribution channels within Dubai. The brand focuses on authentic Lebanese recipes that resonate well with both local consumers and expatriates looking for traditional flavors.
- In December 2024, Alwadiah Food Industries announced plans to expand their production facilities dedicated to hummus production in response to increasing demand from local retailers across the UAE.
- In October 2024, SAVENCIA SA acquired Hope Foods as part of their strategy to strengthen their presence in plant-based dips including hummus. This acquisition is expected to enhance their product portfolio significantly within markets like the UAE where demand for healthy alternatives is rising.
Market Concentration and Characteristics
The UAE hummus market exhibits a moderately concentrated structure, with a mix of global giants and regional players driving competition. Leading companies such as Sabra Dips, Kraft Heinz, and Almarai dominate due to their strong brand presence, extensive distribution networks, and diverse product portfolios. These major players are complemented by smaller regional and artisanal brands like Al Watanieh International Co. and Cedar's Mediterranean Foods, which cater to niche consumer preferences for authentic and locally inspired products. The market is characterized by innovation in flavor profiles, packaging, and clean-label offerings, reflecting the evolving tastes and health-consciousness of UAE consumers. Additionally, the rising influence of private-label products from retail giants further shapes the competitive landscape, offering affordable options that intensify market dynamics.
Report Coverage
The research report offers an in-depth analysis based on product, Packaging type, Ingredient type, Distribution channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The UAE hummus market is expected to maintain robust growth, driven by increasing health consciousness and rising demand for plant-based and nutrient-rich foods.
- The market will see a surge in organic and clean-label hummus products as consumers prioritize natural, preservative-free options aligned with wellness trends.
- Manufacturers will continue to innovate with unique and bold flavor combinations, including fusion and seasonal variants, to attract diverse consumer segments.
- On-the-go and single-serving packaging formats will gain traction, catering to the fast-paced lifestyles of urban consumers seeking convenient snacking solutions.
- The growth of e-commerce and online grocery platforms will expand the availability and accessibility of hummus products, reaching a wider audience.
- The incorporation of hummus into restaurant and cafe menus as a versatile ingredient will bolster demand through the foodservice sector.
- Consumers' growing concern for sustainability will drive demand for eco-friendly packaging and locally sourced ingredients in hummus production.
- Beyond Dubai and Abu Dhabi, untapped growth potential exists in smaller emirates as urbanization and disposable incomes rise in these regions.
- Innovations in food processing and preservation techniques will improve product shelf life and quality, ensuring a competitive edge for manufacturers.
- Partnerships between global brands, local producers, and retail chains will strengthen distribution networks and enhance market penetration.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the UAE Hummus Market in 2023 and 2032, and its CAGR?
What factors are driving the growth of the UAE hummus market?
Which regions dominate the UAE hummus market?
Who are the key players in the UAE hummus market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 UAE Hummus Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global UAE Hummus Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 10.03 million → 2032: USD 19.70 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 UAE Hummus Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. UAE Hummus Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 UAE Hummus Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 UAE Hummus Market Drivers
- 3.3 UAE Hummus Market Restraints & Challenges
- 3.4 UAE Hummus Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 UAE Hummus Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 UAE Hummus Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, UAE Hummus category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 UAE Hummus Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. UAE Hummus Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the UAE Hummus market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 UAE Hummus Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 UAE Hummus Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 UAE Hummus Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in UAE Hummus (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New UAE Hummus Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global UAE Hummus Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America UAE Hummus Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe UAE Hummus Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific UAE Hummus Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America UAE Hummus Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East UAE Hummus Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa UAE Hummus Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. UAE Hummus Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
