
Market Overview
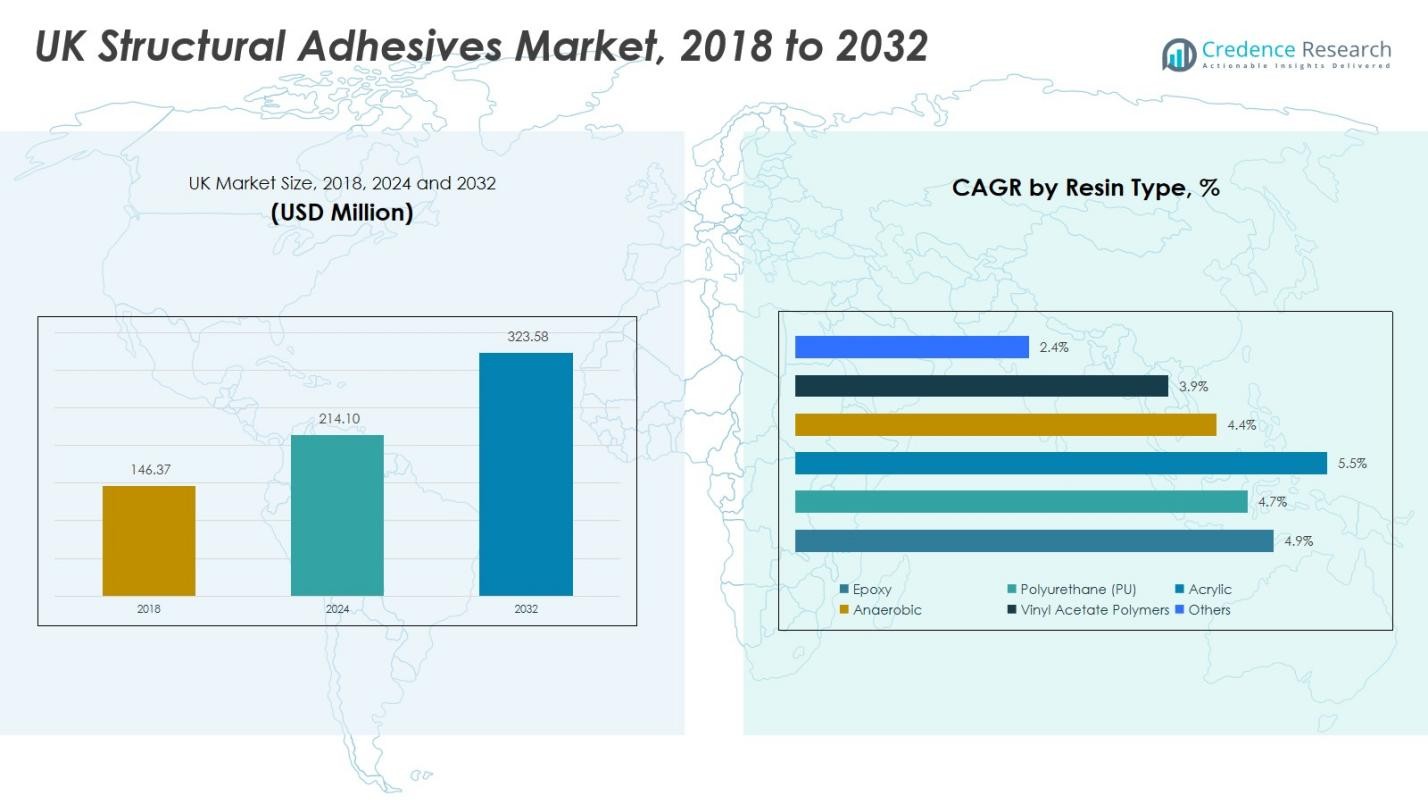
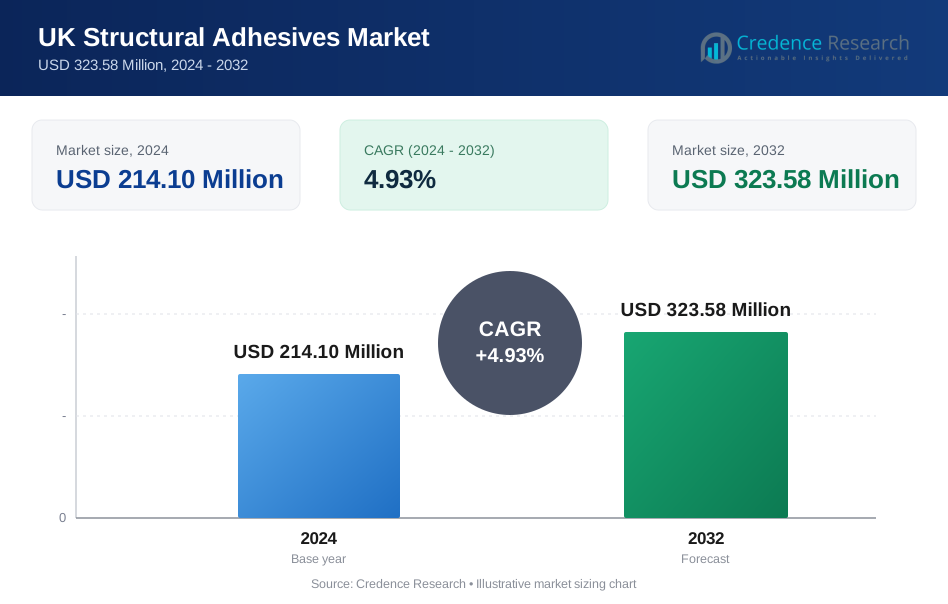
UK Structural Adhesives Market size was valued at USD 146.37 Million in 2018, increased to USD 214.10 Million in 2024, and is anticipated to reach USD 323.58 Million by 2032, growing at a CAGR of 4.93% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| UK Structural Adhesives Market Size 2024 | USD 214.10 Million |
| UK Structural Adhesives Market, CAGR | 4.93% |
| UK Structural Adhesives Market Size 2032 | USD 323.58 Million |
The UK Structural Adhesives Market is highly competitive, with leading players including Henkel AG & Co. KGaA, Sika AG, RPM International Inc., Huntsman Corporation, Arkema S.A., H.B. Fuller Company, Dow Inc., 3M Company, Lord Corporation, and L&L Products, Inc. These companies leverage strong product portfolios, advanced adhesive technologies, and extensive distribution networks to maintain market dominance. Strategic initiatives such as mergers, acquisitions, partnerships, and continuous R&D investments enable them to enhance performance, develop eco-friendly solutions, and expand their regional reach. England emerges as the leading region in the UK Structural Adhesives Market, commanding a significant 55% of total revenue, driven by robust automotive, aerospace, and construction sectors. High adoption of epoxy and polyurethane adhesives across metal, composite, and plastic substrates further strengthens England’s market position, supporting long-term growth and reinforcing its prominence within the UK structural adhesives landscape.
Market Insights
- The UK Structural Adhesives Market was valued at USD 214.10 Million in 2024 and is projected to reach USD 323.58 Million by 2032, growing at a CAGR of 4.93%.
- Rising demand from automotive, aerospace, and construction sectors drives growth, as manufacturers adopt lightweight materials and high-performance adhesives for better fuel efficiency, structural integrity, and assembly efficiency.
- Market trends indicate a shift toward eco-friendly and water-based adhesives, along with growing adoption of composite materials in industrial and transportation applications, presenting opportunities for advanced epoxy and polyurethane formulations.
- The competitive landscape is dominated by Henkel AG & Co. KGaA, Sika AG, RPM International Inc., Huntsman Corporation, Arkema S.A., H.B. Fuller Company, Dow Inc., 3M Company, Lord Corporation, and L&L Products, Inc., who focus on R&D, partnerships, and innovative product offerings.
- England leads regional demand with 55% market share, followed by Scotland (15%), Wales (10%), Northern Ireland (8%), and other regions (12%), while epoxy resins and metal substrates are the dominant segments.
Market Segmentation Analysis:
By Resin Type:
The epoxy resin segment dominates the UK structural adhesives market, accounting for approximately 38% of the total revenue. Its superior mechanical strength, chemical resistance, and versatility across industries, including automotive and aerospace, drive its widespread adoption. Polyurethane (PU) and acrylic resins follow, offering flexibility and fast-curing properties suitable for specialized applications. Anaerobic and vinyl acetate polymers cater to niche markets, while others capture smaller shares. Overall, rising demand for durable bonding solutions in automotive assembly, infrastructure, and industrial manufacturing continues to propel the epoxy segment, reinforcing its leading position in the resin-type category.
For instance, Henkel’s Loctite epoxy adhesives are extensively used in automotive metal bonding, providing high durability to withstand harsh conditions.
By Substrate:
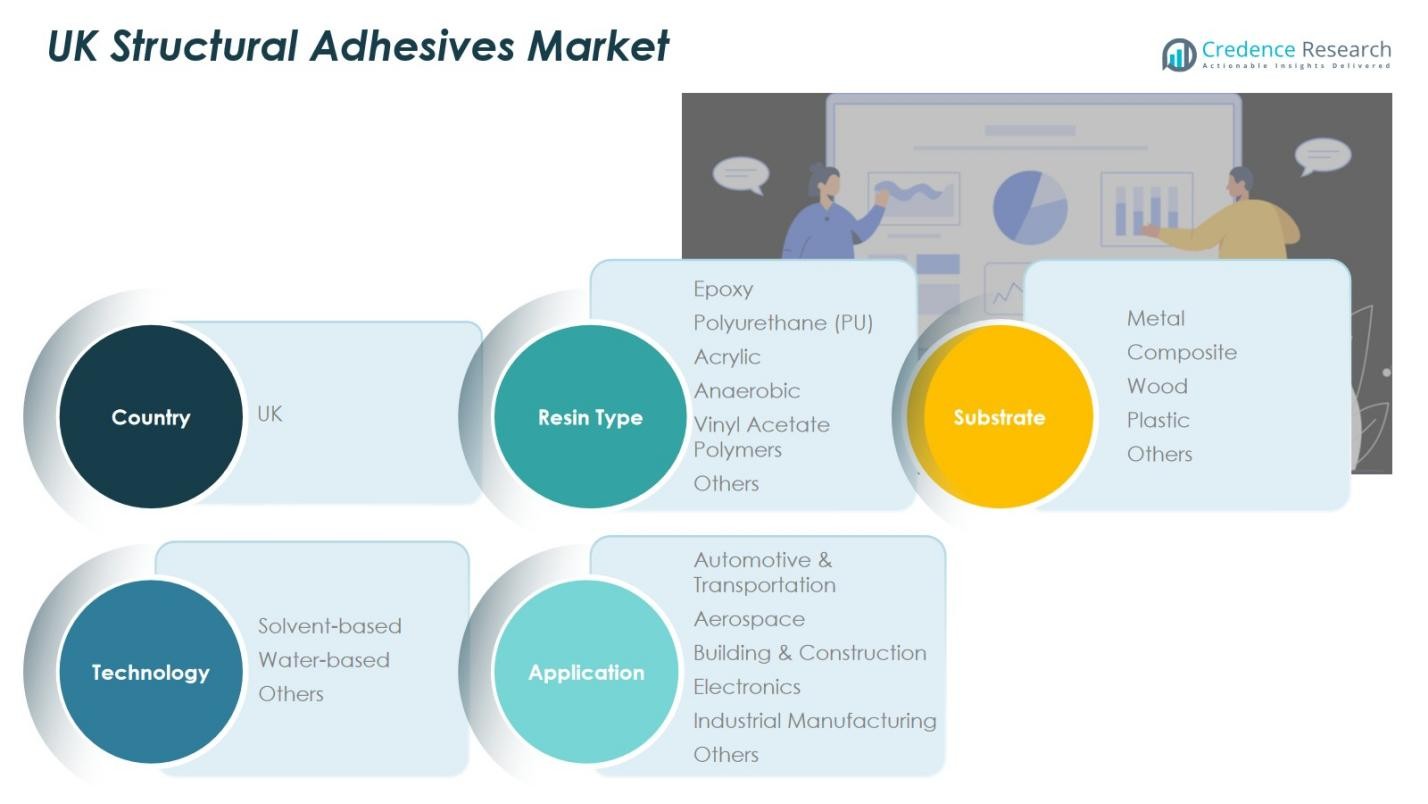
Metal substrates represent the dominant sub-segment, contributing nearly 45% of UK structural adhesives market revenue. The growth is primarily fueled by increasing use of lightweight metals in automotive and aerospace applications, requiring strong adhesive bonding to replace traditional mechanical fasteners. Composites and wood substrates are gaining traction due to rising adoption in construction and furniture sectors, while plastics hold a moderate share, driven by electronic and packaging applications. The demand for enhanced structural integrity, corrosion resistance, and assembly efficiency remains the key driver supporting metal as the leading substrate in the UK market.
For instance, Sika’s SikaPower® epoxy adhesives, based on SmartCore® technology, provide exceptional fatigue resistance and superior corrosion protection for metal-to-metal bonding in lightweight structures, supporting automotive manufacturers in reducing vehicle weight while maintaining strength.
By Technology:
Solvent-based adhesives hold a leading share of around 42% in the UK market, favored for their robust bonding performance across metals, composites, and plastics. Their fast curing, high strength, and adaptability in high-stress applications make them widely adopted in automotive, aerospace, and industrial sectors. Water-based adhesives are growing steadily due to environmental regulations and the demand for eco-friendly solutions, while other technologies, including hot-melt and UV-curable adhesives, cater to niche applications. Increasing emphasis on sustainable manufacturing, efficiency, and high-performance bonding drives the dominance of solvent-based technologies in the UK structural adhesives market.
Key Growth Drivers
Rising Automotive & Aerospace Production
The expansion of the automotive and aerospace sectors in the UK significantly drives demand for structural adhesives. Increasing use of lightweight materials like aluminum and composites in vehicle and aircraft manufacturing requires high-strength bonding solutions to replace traditional mechanical fasteners. This shift enhances fuel efficiency and structural performance, promoting the adoption of epoxy and polyurethane adhesives. Additionally, stringent safety and emission standards necessitate durable and reliable adhesive solutions, further propelling market growth and reinforcing the prominence of structural adhesives across transportation industries.
For instance, companies like ThreeBond have developed acrylic-based structural adhesives specifically engineered to provide robust bonding for lightweight automotive materials such as aluminum and carbon fiber-reinforced polymers, enhancing crash safety and corrosion resistance.
Infrastructure and Construction Development
Ongoing infrastructure projects and modern construction practices in the UK contribute to market growth. Structural adhesives are increasingly preferred over mechanical fasteners for bonding metals, composites, and wood due to their strength, durability, and ability to reduce assembly time. Applications in bridges, buildings, and industrial facilities drive the demand for water-based and solvent-based adhesives. The push toward sustainable construction materials and efficient assembly processes supports higher adoption rates, making construction a critical growth driver for the UK structural adhesives market.
For instance, Structural Adhesives Ltd developed an A2 Fire Rated Epoxy Adhesive recognized with the King’s Award for Enterprise in Innovation, used to enhance fire safety in high-rise buildings and critical infrastructure.
Technological Advancements in Adhesives
Innovations in adhesive chemistry and formulation have expanded the application range of structural adhesives. Advanced epoxy, acrylic, and polyurethane adhesives now offer faster curing times, higher mechanical strength, and improved chemical resistance. These technological developments enable bonding of diverse substrates like metals, composites, and plastics across automotive, aerospace, and industrial sectors. As manufacturers seek reliable and high-performance solutions for lightweight and complex assemblies, the continuous enhancement of adhesive technologies fuels market expansion and reinforces adoption across multiple end-use industries.
Key Trends & Opportunities
Shift Toward Eco-Friendly Adhesives
Sustainability is reshaping the UK structural adhesives market, with a growing preference for water-based and low-VOC adhesives. Environmental regulations and corporate sustainability goals encourage manufacturers to adopt eco-friendly solutions without compromising performance. This trend creates opportunities for R&D investments in green adhesive formulations and enables companies to differentiate their product offerings. The shift toward environmentally responsible adhesives aligns with consumer expectations and regulatory compliance, presenting significant growth potential for players focusing on sustainable and high-performance adhesive solutions.
For instance, DuPont developed MEGUM™ W 9500, a heat-reactive, water-based adhesive delivering strong bonds with reduced harmful emissions.
Expansion in Composite Material Applications
The increasing use of composite materials across automotive, aerospace, and industrial sectors presents substantial opportunities for structural adhesives. Composites require specialized bonding solutions to maintain strength, flexibility, and durability, driving demand for advanced epoxy and polyurethane adhesives. As manufacturers prioritize lightweight and energy-efficient materials, the market can capitalize on adhesives that deliver reliable performance in complex assemblies. Growth in composite adoption across emerging applications, such as electric vehicles and renewable energy components, further strengthens the market outlook for structural adhesives in the UK.
For instance, Boeing’s 787 Dreamliner incorporates about 50% of its structure by weight using carbon fiber-reinforced polymer composites, enhancing fuel efficiency by 20-30%, which necessitates strong, durable adhesives to maintain structural integrity.
Key Challenges
High Cost of Advanced Adhesives
The premium pricing of high-performance structural adhesives, such as advanced epoxies and polyurethanes, limits adoption among small and medium enterprises. While these adhesives offer superior strength and chemical resistance, the high cost can deter cost-sensitive manufacturers from replacing traditional bonding methods. This challenge constrains market penetration in certain segments, particularly where budget limitations outweigh performance requirements. Companies must balance innovation with affordability to expand adoption while maintaining profitability in the competitive UK structural adhesives market.
Stringent Regulatory Compliance
Compliance with environmental and safety regulations poses challenges for structural adhesive manufacturers. VOC emissions, chemical content restrictions, and workplace safety standards require continuous formulation adjustments and testing, increasing production complexity and costs. Failure to meet regulatory requirements can result in penalties and market restrictions. Navigating this regulatory landscape while maintaining product performance and market competitiveness remains a key challenge, necessitating strategic investments in R&D and quality assurance for sustained growth in the UK market.
Regional Analysis
England
England dominates the UK structural adhesives market, accounting for 55% of total revenue. The region’s robust automotive, aerospace, and construction industries drive strong demand for high-performance adhesives. Manufacturers increasingly adopt epoxy and polyurethane adhesives for metal, composite, and plastic substrates to improve assembly efficiency and structural strength. Rising investment in infrastructure projects and transportation networks further fuels market growth. The presence of major adhesive manufacturers and R&D centers in England supports product innovation and distribution. Increasing adoption of eco-friendly and water-based adhesives in industrial and commercial applications reinforces England’s leading position in the UK market.
Scotland
Scotland holds a 15% share of the UK structural adhesives market, driven by growth in construction, renewable energy, and aerospace sectors. Structural adhesives are widely used for bonding metals, composites, and wood in industrial and infrastructure projects. Rising government initiatives to promote sustainable construction practices favor the adoption of water-based and low-VOC adhesives. The region’s emphasis on renewable energy installations, such as wind and offshore projects, requires high-strength bonding solutions for durable performance. Additionally, the presence of small-to-medium adhesive manufacturers catering to specialized applications supports market expansion in Scotland.
Wales
Wales contributes 10% to the UK structural adhesives market, largely supported by construction, automotive component manufacturing, and industrial applications. Structural adhesives are increasingly used to join metals, composites, and plastics, replacing traditional mechanical fasteners. The growth is driven by ongoing infrastructure development and industrial modernization projects. Rising demand for lightweight, high-performance bonding solutions in automotive and aerospace sectors also supports market expansion. The adoption of eco-friendly and solvent-free adhesive technologies aligns with regional sustainability goals, further strengthening market penetration. Wales continues to show steady growth due to government-backed development programs and rising industrial investments.
Northern Ireland
Northern Ireland accounts for 8% of the UK structural adhesives market, with growth fueled by manufacturing, construction, and aerospace sectors. Structural adhesives are preferred for joining metals, plastics, and composites in transportation and industrial assemblies. Government incentives supporting industrial modernization and sustainable construction practices drive demand for high-performance adhesives. Adoption of water-based and solvent-based adhesives is increasing, with epoxy and polyurethane dominating the market. The presence of regional manufacturers and growing demand from small-to-medium enterprises for reliable bonding solutions further supports market expansion. Northern Ireland demonstrates consistent growth potential within the UK structural adhesives landscape.
Other Regions
Other regions in the UK, including smaller industrial hubs and offshore installations, contribute 12% of the total market share. Demand is primarily driven by niche applications in industrial manufacturing, electronics, and specialized construction projects. Structural adhesives are increasingly adopted for bonding metals, composites, and plastics where high performance and durability are required. Growth in these regions is supported by local manufacturing activities, renewable energy projects, and the adoption of eco-friendly adhesive technologies. The focus on innovation, sustainable solutions, and high-strength bonding in emerging industrial sectors continues to enhance market opportunities across other UK regions.
Market Segmentations:
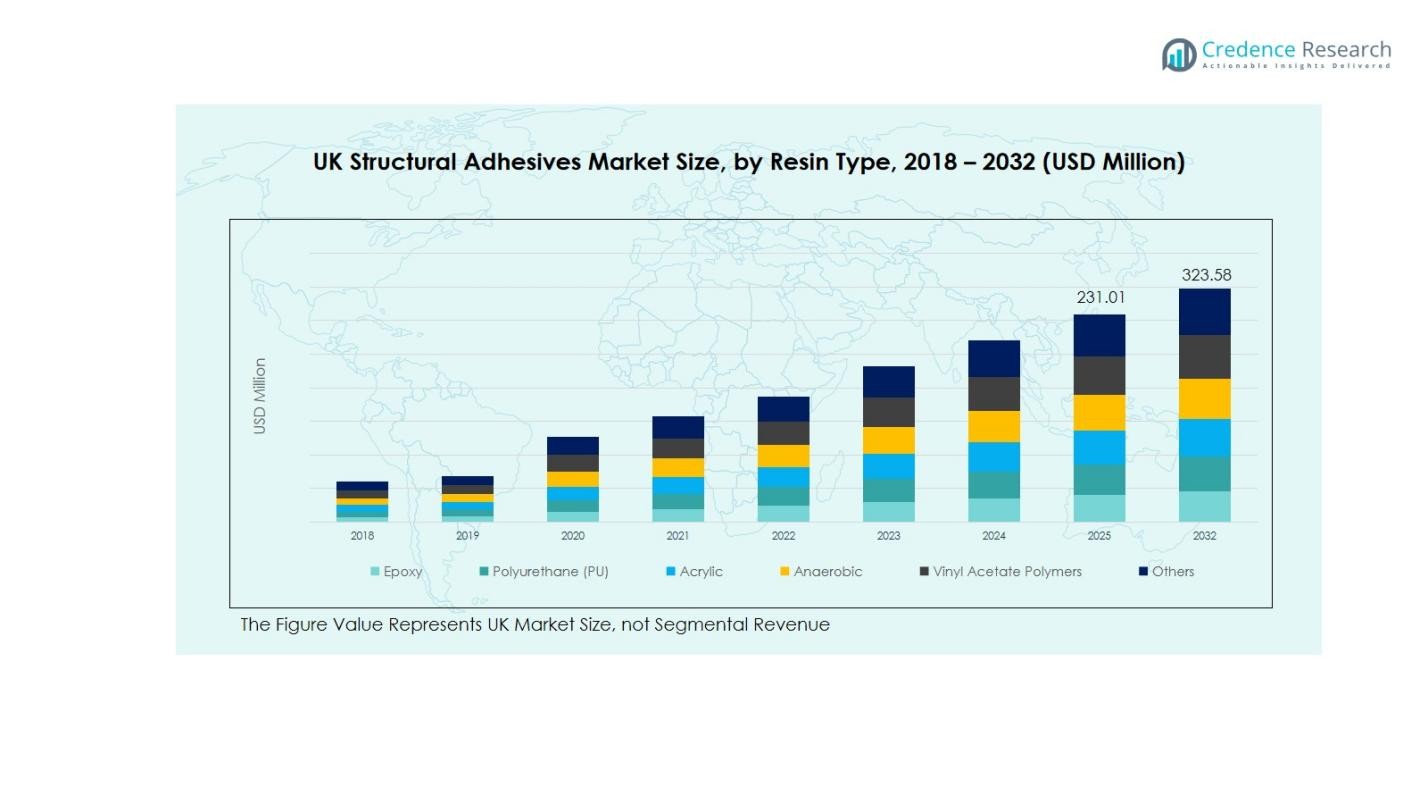
By Resin Type:
- Epoxy
- Polyurethane (PU)
- Acrylic
- Anaerobic
- Vinyl Acetate Polymers
- Others
By Substrate:
- Metal
- Composite
- Wood
- Plastic
- Others
By Technology:
- Solvent-based
- Water-based
- Others
By Application:
- Automotive & Transportation
- Aerospace
- Building & Construction
- Electronics
- Industrial Manufacturing
- Others
By Region:
- England
- Scotland
- Wales
- Northern Ireland
- Other Regions
Competitive Landscape
The competitive landscape of the UK structural adhesives market includes major players such as Henkel AG & Co. KGaA, Sika AG, RPM International Inc., Huntsman Corporation, Arkema S.A., H.B. Fuller Company, Dow Inc., 3M Company, Lord Corporation, and L&L Products, Inc. These companies dominate the market through strong product portfolios, extensive distribution networks, and continuous innovation in adhesive technologies. Strategic initiatives such as mergers, acquisitions, and partnerships enhance their market reach and technological capabilities. The market is characterized by high competition in epoxy and polyurethane segments, with companies focusing on developing eco-friendly, high-performance adhesives to meet evolving industrial and regulatory requirements. Investment in R&D to improve curing times, bonding strength, and substrate compatibility remains a key differentiator. Additionally, regional presence and tailored solutions for automotive, aerospace, and construction sectors strengthen the competitive positioning of these leading players in the UK market.
Key Player Analysis
- Henkel AG & Co. KGaA
- Sika AG
- RPM International Inc.
- Huntsman Corporation
- Arkema S.A.
- Dow Inc.
- 3M Company
- Lord Corporation
- L&L Products, Inc.
Recent Developments
- In March 2023, TECHSiL Ltd acquired Eurobond Adhesives to strengthen its product portfolio and expand its presence in the UK structural adhesives market.
- In June 2024, Meridian Adhesives Group expanded its UK footprint by acquiring Bondloc UK Ltd, a specialty adhesive manufacturer.
- In January 2025, Eurobond Adhesives, a division of the TECHSiL Group, unveiled innovative solutions at the Sign & Digital UK 2025 event, featuring its new hot melt adhesive, tecbond® 248.
Report Coverage
The research report offers an in-depth analysis based on Resin Type, Substrate, Technology, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The UK structural adhesives market is expected to grow steadily due to rising demand from automotive and aerospace sectors.
- Increasing adoption of lightweight materials in vehicles and aircraft will boost demand for high-performance adhesives.
- Expansion of infrastructure and construction projects across the UK will support market growth.
- Eco-friendly and water-based adhesives will gain traction as sustainability regulations tighten.
- Technological advancements in adhesive formulations will enhance bonding strength, curing time, and substrate compatibility.
- Rising use of composite materials in industrial and transportation applications will create new market opportunities.
- Small and medium enterprises are increasingly adopting structural adhesives for cost-effective and efficient assembly processes.
- The demand for adhesives in electronics and industrial manufacturing sectors will continue to grow.
- Strategic collaborations, partnerships, and R&D investments by key players will strengthen market competitiveness.
- Focus on lightweight, durable, and high-performance bonding solutions will drive long-term market expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for UK Structural Adhesives Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the UK Structural Adhesives Market projected to grow between 2025 and 2032?
Which UK Structural Adhesives Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the UK Structural Adhesives Market?
Who are the leading companies in the UK Structural Adhesives Market?
Which region commanded the largest share of the UK Structural Adhesives Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 214.10 Million → 2032: USD 323.58 Million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 UK Structural Adhesives Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 UK Structural Adhesives Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 UK Structural Adhesives Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 UK Structural Adhesives Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 UK Structural Adhesives Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 UK Structural Adhesives Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 UK Structural Adhesives Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 UK Structural Adhesives Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 214.10 Million → 2032: USD 323.58 Million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 UK Structural Adhesives Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 UK Structural Adhesives Geographic Market Outlook, 2024-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 UK Structural Adhesives Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 UK Structural Adhesives Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

