
Market Overview:
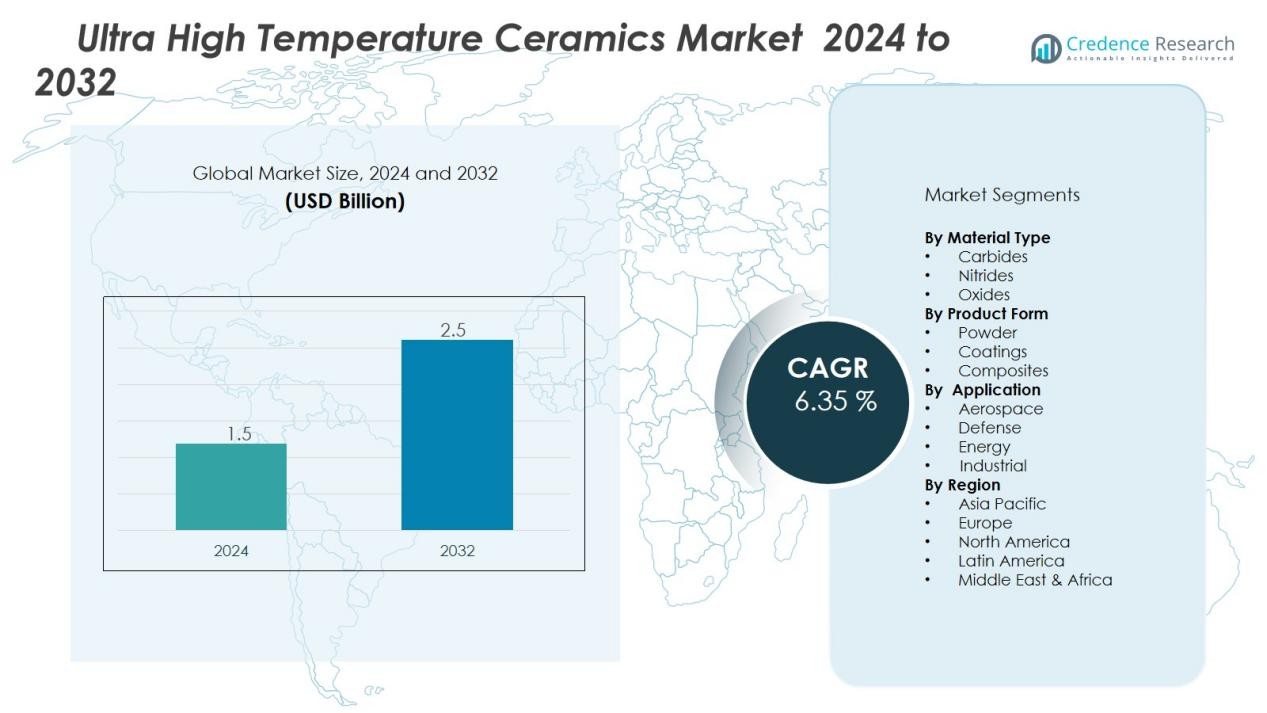
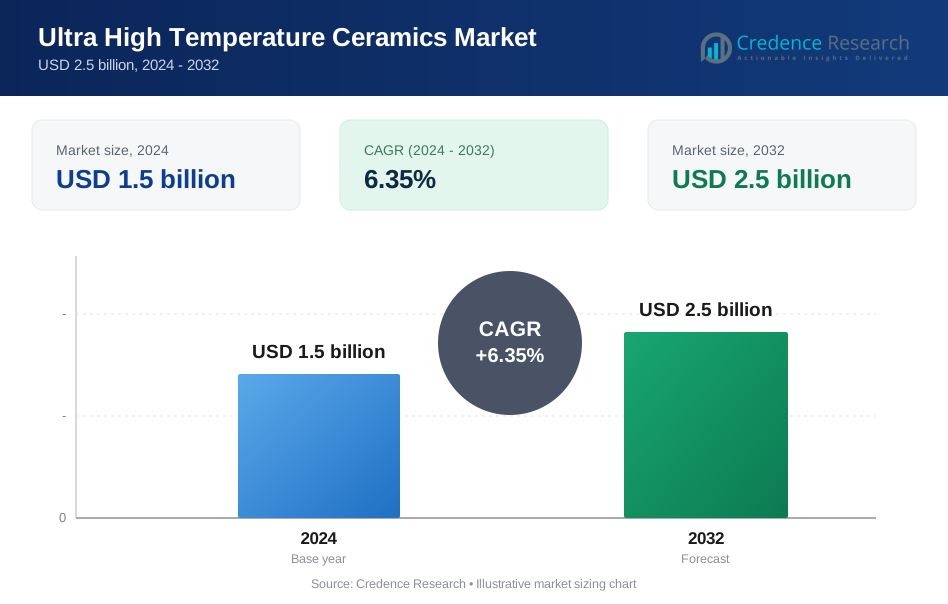
The ultra high temperature ceramics market size was valued at USD 1.5 billion in 2024 and is anticipated to reach USD 2.5 billion by 2032, at a CAGR of 6.35 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Ultra High Temperature Ceramics Market Size 2024 | USD 1.5 Billion |
| Ultra High Temperature Ceramics Market, CAGR | 6.35% |
| Ultra High Temperature Ceramics Market Size 2032 | USD 2.5 Billion |
Market drivers include the rising use of ultra high temperature ceramics in hypersonic vehicles, rocket propulsion systems, and thermal protection systems. Expanding focus on fuel efficiency and emission reduction encourages adoption in automotive and energy sectors. In addition, increasing defense budgets worldwide and growing space exploration programs boost demand. Advanced material innovations, including composites and improved manufacturing processes, further accelerate market penetration.
Regionally, North America holds a leading share due to strong aerospace and defense industries and ongoing NASA and DoD initiatives. Europe follows closely, driven by research in high-performance materials and space exploration projects. Asia-Pacific is projected to be the fastest-growing region, supported by rapid industrialization, increasing defense expenditure, and significant investments in hypersonic technologies by China and India. Latin America and the Middle East & Africa show emerging potential with infrastructure and energy applications.
Market Insights:
- The ultra high temperature ceramics market was valued at USD 1.5 billion in 2024 and is projected to reach USD 2.5 billion by 2032.
- Rising demand in aerospace and defense drives growth, with strong use in hypersonic vehicles, rocket propulsion, and thermal protection systems.
- Expanding space exploration programs in the United States, China, and India create new opportunities for thermal-resistant materials.
- Energy and industrial sectors adopt these ceramics for nuclear reactors, gas turbines, and hydrogen production systems, supporting efficiency and emission reduction.
- Technological advances in composites, fabrication, and additive manufacturing enhance performance, durability, and cost efficiency.
- Challenges include high production costs, rare raw material dependence, and limited commercialization beyond aerospace and defense.
- North America holds 38% market share, Europe follows with 28%, while Asia-Pacific at 24% emerges as the fastest-growing region.
Market Drivers:
Growing Demand from Aerospace and Defense Applications:
The ultra high temperature ceramics market benefits from the increasing demand in aerospace and defense. These materials are critical for thermal protection systems, rocket nozzles, and hypersonic vehicles. Their ability to maintain structural stability under extreme heat makes them indispensable for mission-critical applications. Governments and defense organizations are investing heavily in hypersonic technology programs, which directly drive adoption.
- For Instance, NASA and other researchers have tested hafnium diboride (HfB2) Ultra-High Temperature Ceramic (UHTC) composites for use as leading edges on hypersonic and re-entry vehicles. Test data indicate that UHTCs can maintain high strength under extreme thermal loads during simulated re-entry, with some hafnium diboride-silicon carbide composites showing strengths above 300 MPa.
Expansion of Space Exploration Programs:
The market gains momentum from growing global investments in space exploration. Countries such as the United States, China, and India are advancing space missions that require high-performance thermal materials. Ultra high temperature ceramics offer superior resistance in harsh re-entry conditions and propulsion systems. It supports the development of reusable launch vehicles and long-duration space missions. This rising demand for durable materials strengthens the market outlook.
- For instance, NASA's Thermal Protection Materials Branch has developed the Toughened Uni-Piece Fibrous Reinforced Oxidation-Resistant Composite (TUFROC), which withstands surface temperatures up to 2900°F and has been flight-tested successfully on multiple X-37B missions, supporting reusable space vehicles.
Rising Adoption in Energy and Industrial Sectors:
The ultra high temperature ceramics market experiences growth through adoption in energy and heavy industries. These ceramics provide efficiency in applications such as gas turbines, nuclear reactors, and advanced manufacturing. Their resistance to wear, oxidation, and extreme heat makes them ideal for improving energy conversion systems. Industries use these materials to meet stringent efficiency and emission standards. Growing emphasis on clean energy accelerates their use in critical infrastructure.
Technological Advancements and Material Innovations:
Ongoing innovation significantly contributes to market expansion. Advances in composites, fabrication techniques, and additive manufacturing improve product performance and cost efficiency. The ultra high temperature ceramics market benefits from research collaborations between academic institutions and commercial players. It enables the development of next-generation materials with enhanced durability and wider applications. These advancements expand opportunities across aerospace, defense, and industrial markets.
Market Trends:
Integration of Advanced Manufacturing and Additive Technologies:
The ultra high temperature ceramics market is witnessing a shift toward advanced production methods. Additive manufacturing and precision fabrication are enabling the creation of complex geometries with higher efficiency and reduced waste. These methods support the design of customized components for aerospace, defense, and energy applications. It improves scalability while lowering costs associated with traditional manufacturing. Companies are investing in 3D printing processes that enhance material performance and shorten development cycles. The trend also supports the use of hybrid composites that combine ceramics with other high-strength materials. This integration ensures broader adoption across industries requiring lightweight and heat-resistant components.
- For instance, Johns Hopkins University researchers successfully 3D printed ultra-high temperature carbide ceramics, specifically titanium carbide (TiC), achieving a product yield of up to 98.2 wt% TiC0.90, demonstrating high precision and material performance for aerospace applications.
Increasing Collaboration and Focus on Sustainable Solutions:
The market is shaped by stronger collaborations between industry players, research institutions, and government agencies. Partnerships are advancing new formulations of ceramics with greater thermal resistance and environmental durability. The ultra high temperature ceramics market is also aligning with sustainability goals by focusing on energy efficiency and reducing emissions in industrial processes. It supports innovations in gas turbines, nuclear energy systems, and renewable energy storage technologies. Global emphasis on hypersonic vehicle development and space missions further boosts collaborative research initiatives. Companies are also exploring eco-friendly manufacturing methods to minimize environmental impact while maintaining performance standards. This growing alignment of innovation and sustainability strengthens long-term market potential.
- For instance, the team led by researcher C. Xu recently demonstrated a laser sintering method that produces hafnium carbide (HfC) ultra-high temperature ceramic coatings capable of resisting temperatures near 1900°C with low oxidation damage after 5 minutes of flame exposure, representing a breakthrough in manufacturing complexity and performance.
Market Challenges Analysis:
High Production Costs and Complex Manufacturing Processes:
The ultra high temperature ceramics market faces significant challenges due to high production costs and complex processing requirements. Manufacturing these ceramics demands advanced facilities, specialized equipment, and precise control over high-temperature environments. It limits scalability and raises barriers for smaller manufacturers entering the market. The reliance on rare raw materials further contributes to elevated costs and supply constraints. Consistent quality assurance remains difficult because minor variations can compromise performance in critical applications. These challenges hinder widespread adoption across industries with budget-sensitive operations.
Limited Commercialization and Application Constraints:
The market also struggles with limited commercialization and restricted application scope beyond aerospace and defense. While ultra high temperature ceramics offer unmatched thermal properties, their brittleness and susceptibility to mechanical failure restrict broader use. It requires continuous research to improve toughness and reliability under varying operating conditions. The absence of standardized testing methods adds complexity for manufacturers and end users. High costs and uncertain return on investment discourage rapid adoption in energy and industrial sectors. These constraints collectively slow down the market’s ability to achieve mass adoption across emerging applications.
Market Opportunities:
Expansion into Emerging Energy and Industrial Applications:
The ultra high temperature ceramics market holds strong opportunities in advanced energy and industrial sectors. These materials can play a vital role in nuclear reactors, concentrated solar power, and hydrogen production systems. Their superior thermal resistance and chemical stability support energy efficiency and sustainability goals. It creates new pathways for adoption in industries seeking to reduce emissions and improve reliability. Demand for advanced ceramics in additive manufacturing further boosts potential across customized industrial applications. Growing focus on next-generation turbines and renewable infrastructure strengthens the opportunity for long-term growth.
Rising Investments in Aerospace, Defense, and Space Exploration:
The market is well-positioned to benefit from increasing investments in aerospace and defense technologies. Governments and private players are expanding programs in hypersonic vehicles, reusable launch systems, and thermal protection systems. The ultra high temperature ceramics market can address these needs by delivering high-performance and reliable materials. It enables improved mission safety, cost efficiency, and durability in extreme conditions. International collaborations in space exploration open further opportunities for adoption in propulsion and re-entry systems. Growing budgets for defense modernization across major economies reinforce the market’s potential. These expanding applications provide strong momentum for global growth.
Market Segmentation Analysis:
By Material Type:
The ultra high temperature ceramics market is segmented into carbides, nitrides, and oxides. Carbides such as zirconium carbide and hafnium carbide dominate due to exceptional thermal resistance and stability. Nitrides like silicon nitride are gaining traction for their toughness and wear resistance. Oxides, while less heat-tolerant, provide cost efficiency and wider availability. It creates diverse options for industries seeking balance between performance and affordability.
- For instance, CoorsTek's silicon nitride ceramics achieve flexural strengths of up to 1000 MPa and fracture toughness values around 6 MPa·m^1/2, maintaining these properties even at temperatures as high as 1400°C, making them suitable for high-stress applications such as turbines and bearings.
By Product Form :
The market includes powder, coatings, and composites as primary product forms. Powders are widely used in additive manufacturing and advanced fabrication processes, supporting complex component designs. Coatings hold strong demand for thermal protection in aerospace and defense systems. Composites are emerging as a preferred form due to improved toughness and mechanical stability under extreme heat. It strengthens market adoption across industries that require reliable performance in severe environments.
- For instance, AP&C’s plasma-atomized Ti-6Al-4V powder, specified at a 15–45 µm particle size distribution, exhibits just 0.05% of analyzed particles containing pores when assessed over more than 2,000 particles, ensuring exceptional feedstock purity and flowability.
By Application:
Applications cover aerospace, defense, energy, and industrial sectors. Aerospace leads with high demand for propulsion systems, thermal shields, and hypersonic vehicle components. Defense follows closely, supported by investments in missile systems and protective structures. Energy industries adopt these ceramics for nuclear reactors, gas turbines, and hydrogen systems. It ensures long-term growth as industries pursue advanced materials for extreme temperature applications.
Segmentations:
By Material Type:
- Carbides
- Nitrides
- Oxides
By Product Form:
- Powder
- Coatings
- Composites
By Application :
- Aerospace
- Defense
- Energy
- Industrial
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America:
North America holds 38% market share in the ultra high temperature ceramics market in 2024. The region benefits from advanced aerospace and defense industries supported by high government spending. Strong presence of NASA, the Department of Defense, and private space companies fuels adoption of thermal protection and propulsion systems. It drives continuous demand for high-performance ceramics in hypersonic and re-entry applications. Investment in research collaborations between universities and commercial players further strengthens innovation. Expanding applications in energy and nuclear industries also add to regional dominance.
Europe:
Europe accounts for 28% market share in the ultra high temperature ceramics market in 2024. The region supports adoption through established aerospace programs, including the European Space Agency’s initiatives. Strong focus on sustainability and energy efficiency accelerates use in advanced turbines and industrial sectors. It benefits from robust research networks across Germany, France, and the United Kingdom. Funding for innovation projects helps improve toughness and scalability of ceramic composites. The growing role of defense modernization and partnerships across EU member states reinforces steady demand.
Asia-Pacific:
Asia-Pacific holds 24% market share in the ultra high temperature ceramics market in 2024. Rapid industrialization, rising defense budgets, and expanding space programs drive growth across China, India, and Japan. Government-backed investments in hypersonic vehicle development strengthen demand for durable and high-temperature materials. It also benefits from growing energy infrastructure and nuclear power initiatives. Local manufacturers are scaling production capacities to meet rising regional requirements. Increasing collaboration with global players helps improve technology transfer and material innovation. These factors make Asia-Pacific the fastest-growing region in this industry.
Key Player Analysis:
- Kyocera Corporation
- Saint-Gobain Ceramics
- CeramTec GmbH
- CoorsTek, Inc.
- 3M Company
- The Dow Chemical Company
- Morgan Advanced Materials
- Rauschert GmbH
- Elan Technology, Inc.
- Ibiden Co., Ltd.
Competitive Analysis:
The ultra high temperature ceramics market is characterized by strong competition among established global players. Key companies include Kyocera Corporation, Saint-Gobain Ceramics, CeramTec GmbH, CoorsTek, Inc., 3M Company, The Dow Chemical Company, and Morgan Advanced Materials. These firms focus on advanced product development, strategic partnerships, and expansion of production capabilities to strengthen their positions. It emphasizes research on improving thermal resistance, mechanical toughness, and cost efficiency to meet diverse industrial demands. Players also target aerospace, defense, and energy sectors where material performance under extreme conditions is critical. Continuous investment in additive manufacturing and innovative composite materials supports competitive differentiation. Regional expansion and collaboration with government agencies and research institutions further enhance growth opportunities for leading companies.
Recent Developments:
- In July 2025, Kyocera Document Solutions America announced a strategic partnership with Xerox to allow Xerox to distribute Kyocera’s TASKalfa Pro 15000c cut-sheet inkjet printer under Xerox branding, expanding the reach of Kyocera’s inkjet technology.
- In July 2025, Saint-Gobain completed the acquisition of Interstar Materials Inc., broadening its construction chemicals portfolio and entering the granular pigments sector for concrete, with operations retained under the Interstar brand in North America.
Report Coverage:
The research report offers an in-depth analysis based on Material Type, Product Form and Application. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The ultra high temperature ceramics market will expand with rising adoption in hypersonic vehicles and defense programs.
- It will gain momentum from increasing investments in reusable launch systems and space exploration projects.
- Energy industries will drive demand through applications in nuclear reactors, gas turbines, and hydrogen production.
- Advancements in additive manufacturing will improve cost efficiency and expand the scope of complex ceramic components.
- Collaborations between governments, research institutions, and private companies will accelerate material innovations.
- It will benefit from rising defense modernization budgets in major economies across North America, Europe, and Asia.
- Emerging applications in renewable energy systems and industrial processes will broaden market opportunities.
- Manufacturers will focus on enhancing mechanical strength and reducing brittleness to increase reliability.
- Sustainability initiatives will encourage eco-friendly manufacturing methods and higher efficiency in energy-intensive sectors.
- The market will evolve toward wider commercialization with stronger penetration into aerospace, defense, and energy industries.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Ultra High Temperature Ceramics Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Ultra High Temperature Ceramics Market projected to grow between 2024 and 2032?
Which Ultra High Temperature Ceramics Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Ultra High Temperature Ceramics Market?
Who are the leading companies in the Ultra High Temperature Ceramics Market?
Which region commanded the largest share of the Ultra High Temperature Ceramics Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Ultra High Temperature Ceramics Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Ultra High Temperature Ceramics Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1.5 billion → 2032: USD 2.5 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Ultra High Temperature Ceramics Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Ultra High Temperature Ceramics Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Ultra High Temperature Ceramics Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Ultra High Temperature Ceramics Market Drivers
- 3.3 Ultra High Temperature Ceramics Market Restraints & Challenges
- 3.4 Ultra High Temperature Ceramics Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Ultra High Temperature Ceramics Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Ultra High Temperature Ceramics Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Ultra High Temperature Ceramics category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Ultra High Temperature Ceramics Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Ultra High Temperature Ceramics Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Ultra High Temperature Ceramics market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Ultra High Temperature Ceramics Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Ultra High Temperature Ceramics Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Ultra High Temperature Ceramics Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Ultra High Temperature Ceramics (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Ultra High Temperature Ceramics Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Ultra High Temperature Ceramics Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Ultra High Temperature Ceramics Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Ultra High Temperature Ceramics Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Ultra High Temperature Ceramics Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Ultra High Temperature Ceramics Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Ultra High Temperature Ceramics Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Ultra High Temperature Ceramics Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Ultra High Temperature Ceramics Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
