
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
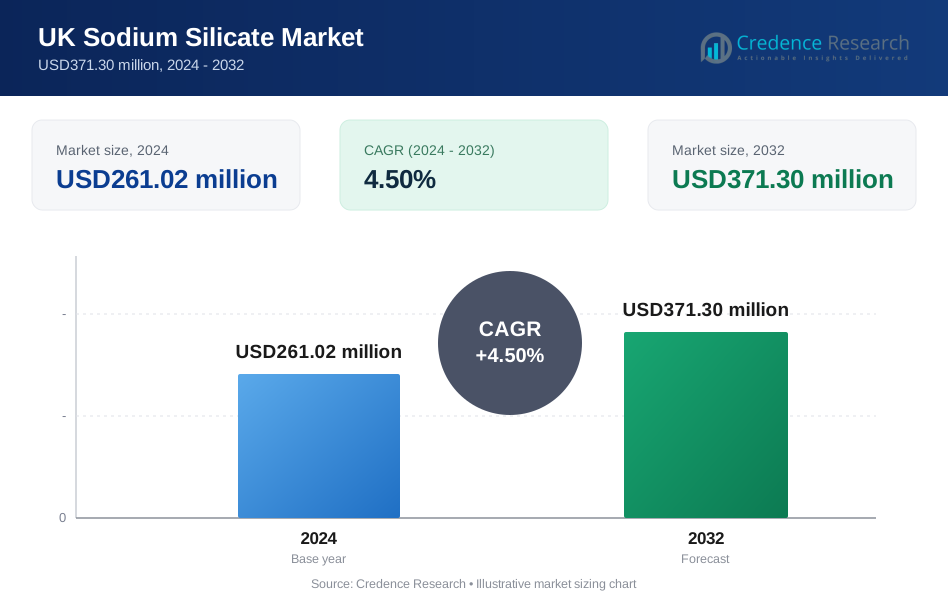
| UK Sodium Silicate Market Size 2024 | USD261.02 million |
| UK Sodium Silicate Market, CAGR | 4.50% |
| UK Sodium Silicate Market Size 2032 | USD371.30 million |
Market Overview
The UK Sodium Silicate Market is projected to grow from USD261.02 million in 2024 to an estimated USD371.30 million by 2032, with a compound annual growth rate (CAGR) of 4.50% from 2025 to 2032. The market is witnessing a steady rise due to increasing industrial demand, particularly in the detergents, ceramics, and construction sectors.
Key drivers of the market include the growing demand for sodium silicate in water treatment and detergent formulations, where its use in industrial cleaning processes continues to rise. Additionally, the expanding construction and ceramics industries in the UK benefit from sodium silicate’s role in cement production and as a bonding agent in ceramics. The market also trends towards more eco-friendly products, boosting demand for sodium silicate as an environmentally safer alternative to other chemicals.
Geographically, the UK holds a significant share in the European Sodium Silicate Market, driven by a robust manufacturing base and demand from various industrial sectors. The market is dominated by players such as Evonik Industries AG, PQ Corporation, and W.R. Grace & Co., which play a vital role in the supply chain and development of sodium silicate applications. With the growing trend of industrial modernization, these companies are key contributors to the market's expansion in the UK.
Market Insights
- The UK Sodium Silicate Market is projected to grow from USD261.02 million in 2024 to USD371.30 million by 2032, with a CAGR of 4.50% from 2025 to 2032.
- The global sodium silicate market is projected to grow from USD 10,277.26 million in 2024 to USD 15,183.45 million by 2032, with a CAGR of 5.00% from 2025 to 2032. It is driven by diverse applications across industries such as detergents, construction, and water treatment.
- Key drivers include the rising demand for sodium silicate in detergents, water treatment, and construction, with industries seeking sustainable, eco-friendly solutions.
- Volatility in raw material prices and supply chain disruptions could impact market growth, raising production costs and limiting availability.
- England holds the largest market share, driven by industrial activities in construction, chemicals, and detergents, while demand in Scotland and Wales is growing due to food processing and ceramics.
- Innovations in sodium silicate production processes and applications, including energy-efficient and eco-friendly products, contribute to market expansion.
- The trend toward sustainability in construction materials and cleaning products is driving increased adoption of sodium silicate as a green alternative to traditional chemicals.
- Major players like Evonik Industries AG, PQ Corporation, and W\.R. Grace & Co. dominate the UK market, focusing on product innovation and meeting the growing demand for eco-conscious solutions.
Report Scope
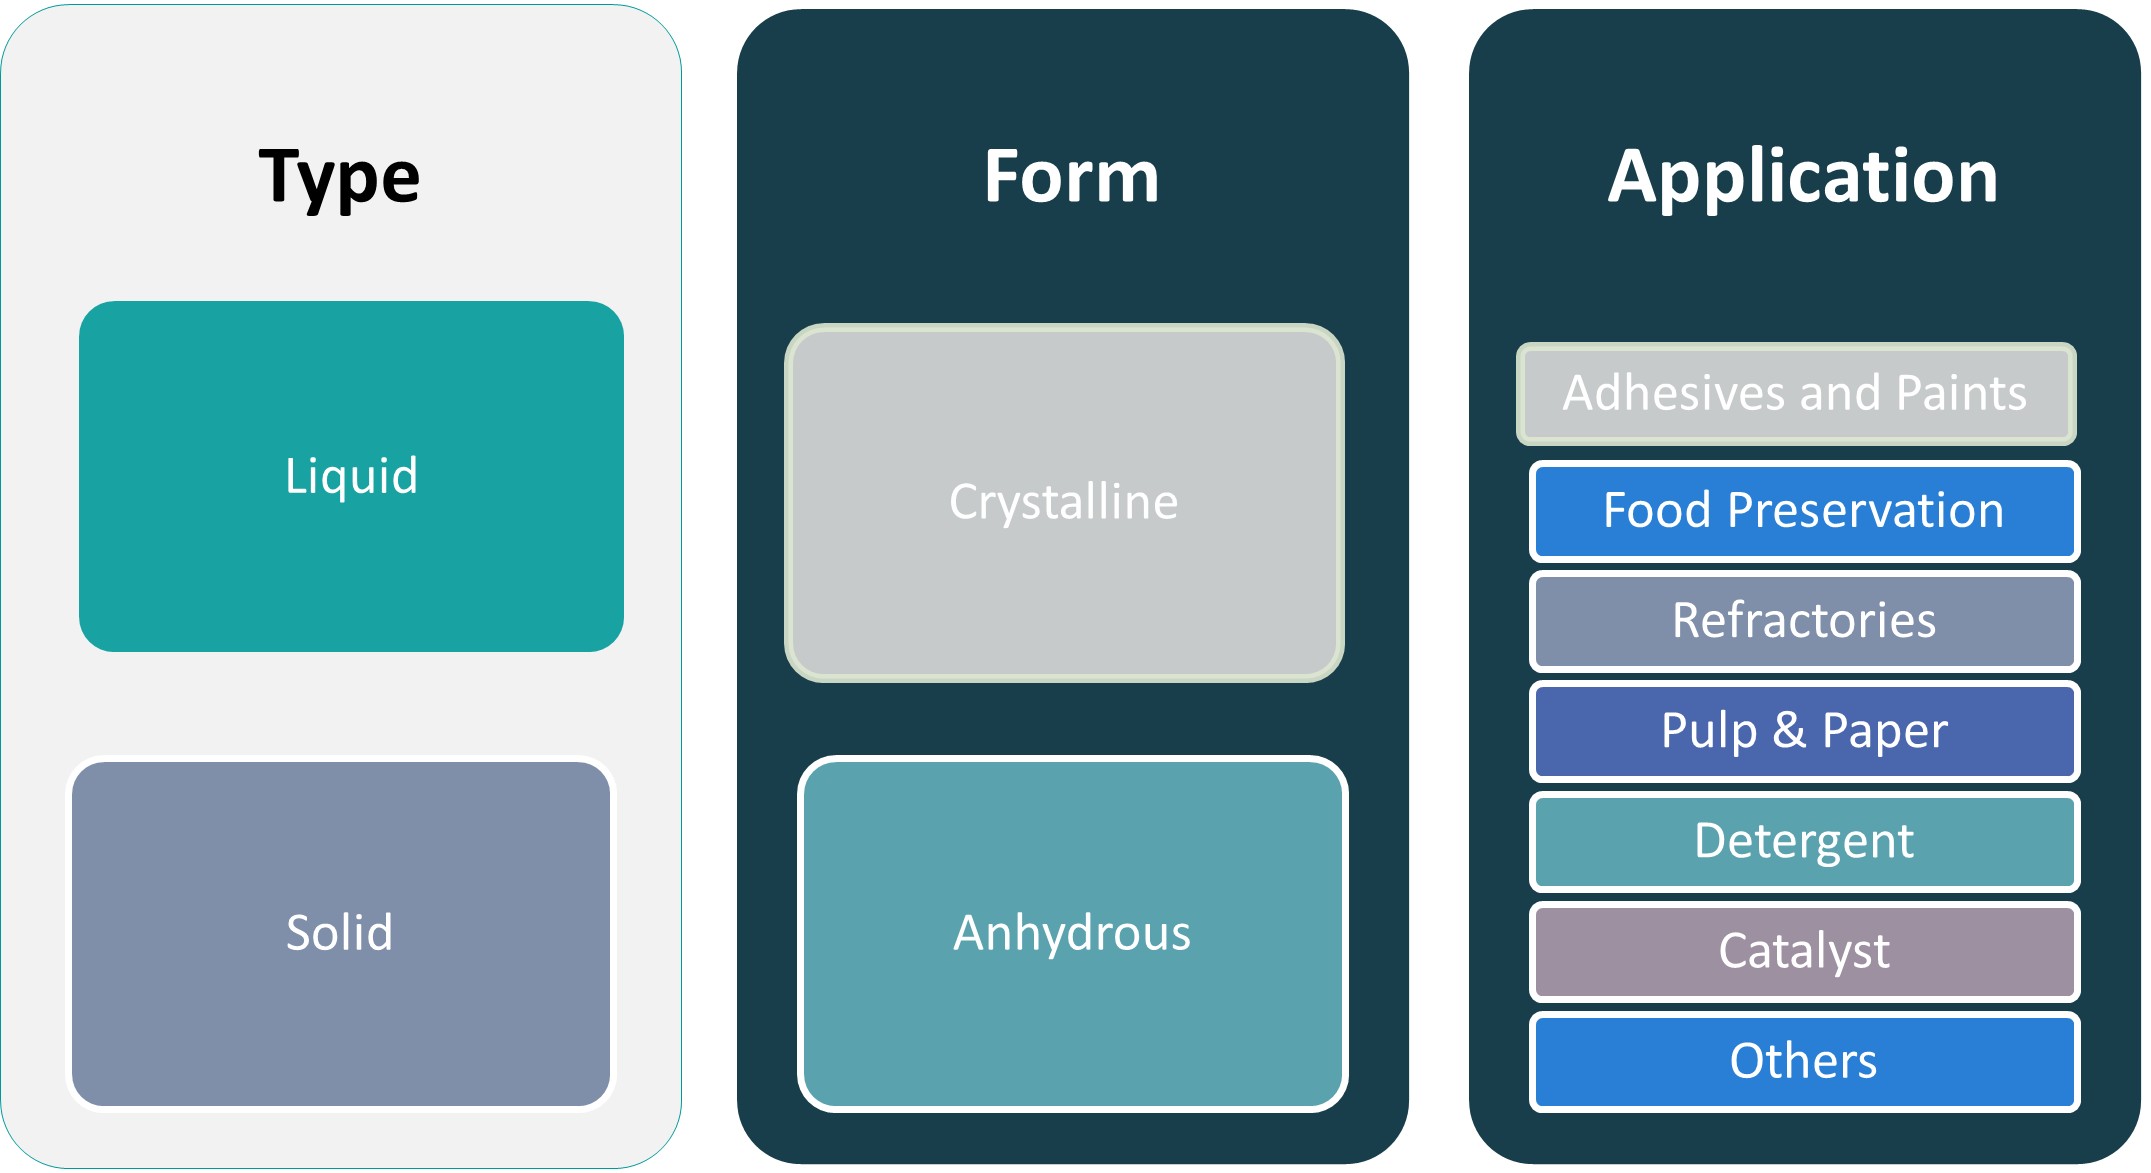
This report segments the UK Sodium Silicate Market as follows:
Market Drivers
Increasing Demand in Detergent and Cleaning Products
The demand for sodium silicate is growing rapidly due to its widespread use in detergent formulations. Sodium silicate is a key ingredient in the production of both household and industrial cleaning products, where it acts as a builder, enhancing the effectiveness of surfactants and preventing the formation of soap scum. For instance, Silmaco offers a complete range of sodium silicate products dedicated to the detergent industry, including metasilicate anhydrous and pentahydrate, which are widely used in industrial and institutional cleaning agents. Additionally, Newport Industries supplies sodium silicate for detergent formulations, supporting manufacturers in producing high-performance cleaning products. It also helps in softening water, which improves the performance of detergents. As the demand for cleaning products continues to rise across sectors such as residential, commercial, and industrial cleaning, sodium silicate remains essential for manufacturers aiming to meet growing consumer expectations for efficient, eco-friendly cleaning solutions. Additionally, the increasing demand for green cleaning products is fostering market growth, as sodium silicate is a non-toxic, biodegradable compound that fits well with the trend towards sustainable chemicals.
Rising Demand from the Construction Industry
The UK construction sector is one of the largest consumers of sodium silicate. The compound is used extensively in the production of cement, where it acts as a binder and improves the durability and strength of the material. For instance, sodium silicate is extensively used in cement and concrete applications, supporting infrastructure projects across the UK. Additionally, sodium silicate plays a crucial role in high-performance concrete formulations, improving durability and resistance in construction materials. Sodium silicate is also employed in the formulation of concrete sealers and water repellents, where it helps to improve resistance to moisture and enhance the lifespan of buildings. The ongoing boom in the UK construction industry, driven by government infrastructure projects and urbanization trends, supports the increased demand for sodium silicate-based products. Furthermore, sodium silicate is a crucial component in the production of fireproofing materials, which is a growing segment as construction standards become stricter in terms of safety regulations. With the ongoing trend toward urban renewal and large-scale commercial construction, sodium silicate will continue to play a key role in shaping the future of the UK construction sector.
Growth of the Ceramics and Glass Manufacturing Sector
The ceramics and glass industries are key sectors contributing to the growth of the sodium silicate market in the UK. Sodium silicate, also known as water glass, is used in the manufacture of ceramics to improve the bonding and strengthening of the material. It is especially valuable in the production of porcelain and other fine ceramics, where it enhances the properties of the clay body, making it more durable and heat-resistant. Similarly, in the glass industry, sodium silicate is utilized as an adhesive and a fluxing agent to facilitate the melting of silica and to improve the clarity and strength of glass products. As these industries continue to expand in the UK, driven by both domestic consumption and export demand, the consumption of sodium silicate is expected to rise. The increasing use of sodium silicate in energy-efficient and sustainable products, such as low-energy glass for buildings, is further contributing to the market's positive outlook.
Water Treatment Applications and Environmental Regulations
The demand for sodium silicate in water treatment processes is another significant driver in the UK market. Sodium silicate is commonly used in water treatment plants to remove heavy metals and other impurities, as it helps to neutralize water and precipitate harmful substances, making the water safe for consumption and use. As water quality regulations become more stringent, water treatment operators are increasingly relying on sodium silicate to meet these requirements. Furthermore, environmental sustainability is becoming an essential focus in various sectors, and sodium silicate is perceived as an environmentally friendly option for water purification. The growing awareness of environmental issues, along with the need to preserve water resources, is expected to fuel the demand for sodium silicate in water treatment applications in the UK.
Market Trends
Shift Towards Eco-Friendly and Sustainable Products
The UK Sodium Silicate Market is witnessing a growing trend toward eco-friendly and sustainable products, driven by increased consumer awareness and stricter environmental regulations. As industries such as detergents, construction, and ceramics seek more sustainable solutions, sodium silicate is becoming a preferred ingredient due to its non-toxic, biodegradable nature. For instance, PQ Corporation, a leading global producer of sodium silicate, reported a revenue of $1.5 billion in 2022 and has integrated sodium silicate into its sustainable product portfolio. Occidental Petroleum Corporation (OxyChem), with a revenue of $7 billion in 2022, has developed sodium silicate-based adhesives and coatings that minimize environmental impact. BASF, headquartered in Germany, recorded $78 billion in revenue in 2022 and has focused on sustainable solutions, utilizing sodium silicate in water treatment applications. Manufacturers are increasingly formulating products that emphasize the environmental benefits of using sodium silicate, such as its role in reducing the environmental impact of cleaning products and construction materials. Additionally, the growing demand for green building materials, such as low-emission cement and energy-efficient glass, is further propelling the market for sodium silicate. With the UK government setting ambitious environmental targets and emphasizing sustainable manufacturing, this trend is expected to continue driving the demand for eco-friendly sodium silicate-based products in various industries.
Technological Advancements in Production and Application
Innovations in sodium silicate production and its applications are influencing the market's growth trajectory in the UK. Manufacturers are focusing on enhancing the efficiency of sodium silicate production processes, including the development of more cost-effective and energy-efficient methods. For instance, Evonik Industries, a German specialty chemicals company, has invested in advanced manufacturing techniques to enhance sodium silicate purity and efficiency. Merck Group, another German-based company, has implemented smart production technologies to optimize resource usage and reduce environmental impact. Tokuyama Corporation, a Japanese firm with operations in the UK, has developed innovative sodium silicate formulations for high-tech applications. Technological advancements in application techniques, such as the use of sodium silicate in advanced water treatment systems, are also contributing to market expansion. In construction, new formulations incorporating sodium silicate are being used to create more durable and weather-resistant materials, such as concrete sealants and fire-resistant coatings. Additionally, research into new applications, such as its use in energy storage and as a catalyst in chemical processes, is opening new growth opportunities for sodium silicate in the UK market.
Increase in Industrial Automation and Mechanization
The increasing industrial automation and mechanization in various sectors are fueling the demand for sodium silicate in the UK. As industries such as agriculture, construction, and manufacturing embrace automation for greater efficiency, the need for sodium silicate in equipment and machinery applications is rising. In the agriculture sector, for instance, sodium silicate is being used in advanced irrigation and water treatment systems, benefiting from automated processes that enhance water purification. In the construction industry, mechanized equipment for mixing and applying sodium silicate-based materials is becoming more common, boosting productivity and reducing labor costs. This trend toward automation is expected to continue to drive the demand for sodium silicate in both traditional and emerging industrial applications, particularly as the UK seeks to improve its manufacturing and processing capabilities in response to competitive market pressures.
Growing Demand from the Renewable Energy Sector
The renewable energy sector is increasingly influencing the UK Sodium Silicate Market, particularly with the use of sodium silicate in energy-efficient products such as solar panels, wind turbines, and energy storage systems. Sodium silicate’s role as a binder and protective coating material is vital in the production of components for renewable energy technologies. For example, sodium silicate is used in the manufacturing of photovoltaic glass for solar panels, enhancing their durability and efficiency. With the UK government pushing for a transition to a low-carbon economy and setting ambitious renewable energy targets, the demand for sodium silicate in renewable energy applications is expected to increase. This trend is helping diversify the market and establish sodium silicate as a critical material in the energy transition process, further driving its growth in the UK.
Market Challenges
Fluctuating Raw Material Prices and Supply Chain Disruptions
One of the key challenges facing the UK Sodium Silicate Market is the volatility in raw material prices and disruptions in the supply chain. Sodium silicate is primarily produced from silica sand and soda ash, both of which are subject to price fluctuations due to factors such as global supply-demand imbalances, geopolitical tensions, and natural disasters that affect mining operations. For instance, disruptions in silica supply in 2024 led to increased production costs for sodium silicate manufacturers in the UK. Soda ash, which is produced through energy-intensive processes, also saw price variations due to rising energy costs and logistical challenges. This price volatility can increase production costs, putting pressure on manufacturers to adjust their pricing strategies or absorb the additional costs. Additionally, the COVID-19 pandemic and subsequent global supply chain disruptions have highlighted the vulnerabilities in the supply chain for key raw materials. Delays in transportation and shortages of materials have impacted the ability of manufacturers to maintain consistent production schedules, leading to potential shortages or delays in product availability for end-users in sectors such as construction, ceramics, and detergents. Some manufacturers have begun investing in alternative sourcing options and improving supply chain resilience to mitigate these risks. Additionally, companies are exploring more efficient production processes to reduce dependency on fluctuating raw material costs. Failure to manage raw material costs effectively could impact the profitability and long-term growth of sodium silicate producers in the region.
Regulatory Pressures and Environmental Concerns
Another significant challenge for the UK Sodium Silicate Market is the increasing regulatory pressures and growing environmental concerns related to chemical production and use. As governments around the world, including the UK, tighten environmental regulations, there is a growing emphasis on reducing the environmental impact of manufacturing processes and ensuring the safe use of chemicals. Sodium silicate, although considered eco-friendly compared to many alternatives, is still subject to regulatory scrutiny, particularly in industries such as water treatment and detergents. Stricter rules on chemical emissions, waste disposal, and material recycling may force companies to adopt costly measures to comply with these new standards. Moreover, the increasing demand for more sustainable products puts pressure on sodium silicate producers to innovate and offer products with reduced environmental impact. This may require significant investment in research and development to formulate new, environmentally friendly variants of sodium silicate and adopt greener production technologies. For manufacturers, keeping up with evolving regulatory requirements while maintaining product cost-effectiveness is a continual challenge. Ensuring compliance with environmental standards without sacrificing market competitiveness is a balancing act that requires ongoing adaptation to both regulatory changes and consumer preferences for sustainable products
Market Opportunities
Expanding Applications in Renewable Energy and Green Construction
A significant market opportunity in the UK Sodium Silicate Market lies in its expanding applications within the renewable energy and green construction sectors. Sodium silicate is increasingly being used in the production of energy-efficient materials, including photovoltaic glass for solar panels and in the development of durable, eco-friendly construction materials. As the UK accelerates its transition to renewable energy and sustainable construction practices, there is a rising demand for products that enhance energy efficiency and environmental performance. Sodium silicate's role as a binder, sealant, and protective coating in solar panels and energy storage systems aligns with the government's focus on reducing carbon emissions and promoting green technologies. Additionally, as the construction industry moves toward more sustainable building practices, sodium silicate-based products are increasingly being integrated into low-carbon materials, such as energy-efficient glass, high-performance cement, and fire-resistant coatings. This trend presents substantial growth potential for sodium silicate manufacturers that can capitalize on the increasing demand for renewable energy infrastructure and sustainable construction solutions.
Rising Demand for Eco-Friendly Detergents and Cleaning Products
Another key opportunity for the UK Sodium Silicate Market is the rising demand for eco-friendly detergents and cleaning products. As consumers become more environmentally conscious, there is a growing preference for non-toxic, biodegradable cleaning solutions. Sodium silicate, known for its eco-friendly properties, is increasingly being incorporated into the formulations of household and industrial detergents. Its ability to enhance the performance of cleaning products while maintaining a low environmental footprint makes it an attractive option for manufacturers looking to meet consumer demand for sustainable alternatives. Furthermore, the tightening of environmental regulations around chemical emissions and waste disposal further drives the shift toward sustainable cleaning products. Companies that innovate and offer eco-friendly, high-performance detergents using sodium silicate stand to capture a growing share of this environmentally driven market.
Market Segmentation Analysis
By Type
The UK Sodium Silicate Market is segmented based on type into liquid and solid forms. The liquid segment dominates the market, driven by its wide application in industrial processes such as detergents, water treatment, and cement manufacturing. Liquid sodium silicate is preferred for its ease of use and ability to dissolve rapidly, making it a key ingredient in various formulations, especially in cleaning agents and adhesives. On the other hand, the solid form of sodium silicate is primarily used in industries that require bulk quantities of the substance in a stable, easy-to-store form. Solid sodium silicate is commonly utilized in the production of ceramics, glass, and as a fluxing agent in steel manufacturing. While the liquid form maintains a larger market share due to its versatility and ease of application, the solid form is anticipated to witness steady growth, particularly in the construction and industrial sectors.
By Form
Sodium silicate is also categorized based on form into crystalline and anhydrous types. The crystalline form is widely used in applications such as detergents, where it acts as a water softener, enhancing the performance of cleaning agents. It is also used in the production of certain types of glass and ceramics. The anhydrous form of sodium silicate, which is essentially anhydrous sodium metasilicate, is preferred in industrial applications that require higher purity and more controlled chemical reactivity, such as in catalysts and in the manufacturing of refractories. The demand for both crystalline and anhydrous forms is expected to grow as industries increasingly look for specific chemical properties that align with advanced manufacturing processes.
Segments
Based on Type
- Liquid
- Solid
Based on Form
- Crystalline
- Anhydrous
Based on Application
- Adhesives and Paints
- Food Preservation
- Refractories
- Pulp & Paper
- Detergent
- Catalyst
- Others
Based on Region
- Scotland
- Wales
- Northern Ireland
Regional Analysis
England (75%)
England holds the largest market share in the UK Sodium Silicate Market, accounting for approximately 75% of the total market. The high concentration of industries such as construction, automotive manufacturing, water treatment, and chemicals contributes significantly to the demand for sodium silicate. The south of England, particularly London and the surrounding areas, is a hub for construction and infrastructure development, further driving the use of sodium silicate in the form of concrete sealants, cement production, and water treatment applications. Additionally, the presence of key players in industrial chemicals, detergents, and adhesives further strengthens England's dominant position in the market. The demand for sodium silicate in industrial cleaning products, which is particularly prevalent in urban areas, also plays a crucial role in boosting its consumption.
Scotland (10%)
Scotland represents around 10% of the UK Sodium Silicate Market share. The demand in this region is largely driven by the food processing, glass manufacturing, and chemical industries. Sodium silicate is used extensively in food preservation and as a binder in glass production. Additionally, the oil and gas industry in Scotland, though declining in some aspects, still requires sodium silicate for certain industrial applications such as water treatment and chemical processing. Moreover, as Scotland continues to focus on sustainable and green energy, the demand for sodium silicate in renewable energy applications such as solar panels is expected to grow, providing further opportunities for market expansion in the region.
Key players
- ICL UK
- Monarch Chemicals
- Plater Group
- Inoxia Ltd
- Source Chemicals Ltd
Competitive Analysis
The UK Sodium Silicate Market is characterized by the presence of both established players and specialized companies, each contributing to the market’s dynamic growth. ICL UK, a prominent player, offers a wide range of sodium silicate products and benefits from a strong market presence. Their diversified product portfolio and extensive industry experience make them a significant competitor. Monarch Chemicals and Plater Group are also notable players, offering specialized solutions for various industrial applications such as detergents, ceramics, and adhesives. These companies are highly competitive in the sector due to their commitment to innovation and efficient manufacturing processes. Inoxia Ltd and Source Chemicals Ltd are more niche players, with a focus on sustainable and eco-friendly chemical solutions. Their smaller, yet focused product offerings position them as key contributors to the growing demand for environmentally-conscious alternatives in sodium silicate-based applications.
Recent Developments
- In May 2025, Evonik announced a global net price increase of up to 5–8% for its MetAMINO (DL-methionine 99% feed grade) product, effective immediately. All existing contracts and supply agreements will be honored.
- In November 2024, Kraton announced a global price increase of \$330 per metric ton for all SIS polymer products, effective January 1, 2025. This decision was driven by rising raw material and process chemical costs.
- In September 2024, CIECH Vitrosilicon initiated the construction of a new warehouse at its Żary plant to enhance sodium silicate production capabilities and logistics efficiency.
- In May 2024, Orablue Chem Pvt. Ltd. participated in ChemExpo 2024 in Mumbai, showcasing its range of sodium metabisulphite and sodium metasilicate products.
- In April 2024, Wacker Chemie AG reported a 22% decline in sales for 2023, attributed to lower prices and volumes, reflecting challenges in the global chemical market.
- In March 2024, Sasol announced plans to expand its sodium silicate production capacity to meet increasing demand in the detergent and water treatment sectors.
Market Concentration and Characteristics
The UK Sodium Silicate Market exhibits moderate market concentration, with a mix of established multinational corporations and smaller, specialized players. Major companies like ICL UK and Monarch Chemicals dominate the market due to their extensive product portfolios, global reach, and strong industry presence. These companies cater to a wide range of sectors, including construction, detergents, and ceramics. However, the market also features a number of smaller firms, such as Inoxia Ltd and Source Chemicals Ltd, which focus on niche applications and eco-friendly solutions. The market is characterized by a growing demand for sustainable and innovative products, which has led to increased competition among both large and small players. Additionally, technological advancements in production processes and a focus on reducing environmental impacts are shaping the market's dynamics, leading to an evolving competitive landscape.
Report Coverage
The research report offers an in-depth analysis based on Type, Form, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The increasing demand for eco-friendly construction materials will drive the growth of sodium silicate in the UK. Sodium silicate's role in producing low-carbon cement and energy-efficient glass will be pivotal in the expansion of sustainable construction projects.
- Sodium silicate's use in the renewable energy sector, particularly in solar panels, is expected to rise. The UK’s push for clean energy will open new opportunities for sodium silicate as a key component in energy-efficient technologies.
- With stricter environmental regulations and a focus on water conservation, sodium silicate will see increased use in water treatment applications. Its ability to remove impurities and enhance water quality positions it well for long-term market growth.
- The shift toward environmentally friendly detergents will spur demand for sodium silicate. As consumers opt for safer, biodegradable cleaning agents, sodium silicate's eco-friendly properties will become a key selling point for manufacturers.
- Sodium silicate will continue to play a significant role in ceramics and glass manufacturing. As demand for specialty ceramics and advanced glass products grows, sodium silicate will be increasingly integrated into production processes.
- Ongoing advancements in sodium silicate production processes will enhance efficiency and reduce costs. The adoption of more sustainable and cost-effective manufacturing technologies will drive market growth.
- Government policies supporting sustainable practices and stricter regulations will promote the use of eco-friendly sodium silicate. As industries comply with environmental standards, sodium silicate will become an essential part of green manufacturing solutions
- The increasing automation of industrial processes in sectors like construction and agriculture will boost the demand for sodium silicate. Its role in improving efficiency in automated systems will contribute to its growing use.
- Sodium silicate is expected to expand into new industries, such as energy storage and advanced catalysts. The chemical's versatility will unlock new applications in industries that require high-performance, sustainable materials.
- As the market grows, competition among key players will intensify, with innovation being the main differentiator. Companies investing in research and development will secure a larger market share by offering specialized, high-quality sodium silicate products.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size of the UK Sodium Silicate Market in 2024 and 2032?
What is the compound annual growth rate (CAGR) of the UK Sodium Silicate Market?
Who are the major players in the UK Sodium Silicate Market?
How does sodium silicate contribute to the construction and ceramics industries?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 UK Sodium Silicate Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global UK Sodium Silicate Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD261.02 million → 2032: USD371.30 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 UK Sodium Silicate Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. UK Sodium Silicate Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 UK Sodium Silicate Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 UK Sodium Silicate Market Drivers
- 3.3 UK Sodium Silicate Market Restraints & Challenges
- 3.4 UK Sodium Silicate Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 UK Sodium Silicate Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 UK Sodium Silicate Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, UK Sodium Silicate category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 UK Sodium Silicate Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. UK Sodium Silicate Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the UK Sodium Silicate market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 UK Sodium Silicate Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 UK Sodium Silicate Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 UK Sodium Silicate Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in UK Sodium Silicate (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New UK Sodium Silicate Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global UK Sodium Silicate Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America UK Sodium Silicate Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe UK Sodium Silicate Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific UK Sodium Silicate Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America UK Sodium Silicate Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East UK Sodium Silicate Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa UK Sodium Silicate Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. UK Sodium Silicate Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
