
Market Overview
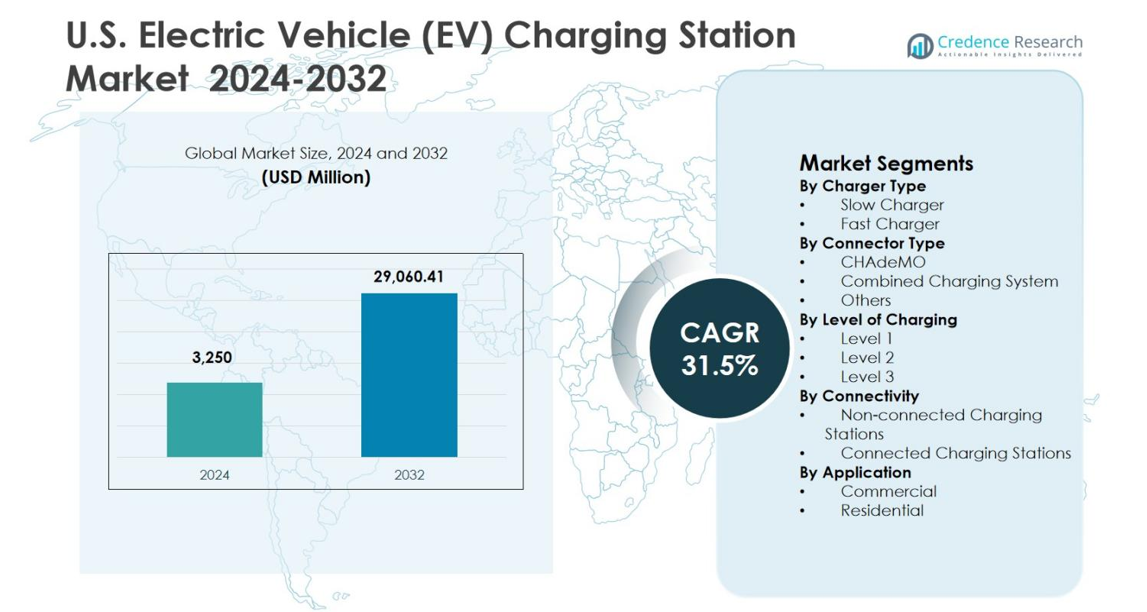
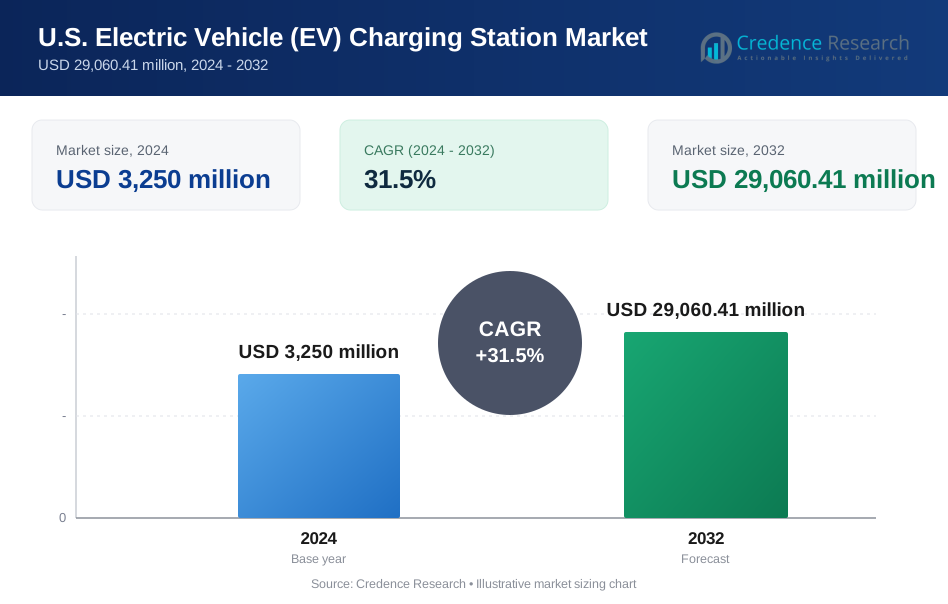
The U.S. Electric Vehicle (EV) Charging Station Market size was valued at USD 3,250 million in 2024 and is anticipated to reach USD 29,060.41 million by 2032, expanding at a CAGR of 31.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| U.S. Electric Vehicle (EV) Charging Station Market Size 2024 | USD 3,250 million |
| U.S. Electric Vehicle (EV) Charging Station Market , CAGR | 31.5% |
| U.S. Electric Vehicle (EV) Charging Station Market Size 2032 | USD 29,060.41 million |
The U.S. Electric Vehicle (EV) Charging Station Market is shaped by the strong presence of leading players such as ChargePoint, Inc., Tesla, Inc., ABB Ltd., bp pulse, General Electric Company, Delta Electronics, Inc., EVgo, Blink Charging, SemaConnect, and Webasto Group, which actively focus on network expansion, fast-charging deployment, and software-enabled charging solutions. These companies invest in public, commercial, and fleet-focused infrastructure to enhance accessibility and charging reliability nationwide. Regionally, the West region dominated the U.S. Electric Vehicle (EV) Charging Station Market with a 38.7% market share in 2024, driven by high EV adoption, supportive clean-energy policies, and dense charging networks across states such as California, Washington, and Oregon, positioning it as the primary growth engine of the market.
Market Insights
- Valued at USD 3,250 million in 2024, the U.S. Electric Vehicle (EV) Charging Station Market is projected to reach USD 29,060.41 million by 2032, expanding at a CAGR of 31.5% during the forecast period.
- Market expansion is driven by accelerating electric vehicle adoption, strong federal and state incentives, and increasing investments in public, residential, and workplace charging infrastructure.
- Deployment trends highlight Fast Chargers as the dominant segment with 2% share, while the Combined Charging System leads connector types with 58.6% share, and Level 2 charging accounts for 46.9% share in 2024.
- Industry dynamics are shaped by network expansion and technology upgrades from ChargePoint, Tesla, ABB, bp pulse, GE, Delta Electronics, EVgo, Blink Charging, SemaConnect, and Webasto Group.
- Regionally, the West led with 7% share in 2024, followed by the South at 22.7%, the Northeast at 21.4%, and the Midwest at 17.2%, reflecting uneven infrastructure maturity across the U.S.
Market Segmentation Analysis:
By Charger Type:
The U.S. Electric Vehicle (EV) Charging Station Market, by charger type, is led by the Fast Charger segment, which accounted for 64.2% market share in 2024, driven by rising demand for reduced charging time and the expansion of highway and urban fast-charging corridors. Fast chargers are increasingly deployed across commercial locations, fleet depots, and public charging networks to support long-distance travel and high vehicle utilization. The growing adoption of DC fast charging by OEMs, increasing federal infrastructure funding, and strong preference for convenience among consumers continue to reinforce the dominance of the fast charger segment.
- For instance, Amazon has equipped several large U.S. delivery stations with 70 or more charging points to support over 100 Rivian electric vans, combining Level 2 units with strategically placed DC fast chargers so vans can recover up to 80% charge in about 30 minutes between multi‑shift delivery cycles.
By Connector Type:
By connector type, the Combined Charging System (CCS) segment dominated the U.S. Electric Vehicle (EV) Charging Station Market with a 58.6% market share in 2024, supported by its wide compatibility with major North American and European EV manufacturers. CCS enables both AC and DC charging through a single connector, making it a preferred standard for public and commercial charging installations. The dominance of CCS is further driven by regulatory alignment, automaker standardization strategies, and large-scale deployment by charging network operators, ensuring interoperability, scalability, and long-term infrastructure reliability across the U.S. market.
- For instance, ChargePoint deploys CCS-compatible Express Plus stations up to 500 kW through 125 NEVI-funded sites, including recent Interstate 95 openings in Rhode Island.
By Level of Charging:
Based on the level of charging, Level 2 charging stations held the dominant position in the U.S. Electric Vehicle (EV) Charging Station Market, capturing 46.9% market share in 2024. This dominance is attributed to widespread installation across residential complexes, workplaces, retail centers, and public parking facilities. Level 2 chargers offer a balanced combination of moderate charging speed, cost efficiency, and ease of installation compared to Level 3 systems. Government incentives, utility programs, and increasing adoption in multi-unit dwellings continue to drive sustained growth of the Level 2 segment.
Key Growth Drivers
Rapid Growth in Electric Vehicle Adoption
The U.S. Electric Vehicle (EV) Charging Station Market is strongly driven by the accelerating adoption of electric vehicles across passenger, commercial, and fleet segments. Rising consumer awareness of environmental sustainability, declining battery costs, and expanding EV model availability are encouraging higher vehicle penetration. As EV ownership increases, the need for reliable and accessible charging infrastructure intensifies across residential, workplace, and public locations. This sustained rise in EV parc directly fuels large-scale deployment of charging stations to support daily commuting, long-distance travel, and commercial fleet operations.
- For instance, Tesla operates 2,892 Supercharger stations with 34,980 DC fast-charging ports in the U.S., providing high-speed highway and urban coverage that underpins long-distance and intercity EV travel.
Strong Government Support and Infrastructure Funding
Federal and state-level initiatives play a critical role in advancing the U.S. Electric Vehicle (EV) Charging Station Market. Programs such as public infrastructure grants, tax credits, and utility-backed incentives are accelerating charging station installations nationwide. Policy frameworks focused on reducing carbon emissions and promoting clean transportation have strengthened investment confidence among private players. Additionally, funding allocated for highway corridor electrification and underserved communities is driving widespread deployment, ensuring equitable access to charging infrastructure and supporting long-term market expansion.
- For instance, the federal Alternative Fuel Vehicle Refueling Property Credit (30C) now allows businesses and tax‑exempt entities to claim up to 30 percent of eligible EV charging project costs, capped at 100,000 dollars per charging port in qualifying low‑income or non‑urban census tracts, substantially improving the economics of private investment in public or workplace charging.
Expansion of Commercial and Fleet Charging Networks
The rapid electrification of commercial fleets, including logistics, ride-hailing, public transit, and delivery services, is a major growth catalyst for the U.S. Electric Vehicle (EV) Charging Station Market. Fleet operators require high-capacity, reliable, and fast charging solutions to maintain operational efficiency and minimize downtime. This demand is driving investments in depot-based and high-power public charging networks. Partnerships between charging providers, fleet operators, and energy companies further strengthen infrastructure scalability and reinforce sustained market growth.
Key Trends & Opportunities
Deployment of High-Power and Ultra-Fast Charging Technologies
The U.S. Electric Vehicle (EV) Charging Station Market is witnessing a strong shift toward high-power and ultra-fast charging solutions. Charging providers are increasingly installing Level 3 and DC fast chargers to meet consumer expectations for shorter charging times. This trend creates opportunities for technology providers offering advanced power electronics, thermal management, and grid integration solutions. High-power charging hubs along highways and urban centers are enhancing user convenience while unlocking new revenue streams for network operators.
- For instance, EVgo partnered with Pilot Company and General Motors to deploy over 200 sites featuring 350 kW DC fast chargers across nearly 40 states by mid-2025, with more than 850 stalls now operational at Pilot and Flying J travel centers along interstate highways.
Integration of Renewable Energy and Smart Charging Solutions
The integration of renewable energy sources and smart charging technologies presents significant opportunities in the U.S. Electric Vehicle (EV) Charging Station Market. Charging stations are increasingly paired with solar power, battery storage, and energy management systems to reduce grid strain and operating costs. Smart charging software enables load balancing, dynamic pricing, and demand response participation. These advancements improve grid resilience, support sustainability goals, and create value-added services for utilities, businesses, and end users.
- For instance, Envision Solar's EV ARC™ system deploys off-grid solar-powered charging stations across the U.S. and Canada in partnership with ChargePoint. The patented EnvisionTrak™ technology tracks the sun to generate 18-25% more electricity than fixed arrays, powering up to 150 miles of daily EV driving with stored energy for nighttime use.
Key Challenges
High Installation and Grid Upgrade Costs
High upfront installation costs remain a major challenge for the U.S. Electric Vehicle (EV) Charging Station Market. Expenses related to land acquisition, electrical upgrades, permitting, and grid interconnection significantly increase project timelines and capital requirements. Fast and ultra-fast charging stations require substantial power capacity, often necessitating transformer upgrades and utility coordination. These financial and logistical barriers can slow deployment, particularly in rural areas and small commercial locations with limited infrastructure readiness.
Grid Capacity Constraints and Operational Reliability
Grid capacity limitations and operational reliability issues pose challenges to the U.S. Electric Vehicle (EV) Charging Station Market. Rapid expansion of charging networks increases demand on local distribution systems, leading to congestion and voltage instability in certain regions. Inconsistent uptime, maintenance requirements, and interoperability issues also affect user experience. Addressing these challenges requires coordinated planning between utilities, charging operators, and regulators to ensure reliable power supply, standardization, and long-term infrastructure resilience.
Regional Analysis
West
The U.S. Electric Vehicle (EV) Charging Station Market in the West region held 38.7% market share in 2024, supported by strong EV adoption, advanced clean-energy policies, and dense charging infrastructure across states such as California, Washington, and Oregon. High consumer awareness, zero-emission mandates, and extensive public–private investments continue to drive charging station deployment. The region benefits from widespread fast-charging networks, strong utility participation, and early adoption of smart-charging technologies, reinforcing its leadership position and accelerating the transition toward electrified transportation systems.
Northeast
The Northeast accounted for 21.4% market share in 2024 in the U.S. Electric Vehicle (EV) Charging Station Market, driven by urban density, state-level climate initiatives, and growing public transit electrification. States including New York and Massachusetts actively promote EV adoption through incentives and infrastructure funding. The high concentration of multi-unit residential buildings supports demand for Level 2 and public charging solutions. Expanding workplace charging programs and municipal investments continue to strengthen charging accessibility across metropolitan and suburban areas.
Midwest
The Midwest region captured 17.2% market share in 2024 within the U.S. Electric Vehicle (EV) Charging Station Market, supported by increasing EV adoption, automotive manufacturing presence, and expanding interstate charging corridors. States such as Michigan, Illinois, and Ohio are investing in highway fast-charging networks to support long-distance travel and regional connectivity. Utility-led infrastructure programs and growing commercial fleet electrification contribute to steady market growth. The region is also benefiting from rising investments in manufacturing-linked charging infrastructure.
South
The South held 22.7% market share in 2024 in the U.S. Electric Vehicle (EV) Charging Station Market, driven by rising EV adoption, urban expansion, and growing investments in public charging infrastructure. States such as Texas, Florida, and Georgia are witnessing rapid deployment of fast and Level 2 charging stations across retail centers, workplaces, and residential developments. Favorable economic growth, expanding logistics fleets, and utility modernization initiatives continue to improve charging accessibility, supporting strong market momentum across the southern United States.
Market Segmentations:
By Charger Type
- Slow Charger
- Fast Charger
By Connector Type
- CHAdeMO
- Combined Charging System
- Others
By Level of Charging
- Level 1
- Level 2
- Level 3
By Connectivity
- Non-connected Charging Stations
- Connected Charging Stations
By Application
- Commercial
- Residential
By Geography
- West
- Northeast
- Midwest
- South
Competitive Landscape
Competitive landscape analysis of the U.S. Electric Vehicle (EV) Charging Station Market highlights the strong presence of key players including ChargePoint, Inc., Tesla, Inc., ABB Ltd., bp pulse, General Electric Company, Delta Electronics, Inc., EVgo, Blink Charging, SemaConnect, and Webasto Group. The market is characterized by rapid network expansion, technology differentiation, and strategic collaborations aimed at strengthening geographic coverage and charging speed capabilities. Leading companies focus on deploying fast and ultra-fast charging solutions, enhancing software platforms, and integrating smart energy management systems. Partnerships with utilities, fleet operators, and retail chains play a critical role in improving accessibility and utilization rates. Continuous investments in interoperability, reliability, and user experience are shaping competition, while mergers, acquisitions, and long-term service agreements are enabling players to scale operations and maintain strong positioning in an increasingly infrastructure-intensive market.
Key Player Analysis
- ABB Ltd.
- SemaConnect Inc.
- Delta Electronics, Inc.
- Tesla, Inc.
- bp pulse
- General Electric Company
- Webasto Group
- ChargePoint, Inc.
- ClipperCreek, Inc.
- Leviton Manufacturing Co., Inc.
Recent Developments
- In December 2025, EVgo Inc. partnered with Miller Electric Company to deploy more than 40% of its charging stations using domestically manufactured prefabricated modular skids, accelerating installations and cutting costs.
- In November 2025, Jolt acquired Volta's 3,000 EV charging network in the U.S. from Shell to expand its operations.
- In April 2025, ChargePoint announced a new AC Level 2 charging product architecture featuring bidirectional charging and speeds up to double typical rates, with North American models arriving by end of 2025.
- In May 2025, Eaton and ChargePoint established a partnership to integrate EV charging with infrastructure solutions, co-developing bidirectional and V2X technologies for U.S. deployments
Report Coverage
The research report offers an in-depth analysis based on Charger Type, Connector Type, Level of Charging, Connectivity, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The U.S. Electric Vehicle (EV) Charging Station Market will continue to expand rapidly, supported by sustained growth in electric vehicle adoption across all vehicle segments.
- Public and private investments will accelerate nationwide charging infrastructure deployment, particularly along highways and in urban centers.
- Fast and ultra-fast charging stations will gain wider adoption to meet consumer demand for reduced charging time.
- Residential and workplace charging installations will increase with rising EV ownership in multi-unit housing and commercial facilities.
- Fleet electrification will drive demand for high-capacity and depot-based charging solutions.
- Smart charging and software-driven energy management will enhance network efficiency and grid stability.
- Integration of renewable energy and energy storage with charging stations will support sustainability goals.
- Standardization and interoperability of connectors and payment systems will improve user experience.
- Utility participation and grid modernization initiatives will strengthen charging reliability and scalability.
- Strategic partnerships and consolidation among charging providers will shape long-term market structure.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the U.S. Electric Vehicle (EV) Charging Station Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the U.S. Electric Vehicle (EV) Charging Station Market projected to grow between 2024 and 2032?
What types of EV charging stations currently dominate the US market?
How will the Bipartisan Infrastructure Law impact the growth of the US EV charging station market?
Who are the leading companies in the U.S. Electric Vehicle (EV) Charging Station Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 U.S. Electric Vehicle (EV) Charging Station Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Selected Country & Subnational Markets Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 U.S. Electric Vehicle (EV) Charging Station Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,250 million → 2032: USD 29,060.41 million)
- 2.1.2 Volume & Revenue – National Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 U.S. Electric Vehicle (EV) Charging Station Segmentation Snapshot
- 2.2.1 Market Split by Subnational Area – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. U.S. Electric Vehicle (EV) Charging Station Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 U.S. Electric Vehicle (EV) Charging Station Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage Across Domestic Markets
- 3.2 U.S. Electric Vehicle (EV) Charging Station Drivers
- 3.3 U.S. Electric Vehicle (EV) Charging Station Restraints & Challenges
- 3.4 U.S. Electric Vehicle (EV) Charging Station Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 U.S. Electric Vehicle (EV) Charging Station Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 U.S. Electric Vehicle (EV) Charging Station Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 National & Subnational Regulatory Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, U.S. Electric Vehicle (EV) Charging Station category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 U.S. Electric Vehicle (EV) Charging Station Attractiveness Analysis
- 4.1.1 By Subnational Area – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Subnational Area – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Subnational Area – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Domestic Market Opportunity Scorecards
- 4.5.1 Priority Domestic Market 1
- 4.5.2 Priority Domestic Market 2
- 4.5.3 Priority Domestic Market 3
- 4.5.4 Priority Domestic Market 4
Note: Domestic market scorecards cover relevant states, provinces, territories, cities, or economic zones within the selected country. Numbered entries are populated with market names suited to the national administrative structure and research scope. Geographic share tables use one consistent, nonoverlapping set of areas.
Chapter 5. U.S. Electric Vehicle (EV) Charging Station Cross-Border Trade & Market Access Analysis
- 5.1 National Trade & International Partner Overview
- 5.1.1 Export Value by Destination Country (2024)
- 5.1.2 Export Volume by Destination Country (2024) (Where Applicable)
- 5.1.3 Import Value by Source Country (2024)
- 5.1.4 Import Volume by Source Country (2024) (Where Applicable)
- 5.1.5 National & Partner-Country Trade Balances (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Destination Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 National Participation in Regional Trade & Economic Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter covers international trade relevant to U.S. Electric Vehicle (EV) Charging Station in the selected country. Exports are analyzed by destination and imports by source. Domestic interregional flows are excluded from international trade totals. Goods, services, and digital offerings use applicable classifications; volume and route analyses apply only where meaningful.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 U.S. Electric Vehicle (EV) Charging Station Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Multinational, National & Local Player Dynamics
- 6.2 U.S. Electric Vehicle (EV) Charging Station Share Analysis – 2024
- 6.2.1 National Revenue Share by Company
- 6.2.2 National Volume Share by Company (Volume Where Applicable)
- 6.2.3 Company Revenue Share by Subnational Area
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 National Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 U.S. Electric Vehicle (EV) Charging Station Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Revenue Exposure Across Domestic Markets
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in U.S. Electric Vehicle (EV) Charging Station (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in U.S. Electric Vehicle (EV) Charging Station
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. U.S. Electric Vehicle (EV) Charging Station – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Subnational Market Analysis – Country Overview
- 8.1 Domestic Geographic Market Overview
- 8.1.1 Subnational Volume Share (Where Applicable)
- 8.1.2 Subnational Revenue Share
- 8.1.3 Market Volume by Subnational Area (Where Applicable)
- 8.1.4 Market Revenue by Subnational Area
- 8.1.5 Subnational Forecasts Through 2032
- 8.2 Cross-Area Segment Analysis Within the Country
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. U.S. Electric Vehicle (EV) Charging Station – Priority Domestic Market 1
Chapter 10. U.S. Electric Vehicle (EV) Charging Station – Priority Domestic Market 2
Chapter 11. U.S. Electric Vehicle (EV) Charging Station – Priority Domestic Market 3
Chapter 12. U.S. Electric Vehicle (EV) Charging Station – Priority Domestic Market 4
Chapter 13. U.S. Electric Vehicle (EV) Charging Station Company Profiles
- 13.1 [Company 01]
- 13.1.1 Company Overview
- 13.1.2 Key Management Personnel
- 13.1.3 Products & Services Portfolio
- 13.1.4 Financial Performance
- 13.1.5 Domestic Market Focus & Local Operating Presence
- 13.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 14. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 15. Research Methodology
- 15.1 Research Framework & Philosophy
- 15.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 15.3 Data Modeling – National Market Sizing & Subnational Allocation
- 15.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 15.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 15.6 Quality Control – Four-Layer Validation Framework
- 15.7 Limitations & Standard Assumptions
- 15.8 Disclaimer
