
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| U.S. Lawn Mower Market Size 2024 | USD 6,431.71 Million |
| U.S. Lawn Mower Market, CAGR | 5.40% |
| U.S. Lawn Mower Market Size 2032 | USD 9,796.06 Million |
Market Overview
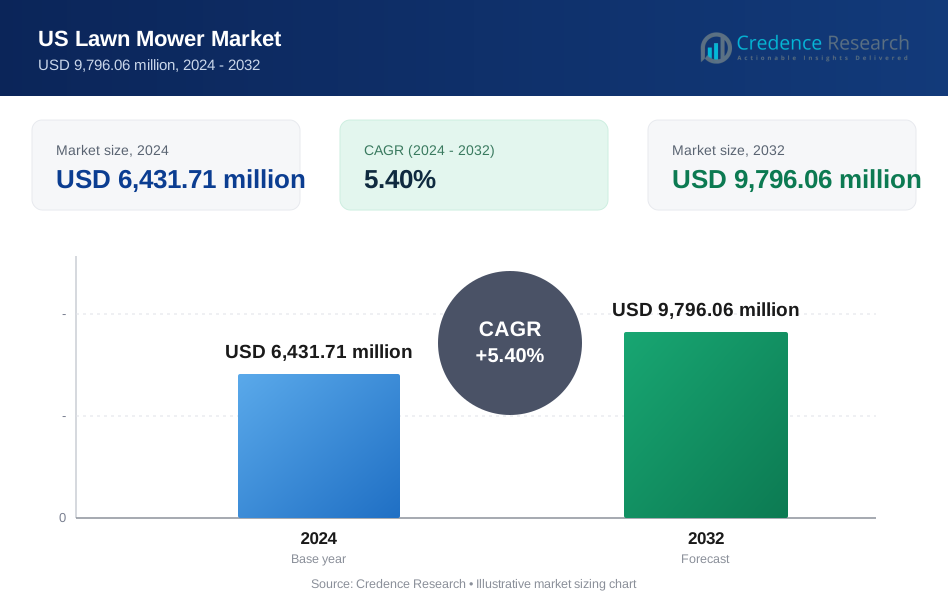
The U.S. Lawn Mower Market is projected to grow from USD 6,431.71 million in 2024 to an estimated USD 9,796.06 million by 2032, reflecting a compound annual growth rate (CAGR) of 5.40% from 2025 to 2032. This growth is driven by technological advancements, increased adoption of robotic mowers, and a rising preference for electric models due to environmental concerns.
Key drivers include technological innovations such as robotic and electric mowers, as well as a growing emphasis on eco-friendly lawn care solutions. Trends indicate a shift towards smart, connected devices that integrate with home automation systems.
Geographically, North America holds a significant share of the lawn mower market, with the U.S. leading due to its large residential and commercial sectors. Key players in this market include companies like Deere & Company, Honda Motor Co., and Husqvarna Group, which are recognized for their innovative products and strong distribution networks.
Market Insights
- The U.S. Lawn Mower Market is expected to grow from USD 6,431.71 million in 2024 to USD 9,796.06 million by 2032, driven by technological advancements and consumer preference for eco-friendly solutions.
- Key drivers include innovations in robotic and electric mowers, with increasing adoption due to environmental concerns and the demand for convenience and automation in lawn care.
- A growing emphasis on reducing carbon footprints is pushing consumers to adopt electric and battery-powered mowers, aligning with sustainability trends in lawn care.
- The rise of smart home systems is driving demand for connected lawn mowers that offer remote control and optimized scheduling features.
- High initial costs of advanced mowers like robotic and electric models may limit adoption, particularly among price-sensitive consumers.
- North America, particularly the U.S., holds a significant share of the market, with the South and Midwest regions leading due to their extensive residential and commercial properties.
- Major players like Deere & Company, Honda Motor Co., and Husqvarna Group are key contributors to the market, known for their strong distribution networks and product innovation.
Market Drivers
Increased Adoption of Smart Technology and Automation
Another significant driver of the U.S. lawn mower market is the increasing adoption of smart technologies in lawn care equipment. The integration of the Internet of Things (IoT) in lawn mowers is transforming them into connected devices that offer greater control and convenience for users. Smart mowers can now be controlled remotely through mobile apps, allowing homeowners to schedule mowing sessions, monitor battery levels, and track the mower's performance. Some models even come equipped with GPS, enabling them to map out the lawn and optimize their cutting paths for efficiency. The ability to integrate lawn mowers with smart home systems is also becoming more common, enabling users to operate their lawn care equipment alongside other connected devices such as smart irrigation systems and home automation networks. Additionally, automated mowers that work independently, requiring minimal human intervention, are becoming increasingly attractive due to their convenience. As more consumers embrace smart home technology, the demand for smart lawn care devices, including robotic and app-controlled mowers, will continue to rise, fueling the growth of the market.
Growing Interest in Residential Landscaping and Lawn Care
The U.S. lawn mower market is also benefiting from the rising interest in residential landscaping and outdoor living spaces. As more homeowners seek to improve the aesthetics of their yards and create enjoyable outdoor environments, the demand for lawn care equipment, including mowers, has increased. Factors such as the growing popularity of DIY home improvement projects and the desire for a well-maintained lawn are contributing to the expansion of the lawn care market. According to recent surveys, homeowners in the U.S. are increasingly investing in their lawns as part of larger home improvement or landscaping initiatives. The trend of enhancing curb appeal, along with the increased focus on outdoor spaces for recreation and relaxation, is pushing more consumers to invest in high-quality lawn care equipment. Furthermore, as new residential developments continue to emerge, the demand for lawn mowers in suburban areas and newly built homes is expanding. This surge in residential landscaping, paired with consumers’ growing focus on lawn aesthetics, will continue to drive the demand for lawn mowers, further boosting market growth.
Technological Advancements in Lawn Mower Designs
Technological innovations are one of the primary drivers propelling the growth of the U.S. lawn mower market. Over the past few years, there has been a marked shift towards more efficient, user-friendly, and eco-conscious lawn mowers. For instance, surveys from companies like Husqvarna highlight consumer preferences for sustainable solutions, with many consumers opting for battery-powered equipment due to its environmental benefits. The advent of electric and robotic lawn mowers has drastically altered consumer preferences, driven by the desire for a more sustainable and low-maintenance lawn care solution. Robotic mowers, in particular, are gaining popularity due to their autonomous functionality, which allows users to program them to mow lawns on their own. These devices rely on advanced sensors and algorithms to navigate and adjust to various lawn terrains, making them increasingly convenient for residential and commercial use. In addition, electric mowers are favored for their minimal environmental impact compared to traditional gas-powered models, aligning with the growing trend toward environmental sustainability.
Rising Consumer Demand for Eco-Friendly Lawn Care Solutions
The increasing awareness surrounding environmental sustainability is significantly influencing the U.S. lawn mower market. Consumers are now more conscious of the environmental impact of their purchases, and as a result, there is a strong shift toward eco-friendly lawn care solutions. For instance, reports from organizations like the CoPIRG Foundation emphasize the negative impacts of air pollution from gas-powered equipment, highlighting the benefits of transitioning to electric alternatives. Gas-powered mowers, which have traditionally dominated the market, contribute to pollution and greenhouse gas emissions. In contrast, electric mowers offer a greener alternative by operating with minimal environmental impact. This shift is also in line with the growing trend of reducing one's carbon footprint, particularly in urban and suburban areas where outdoor pollution levels are a major concern. With the rise of climate-conscious consumers, companies are innovating to meet the demand for low-emission, energy-efficient lawn mowers. Additionally, advancements in technology have enhanced the appeal of electric mowers, further driving consumer interest in environmentally friendly lawn care equipment.
Market Trends
Integration of Smart Technology and Connectivity
Another key trend in the U.S. lawn mower market is the integration of smart technology and connectivity into lawn care equipment. As part of the broader shift toward smart homes, many lawn mower manufacturers are incorporating features that allow users to connect their mowers to their smartphones, enabling remote control and monitoring of lawn care tasks. Smart lawn mowers can be controlled via dedicated apps, allowing users to schedule mowing sessions, adjust cutting heights, and track battery life from the convenience of their mobile devices. This connectivity also extends to integrating mowers with other smart home systems, such as smart irrigation or weather forecasting devices, providing homeowners with more comprehensive control over their outdoor environments. For instance, some advanced mowers can adjust their mowing schedules based on weather patterns, ensuring that the lawn is mowed at the optimal time for health and efficiency. The IoT (Internet of Things) integration in lawn mowers is a significant factor driving market growth as consumers increasingly seek out devices that offer convenience, automation, and enhanced user experience. As the Internet of Things continues to expand, the lawn mower market will likely see further adoption of connected devices, transforming the way consumers approach lawn care.
Growth of the Landscaping and Outdoor Living Trend
The increasing focus on landscaping and outdoor living spaces is another key trend shaping the U.S. lawn mower market. As homeowners continue to invest in their outdoor spaces for recreational and aesthetic purposes, the demand for high-quality lawn care equipment is on the rise. Landscaping has become a central part of home improvement projects, with many homeowners treating their lawns as an extension of their living spaces. In line with this trend, lawn mowers are evolving to meet the needs of consumers who prioritize a well-manicured lawn. Lawn care is now seen as an integral part of home maintenance, and the desire for a pristine lawn has led to increased sales of advanced mowers that offer superior cutting performance, ease of use, and efficiency. In addition to aesthetic improvements, outdoor spaces are becoming more functional, with many homeowners adding features such as outdoor kitchens, fire pits, and seating areas. As a result, the demand for lawn mowers is rising as homeowners seek to maintain beautiful and well-kept outdoor areas. Furthermore, the trend toward outdoor living has been accelerated by the COVID-19 pandemic, which prompted people to spend more time at home and invest in improving their living environments. As landscaping continues to grow in popularity, the demand for premium lawn care equipment, including advanced mowers, will likely remain strong in the coming years.
Shift Toward Electric and Battery-Powered Mowers
One of the most prominent trends in the U.S. lawn mower market is the ongoing shift from traditional gas-powered mowers to electric and battery-powered models. This transition is primarily driven by increasing consumer awareness of environmental sustainability, as electric mowers offer a cleaner and quieter alternative to their gas counterparts. For instance, the California Air Resources Board (CARB) has implemented regulations requiring all new lawn mowers sold in California to be zero-emission by 2024, reflecting a broader shift toward eco-friendly technologies. Additionally, advancements in battery technology have made electric lawn mowers more practical, offering longer battery life and faster charging times. Many consumers are also drawn to the reduced maintenance requirements of electric mowers, as they have fewer moving parts than gas-powered models and do not require oil changes, reducing the time and money spent on upkeep. As electric mowers continue to gain popularity, manufacturers are responding by enhancing their features, including improved cutting performance and greater ease of use.
Rise in Robotic Lawn Mowers
The demand for robotic lawn mowers has seen significant growth in the U.S. market, driven by the increasing desire for convenience and automation in lawn care. Robotic mowers offer consumers the ability to automate lawn mowing, requiring minimal human intervention. For instance, companies like Toro have introduced battery-powered residential yard care robotic mowers with advanced features such as wire-free navigation and smartphone app control, making these devices more accessible and user-friendly. These autonomous devices are equipped with sensors, GPS technology, and advanced algorithms that enable them to navigate lawns, avoid obstacles, and optimize mowing patterns for efficient operation. Robotic mowers are particularly appealing to busy homeowners who want to maintain a neat lawn without dedicating time to manual mowing. Moreover, robotic mowers align with the broader trend toward smart home devices, as many models can be controlled remotely through mobile apps, allowing homeowners to schedule mowing sessions and receive maintenance notifications.
Market Challenges
Battery Life and Charging Time Limitations
Despite advancements in battery technology, the limitations of battery life and long charging times remain a significant challenge for the U.S. lawn mower market, especially for electric and robotic mowers. While electric mowers are favored for their environmental benefits and quieter operation, the battery capacity can limit their usability, particularly for larger lawns. Consumers may face the inconvenience of needing to recharge their mowers during or between mowing sessions, which can disrupt lawn care routines. Robotic mowers, which operate autonomously, also rely on battery life to function, and while some models can return to charging stations automatically, they may still struggle to cover large or complex lawns in one go. These limitations may deter some potential buyers from adopting electric or robotic models, especially those who require longer operational times without interruptions. As a result, battery life and charging time remain key factors influencing purchasing decisions and pose a challenge to widespread adoption of these advanced technologies.
High Initial Cost of Advanced Lawn Mowers
One of the significant challenges in the U.S. lawn mower market is the high initial cost associated with advanced models, particularly electric and robotic mowers. These models integrate cutting-edge technologies such as GPS mapping, app-based controls, and automation systems, which enhance convenience and efficiency but also significantly increase production costs. For instance, robotic mowers often include advanced sensors and navigation systems that make them more expensive compared to traditional gas-powered or electric models. Similarly, electric mowers, while eco-friendly and cost-effective in the long run, require advanced battery technology, which contributes to their higher upfront prices.This cost barrier can deter adoption among price-sensitive consumers or those with smaller lawns who may not perceive sufficient value in these advanced features. Additionally, maintenance requirements for high-tech components can further add to ownership costs. To address this challenge, manufacturers could focus on reducing production costs through economies of scale and technological innovations. Offering entry-level models with essential features at more affordable prices could also help broaden accessibility. Furthermore, subscription or rental services are emerging as viable options to mitigate the impact of high upfront costs, allowing consumers to experience the benefits of advanced mowers without a long-term financial commitment.
Market Opportunities
Expansion of Smart Lawn Care Solutions
One significant opportunity in the U.S. lawn mower market lies in the growing demand for smart and connected lawn care solutions. As the trend toward home automation and IoT devices continues to rise, there is an increasing interest in integrating lawn mowers with smart home ecosystems. This provides an opportunity for manufacturers to innovate and develop lawn mowers equipped with advanced sensors, GPS technology, and remote control capabilities via mobile apps. Consumers are increasingly seeking devices that offer convenience, efficiency, and automation, and smart lawn mowers can fulfill these needs by allowing users to control their mowers remotely, monitor their performance, and even schedule mowing sessions based on weather forecasts or lawn conditions. The potential for integration with other smart home devices, such as irrigation systems, presents an exciting opportunity for growth. By capitalizing on this trend and offering advanced features like machine learning for optimized lawn care, manufacturers can appeal to tech-savvy consumers and create a differentiated product offering in a competitive market.
Growing Focus on Eco-Friendly Lawn Care
Another major opportunity for growth in the U.S. lawn mower market is the increasing consumer demand for environmentally sustainable lawn care solutions. As eco-consciousness rises, consumers are increasingly choosing electric and battery-powered mowers over gas-powered models due to their lower emissions and reduced environmental impact. This growing preference for sustainable products presents an opportunity for manufacturers to expand their portfolios of electric and robotic lawn mowers, catering to the environmentally aware consumer segment. Additionally, as government regulations and incentives for reducing carbon emissions continue to evolve, there will likely be further demand for eco-friendly lawn care solutions. Manufacturers who focus on energy-efficient technologies and the development of long-lasting, low-maintenance products are poised to tap into this emerging market, responding to both consumer preferences and regulatory pressures.
Market Segmentation Analysis
By Product Type
The market is divided into walk-behind mowers, ride-on mowers, and robotic mowers. Walk-behind mowers dominate the segment, consisting of various models such as reel mowers, self-propelled mowers, push mowers, and hover mowers. These mowers are primarily used for residential lawns due to their affordability and ease of use. Ride-on mowers, including standard ride-on, zero-turn, lawn tractors, and garden tractors, are more suitable for larger residential properties and commercial use, offering superior comfort and efficiency for extensive lawns. Robotic mowers, although relatively new, are gaining traction for their autonomous operation, making them attractive to tech-savvy homeowners and businesses seeking automation in lawn care.
By Fuel Type
Lawn mowers are classified by fuel source, including manual-powered, gas-powered, propane-powered, and electric-powered options. Gas-powered mowers remain the most widely used due to their strong performance and ability to handle large lawns. However, the market is shifting towards electric-powered options due to increasing environmental awareness, with electric-corded and electric-cordless/battery-powered mowers gaining popularity. Propane-powered mowers are a growing segment, as they offer lower emissions and cleaner operation compared to gas-powered models. Manual-powered mowers are typically preferred for small lawns due to their simplicity and eco-friendliness.
Segments
Based on Product Type
- Walk-behind
- Reel
- Self-propelled
- Push
- Hover
- Ride-on
- Standard Ride-on
- Zero-turn
- Lawn Tractors
- Garden Tractors
- Robotic
Based on Fuel Type
- Manual-Powered
- Gas-Powered
- Propane-Powered
- Electric-Corded
- Electric-Cordless/Battery-Powered
Based on End User
- Residential Users
- Professional Landscaping Services
- Golf Courses & Other Sports Arenas
- Government & Others
Based on Drive Type
- AWD
- FWD
- RWD
- Manual
Based on Blade Type
- Cylinder
- Standard/Deck
- Mulching
- Lifting
Based on Start Type
- No Start Required
- Keyed Start
- Push Start
- Recoil Start
Based on Distribution Channel
- Offline
- Dealers & Distributors
- Specialty Stores
- Mass Market Players
- Online
- Direct Sales
- Third-Party
Based on Region
- Northeast Region
- South Region
- Midwest Region
- West Region
- Pacific Northwest Region
Regional Analysis
Northeast Region (20%)
The Northeast region holds a significant share of the U.S. lawn mower market, driven by its high population density and a growing trend of urban gardening and landscaping. The region experiences a temperate climate, which leads to a substantial demand for residential lawn care products during the spring and summer months. Additionally, the increasing adoption of eco-friendly products like electric and battery-powered mowers has contributed to market growth in urban areas, where environmental sustainability is a priority. The demand for robotic mowers is also gaining traction in suburban and affluent urban neighborhoods, where consumers seek automated lawn care solutions.
South Region (30%)
The South region commands the largest market share, due to its extensive residential and commercial landscapes. The warm climate throughout the year ensures consistent demand for lawn mowers, with both residential users and commercial landscaping services investing in high-performance equipment. The preference for ride-on mowers, particularly zero-turn and lawn tractors, is prevalent in the South, where larger properties and estates are more common. Furthermore, the growth of professional landscaping services in this region presents opportunities for manufacturers to target commercial and industrial buyers. As the region continues to expand, there is growing interest in automated and electric models, as well as an increasing focus on sustainability.
Key players
- American Honda Motor Co., Inc.
- Ariens Company
- Briggs & Stratton
- John Deere
- Greenworks Tools
Competitive Analysis
The U.S. lawn mower market is highly competitive, with several key players dominating the landscape. Honda Motor Co., Inc. is a significant player, known for its reliable and durable gas-powered mowers, as well as innovations in eco-friendly and electric models. Ariens Company has made a strong impact with its high-performance ride-on mowers, particularly appealing to commercial landscaping services. Briggs & Stratton maintains a robust market presence with its engine technologies and comprehensive range of both residential and commercial lawn care equipment. John Deere is a market leader, offering a wide variety of premium mowers that cater to both residential and professional users, emphasizing innovation and performance. Meanwhile, Greenworks Tools has carved out a niche by offering environmentally friendly, battery-powered mowers, tapping into the growing demand for sustainable and low-maintenance solutions. These companies are constantly evolving through technological advancements and strategic product diversification to maintain competitive advantages in a rapidly changing market.
Recent Developments
- In October 2024, Honda introduced a new line of battery-powered lawn mowers at the Equip Exposition, including walk-behind models like HRX, HRN, and HRC, as well as a battery-powered zero-turn-radius (ZTR) lawn mower. These models are scheduled to be available in Spring 2025.
- In June 2023, Chervon (parent company of EGO) announced a partnership with John Deere to offer EGO's battery-powered lawn care products through John Deere dealers in the U.S. and Canada.
- In February 2023, John Deere introduced the Z370R Electric ZTrak, an all-electric residential zero-turn mower featuring a 3.2 kWh battery, capable of mowing up to two acres per charge.
Market Concentration and Characteristics
The U.S. lawn mower market is moderately concentrated, with several large players dominating the landscape, including Honda, John Deere, Briggs & Stratton, and Ariens Company, along with emerging brands like Greenworks Tools. These key players have a strong market presence across various segments, from residential to commercial mowers, with a focus on technological advancements, eco-friendly solutions, and product diversification. The market is characterized by intense competition, particularly in the ride-on and robotic mower segments, as manufacturers seek to meet the growing demand for innovative, efficient, and sustainable lawn care products. While large companies hold a significant share, smaller players focusing on niche segments like battery-powered or robotic mowers are also gaining ground. The increasing emphasis on environmental sustainability and smart home integration further influences the market dynamics, pushing companies to continuously evolve to stay competitive.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Fuel Type, End User, Drive Type, Blade Type, Start Type, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The growing emphasis on environmental sustainability will continue to drive the demand for electric and battery-powered lawn mowers. Consumers are increasingly opting for low-emission products to reduce their carbon footprint.
- Robotic lawn mowers will see significant growth due to their autonomous operation and convenience. As technology advances, these mowers will become more affordable and efficient, appealing to tech-savvy consumers.
- The integration of smart technologies in lawn mowers will increase, enabling features like remote control, scheduling, and performance monitoring. Consumers will seek connected devices that offer convenience and automation in lawn care.
- As the demand for professional landscaping services grows, there will be an increased need for high-performance mowers. Commercial buyers will continue to invest in durable and efficient equipment to cater to large properties.
- Consumers will increasingly prefer low-maintenance mowers, such as electric and robotic models, which offer reduced upkeep compared to traditional gas-powered models. This trend will support the rise of battery-powered solutions.
- The improvement in battery technology will lead to longer runtimes and quicker recharge times, enhancing the efficiency and appeal of electric mowers. This will further increase their adoption for larger lawns.
- With the demand for more efficient lawn care solutions, the popularity of zero-turn and ride-on mowers will grow. These mowers offer superior maneuverability and comfort for larger residential and commercial spaces.
- The online sales channel will continue to expand, offering consumers a wider variety of mowers, competitive pricing, and convenience. Direct sales from manufacturers and third-party platforms will dominate the market.
- Stricter regulations on emissions and noise pollution will drive the demand for eco-friendly and quieter mowers. Manufacturers will innovate to meet environmental standards and capitalize on these regulatory changes.
- Smart mowing systems that integrate with home automation systems will gain popularity. Consumers will increasingly adopt these systems to optimize lawn care based on weather patterns and soil conditions, further advancing the trend toward smart homes.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Technological Advancements and Smart Integration
The integration of IoT, GPS, and app-based controls in lawn mowers is transforming them into smart devices, enabling remote operation, optimized scheduling, and seamless integration with home automation systems. This technological evolution is attracting tech-savvy consumers and driving market growth.
Shift Toward Eco-Friendly and Electric Models
Growing environmental awareness and regulatory pressures are pushing consumers and commercial buyers to adopt electric and battery-powered mowers, which offer lower emissions and quieter operation compared to traditional gas-powered models. This shift is further supported by advancements in battery technology, making electric mowers more practical and appealing.
Rising Adoption of Robotic and Automated Mowers
The demand for convenience and automation in lawn care is fueling the adoption of robotic mowers, which can operate autonomously with minimal human intervention. These products appeal to busy homeowners and commercial users seeking efficient, low-maintenance solutions.
Expansion of Residential Landscaping and Outdoor Living
Increased investment in residential landscaping and the trend toward enhancing outdoor living spaces are boosting demand for high-quality lawn care equipment. Homeowners are prioritizing lawn aesthetics and functionality, leading to higher sales of advanced mowers across suburban and newly developed areas.
Growth of Professional Landscaping Services
The expansion of commercial landscaping services, particularly in regions with large estates and commercial properties, is driving demand for high-performance, durable mowers. Professional buyers require reliable equipment for extensive and frequent use, supporting market growth in the commercial segment.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the U.S. Lawn Mower Market in 2023 and 2032?
What are the main drivers of growth in the U.S. Lawn Mower Market?
Which regions dominate the U.S. Lawn Mower Market?
How is smart technology impacting the U.S. Lawn Mower Market?
What key players are driving the U.S. Lawn Mower Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Residential Users
- 1.2.2 Professional Landscaping Services
- 1.2.3 Golf Courses & Other Sports Arenas
- 1.2.4 Government & Others
- 1.3 By Fuel Type
- 1.3.1 Manual-Powered
- 1.3.2 Gas-Powered
- 1.3.3 Propane-Powered
- 1.3.4 Electric-Corded
- 1.3.5 Electric-Cordless/Battery-Powered
- 1.4 By Product Type
- 1.4.1 Walk-behind (Reel, Self-propelled, Push, Hover)
- 1.4.2 Ride-on (Standard Ride-on, Zero-turn, Lawn Tractors, Garden Tractors)
- 1.4.3 Robotic
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6,431.71 million → 2032: USD 9,796.06 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 US Lawn Mower Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 US Lawn Mower Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 US Lawn Mower Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 US Lawn Mower Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 US Lawn Mower Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 US Lawn Mower Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 US Lawn Mower Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 US Lawn Mower Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6,431.71 million → 2032: USD 9,796.06 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 US Lawn Mower Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Residential Users
- 12.3.7.2 Professional Landscaping Services
- 12.3.7.3 Golf Courses & Other Sports Arenas
- 12.3.7.4 Government & Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Fuel Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Manual-Powered
- 12.4.7.2 Gas-Powered
- 12.4.7.3 Propane-Powered
- 12.4.7.4 Electric-Corded
- 12.4.7.5 Electric-Cordless/Battery-Powered
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Walk-behind (Reel, Self-propelled, Push, Hover)
- 12.5.7.2 Ride-on (Standard Ride-on, Zero-turn, Lawn Tractors, Garden Tractors)
- 12.5.7.3 Robotic
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 US Lawn Mower End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 US Lawn Mower Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 US Lawn Mower Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 US Lawn Mower Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 John Deere
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 American Honda Motor Co., Inc.
- 18.4 Ariens Company
- 18.5 Briggs & Stratton
- 18.6 Greenworks Tools
- 18.7 Husqvarna Group
- 18.8 Toro Company
- 18.9 MTD Products
- 18.10 Chervon (EGO)
- 18.11 Craftsman
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

