
Market Overview:
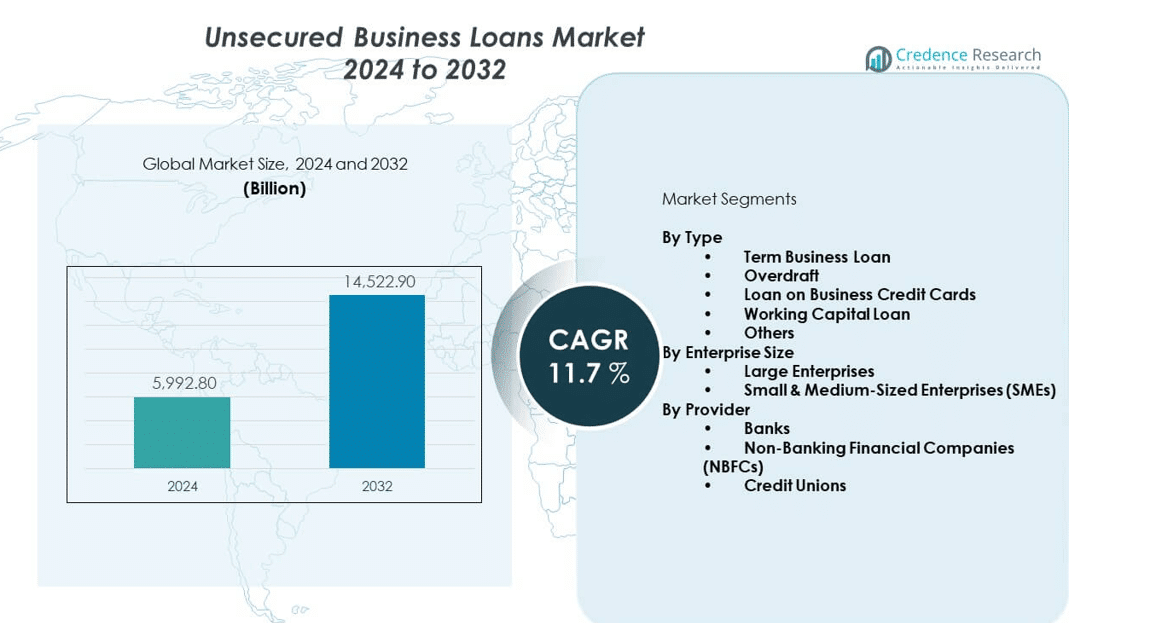
The Unsecured business loans market is projected to grow from USD 5,992.8 million in 2024 to an estimated USD 14,522.9 million by 2032, reflecting a compound annual growth rate (CAGR) of 11.7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Unsecured Business Loans Market Size 2024 | USD 5,992.8 million |
| Unsecured Business Loans Market, CAGR | 11.7% |
| Unsecured Business Loans Market Size 2032 | USD 14,522.9 million |
The market growth is primarily driven by increasing capital requirements of SMEs, rising preference for short-term financing, and the need for immediate liquidity without collateral obligations. Businesses are actively seeking alternatives to traditional bank loans, and lenders are responding with competitive interest rates, streamlined documentation, and customized solutions. The rapid penetration of digital lending platforms and AI-driven credit risk assessment tools is further enhancing accessibility, improving loan disbursal speed, and strengthening borrower confidence.
From a geographic perspective, North America leads the unsecured business loans market due to its mature financial infrastructure, high credit penetration, and widespread adoption of digital lending solutions. Europe follows with strong demand from SMEs in countries such as Germany and the UK, supported by government-backed financing initiatives. The Asia-Pacific region is emerging as the fastest-growing market, driven by rapid SME expansion in China, India, and Southeast Asia, along with increased reliance on fintech-based lending. Latin America and the Middle East & Africa are also gaining momentum as financial inclusion initiatives and startup ecosystems fuel loan demand.
Market Insights:
- The unsecured business loans market was valued at USD 5,992.8 million in 2024 and is projected to reach USD 14,522.9 million by 2032, growing at a CAGR of 7% during the forecast period.
- Rising capital needs of small and medium enterprises (SMEs) are driving demand for quick and collateral-free financing solutions.
- The growing adoption of digital lending platforms, AI-driven credit assessments, and alternative data usage is improving loan accessibility.
- High default risk and credit assessment complexities remain major restraints, particularly in volatile business environments.
- Stringent regulatory requirements and compliance costs create challenges for lenders, especially smaller and cross-border operators.
- North America leads the market due to mature financial infrastructure and strong digital adoption, while Europe follows with government-backed SME financing programs.
- Asia-Pacific is emerging as the fastest-growing region, supported by rapid SME expansion, fintech penetration, and government initiatives promoting financial inclusion.
Market Drivers:
Rising Demand from Small and Medium Enterprises for Accessible Financing:
The unsecured business loans market is expanding because SMEs require quick access to capital without pledging collateral. These businesses often face barriers in securing traditional bank loans due to limited credit history and lack of assets. Unsecured loans provide them with a viable option to meet working capital needs, expand operations, and invest in growth. It enables enterprises to handle short-term expenses like payroll, inventory, and supplier payments effectively. Digital lenders are filling the gap by offering instant approvals with minimal documentation. This accessibility has encouraged more businesses to explore unsecured borrowing. It strengthens entrepreneurial ecosystems, especially in emerging economies. By simplifying financing, the market supports sustained SME growth and economic development.
- For instance, Kabbage, a leading digital lender, processed over 200,000 unsecured loans totaling $6 billion to SMEs within a single year.
Technological Integration Enhancing Loan Approvals and Risk Assessments:
It benefits from technological advancements that are transforming loan approval processes. Artificial intelligence and machine learning algorithms are enabling more accurate credit assessments. Lenders are increasingly using digital footprints, alternative data, and automated scoring to evaluate borrowers. This reduces the dependence on conventional financial statements and improves loan accessibility. Fintech platforms offer end-to-end digital loan applications, eliminating paperwork delays. This speed encourages more businesses to rely on unsecured borrowing for urgent requirements. Technology-driven efficiency boosts lender confidence and widens the pool of eligible borrowers. By streamlining the process, innovation is making unsecured loans more attractive and sustainable in the long term.
- For instance, Upstart’s AI-powered lending platform approved loans within a quarter, significantly reducing default rates through predictive analytics.
Growing Preference for Flexible Repayment Options Supporting Borrower Adoption:
The unsecured business loans market is benefiting from greater flexibility in repayment structures. Borrowers seek terms that align with revenue cycles and seasonal cash flow variations. Lenders are responding with customized repayment schedules, reducing default risk. This adaptability is especially critical for businesses in retail, hospitality, and agriculture. It promotes confidence among borrowers who might otherwise avoid loan commitments. Flexible structures improve financial planning and business resilience. Competitive loan offerings with tailored terms encourage repeat borrowing. By addressing real business challenges, this driver reinforces the reliability and appeal of unsecured loans.
Expansion of Alternative Lending Channels Increasing Market Reach:
It is also gaining momentum due to the rise of alternative lending channels. Peer-to-peer lending platforms and non-banking financial companies are reaching underserved businesses. These institutions bridge the financing gap left by traditional banks. They provide quicker approvals and simplified terms that attract first-time borrowers. The diversity of providers enhances competition, leading to better interest rates and loan terms. Alternative channels also foster financial inclusion in developing regions. With lower entry barriers, businesses that were previously excluded gain access to funding. This driver ensures the steady expansion of the unsecured business loans market across industries and geographies.
Market Trends:
Increasing Digital Transformation in Lending Ecosystems and Borrower Experiences:
The unsecured business loans market is witnessing strong digital transformation trends. Online applications and instant approvals are now standard in the industry. Lenders are adopting mobile-first platforms to provide seamless borrower experiences. Digital signatures and automated verification processes are reducing turnaround times. Businesses appreciate the convenience of securing loans without visiting branches. It positions digital lenders as trusted partners for growing enterprises. Cloud-based platforms are improving scalability for lenders, enabling them to process higher volumes. This trend continues to redefine the competitive landscape in favor of technology-driven solutions.
- For instance, OnDeck offers term loans from $5,000 to $250,000 with repayment terms up to 24 months. The platform enables same-day funding for loans up to $100,000, with the loan approval process typically completed within 24-48 hours.
Rising Influence of Embedded Finance and Strategic Partnerships with Ecosystems:
It is evolving with embedded finance solutions that integrate lending into business platforms. Payment gateways, accounting software, and e-commerce platforms are embedding loan offerings. This integration allows businesses to access financing at the point of need. Partnerships between fintech firms and industry ecosystems are reshaping service delivery. Businesses gain loans linked to real-time cash flow data, reducing approval hurdles. Embedded models improve transparency and borrower engagement. The growing influence of ecosystem-based lending ensures wider adoption. This trend positions the unsecured business loans market as a central part of business digital ecosystems.
- For instance, Square Capital integrated its lending product into over 3 million merchant accounts by 2024, delivering embedded loans averaging $10,000 directly through sellers’ payment dashboards.
Growing Role of Sustainable and Responsible Lending Practices Across Regions:
Sustainability is emerging as a notable trend in unsecured business lending. Lenders are developing loan products that encourage eco-friendly business initiatives. Borrowers are incentivized through lower interest rates for green practices. It reflects rising demand for responsible financial products in global markets. Governments and regulators are supporting lenders with sustainability-linked frameworks. Green financing enhances reputational value for lenders and businesses alike. The trend is gaining traction among SMEs focused on environmental responsibility. By aligning with global sustainability agendas, this trend strengthens the market’s long-term appeal.
Expansion of Cross-Border Lending Enabled by Technology and Globalization:
It is benefiting from the expansion of cross-border lending opportunities. Digital platforms enable international lenders to reach small businesses globally. Currency exchange integration and global compliance systems support this shift. Businesses in developing nations gain access to international credit lines. This trend diversifies funding options beyond domestic lenders. It opens opportunities for enterprises seeking growth in foreign markets. Cross-border platforms build transparency with real-time monitoring of repayments. The unsecured business loans market is positioned to thrive as globalization reshapes financial accessibility.
Market Challenges Analysis:
Rising Default Risk and Credit Assessment Complexities Affecting Loan Portfolios:
The unsecured business loans market faces significant challenges in managing default risks. Lenders must rely heavily on credit scoring systems and alternative data due to the absence of collateral. Unpredictable business cycles, economic downturns, and market disruptions elevate risk exposure. SMEs with limited financial history create difficulties in precise risk evaluation. Lenders struggle to balance accessibility with profitability, especially in volatile markets. Interest rate hikes and inflationary pressures further increase borrower stress. These conditions often lead to higher non-performing loan ratios. It compels lenders to continuously refine credit risk models and monitoring mechanisms.
Regulatory Pressures and Compliance Burdens Limiting Market Expansion:
It also contends with regulatory and compliance challenges across regions. Financial regulators impose strict lending norms to protect borrowers and stabilize credit markets. Lenders face increasing requirements around transparency, interest rate disclosures, and fair practices. Compliance with anti-money laundering and data protection laws adds complexity. These regulations increase operational costs for both traditional banks and fintech platforms. Smaller lenders face disproportionate compliance burdens, limiting their competitiveness. Cross-border expansion requires alignment with diverse legal frameworks, slowing growth. The unsecured business loans market is constrained by such regulatory hurdles, which challenge its pace of expansion while ensuring borrower protection.
Market Opportunities:
Expanding Financial Inclusion and SME Growth Potential Driving Market Penetration:
The unsecured business loans market is well-positioned to capitalize on financial inclusion opportunities. Emerging economies have large unbanked and underbanked business populations. Digital lending platforms can extend financing to these underserved segments. SMEs in these regions seek funds to fuel expansion, job creation, and innovation. Governments are promoting supportive policies to empower small enterprises. It creates fertile ground for lenders to penetrate new markets. The opportunity to bridge financing gaps can unlock significant revenue potential. Expanding financial inclusion establishes long-term resilience for the market.
Leveraging Artificial Intelligence and Blockchain for Innovative Lending Solutions:
It can further grow by embracing advanced technologies like AI and blockchain. AI-driven tools enhance borrower profiling and predictive credit scoring. Blockchain introduces transparency, security, and efficiency in loan contracts. These innovations reduce operational risks and build borrower confidence. Technology enables cost-effective scaling for lenders targeting diverse markets. By adopting these solutions, lenders can differentiate their offerings from competitors. This opportunity will enhance trust, attract global investors, and improve operational sustainability. The unsecured business loans market can transform with technology-driven opportunities for growth and innovation.
Market Segmentation Analysis:
By Type
The unsecured business loans market by type is driven by the dominance of term business loans, which provide structured repayment schedules and predictable costs, making them the most widely used option for enterprises seeking stability. Overdraft facilities remain popular among businesses requiring short-term liquidity to manage operational gaps, while loans on business credit cards cater to smaller transactions and flexible expenses. Working capital loans are gaining importance among SMEs for managing cash flow cycles, while other products such as merchant financing and invoice-backed loans are addressing niche requirements.
- For instance, OnDeck facilitated over 50,000 term loans averaging $50,000 each, supporting SME stability through tailored repayment terms.
By Enterprise Size
Large enterprises utilize unsecured loans to support expansion strategies, acquisitions, and large-scale operational needs. However, the demand is highest among small and medium-sized enterprises, which often face restricted access to secured credit due to limited collateral availability. It serves as a critical financing tool for SMEs to manage growth, working capital, and unexpected expenses, highlighting their strong contribution to overall market expansion.
- For instance, BlueVine provides business lines of credit up to $250,000 with competitive interest rates starting as low as for qualified customers. It has supported over 750,000 U.S. businesses with capital access and banking solutions.
By Provider
Banks hold a significant share of the unsecured business loans market due to established credibility, extensive networks, and competitive rates. Non-banking financial companies (NBFCs) are expanding their role by offering faster approvals and flexible products, which are attractive to SMEs with limited credit histories. Credit unions, while smaller in scale, serve as an important source of community-based financing, offering personalized lending solutions to local businesses. Together, these providers create a diverse competitive landscape that ensures wide accessibility of unsecured loans to enterprises of varying scales and requirements.
Segmentation:
By Type
- Term Business Loan
- Overdraft
- Loan on Business Credit Cards
- Working Capital Loan
- Others
By Enterprise Size
- Large Enterprises
- Small & Medium-Sized Enterprises (SMEs)
By Provider
- Banks
- Non-Banking Financial Companies (NBFCs)
- Credit Unions
Regional Analysis:
North America
North America holds the largest share of the unsecured business loans market, accounting for nearly 35% of global revenue. The region benefits from a mature financial infrastructure, high credit penetration, and strong adoption of digital lending solutions. Banks and fintech firms in the United States and Canada lead innovation with AI-based credit assessments and instant loan approvals. Government-backed support programs for SMEs further strengthen market adoption. It continues to expand as businesses seek flexible financing alternatives to traditional secured loans. Competitive interest rates and diverse product offerings drive consistent demand. The presence of leading global financial institutions ensures a stable market outlook.
Europe
Europe represents around 28% of the unsecured business loans market, supported by strong SME activity and favorable regulatory initiatives. Countries such as Germany, the United Kingdom, and France dominate lending volumes, while emerging markets in Eastern Europe show steady growth. European lenders are focusing on sustainable financing models, integrating green loan products with unsecured lending structures. It benefits from policy support aimed at improving SME access to capital, particularly in post-pandemic recovery phases. Fintech adoption and open banking frameworks accelerate competition and efficiency in the region. Strong cross-border financing and partnerships further diversify opportunities. The market in Europe demonstrates a balanced mix of traditional banking strength and fintech innovation.
Asia-Pacific and Other Regions
Asia-Pacific accounts for nearly 25% of the unsecured business loans market and is the fastest-growing region. Expanding SME sectors in China, India, and Southeast Asia drive demand for unsecured lending solutions. Rising fintech penetration and digital inclusion initiatives provide strong growth momentum. It benefits from government schemes promoting financial access for small businesses and startups. Latin America contributes around 7% of market share, supported by Brazil and Mexico, where SMEs are adopting alternative lending platforms. The Middle East & Africa hold about 5% share, with growth tied to financial inclusion programs and startup financing needs. Together, these regions represent significant untapped opportunities for lenders expanding global reach.
Key Player Analysis:
- American Express Company
- Bajaj Finserv Ltd
- Bank of America Corporation
- Deutsche Bank AG
- Funding Circle
- HDFC Bank Ltd
- OnDeck
- Wells Fargo
- JPMorgan Chase & Co.
- Citigroup Inc.
- Goldman Sachs
- Barclays PLC
- HSBC Holdings PLC
- ICICI Bank
- Standard Chartered
- Capital One Financial Corp.
- BNP Paribas
- UBS Group AG
- Santander Group
Competitive Analysis:
The unsecured business loans market is highly competitive, with global banks, non-banking financial companies, and fintech platforms shaping the landscape. Large financial institutions such as JPMorgan Chase, HSBC, and Citigroup dominate through wide distribution networks and strong credit evaluation frameworks. Fintech players like Funding Circle and OnDeck enhance competition by offering faster approvals and flexible terms tailored for SMEs. NBFCs and regional banks are gaining traction in emerging economies by addressing underserved markets. It is defined by product innovation, digital lending technologies, and strategic collaborations that strengthen accessibility and borrower confidence.
Recent Developments:
- In July 2025, Bajaj Finserv Ltd initiated a Loan Utsav campaign in India, offering unsecured business loans up to Rs. 80 lakh. The campaign included additional cashback rewards and brand vouchers, targeting small and medium-sized businesses with fast approval and flexible repayment options.
- In February 2025, HDFC Bank announced plans to expand its loan securitization business over the next 3-5 years to accommodate growing investor demand and to strategically support growth in retail deposits and unsecured loans.
Market Concentration & Characteristics:
The unsecured business loans market shows moderate to high concentration, with leading global banks, fintech lenders, and NBFCs holding substantial market presence. It is characterized by diverse providers competing on interest rates, repayment flexibility, and technological integration. Established banks leverage scale and credibility, while fintech firms introduce speed and innovation, challenging traditional models. Regional and local lenders focus on SMEs and underserved markets, balancing the competitive dynamics. The market demonstrates high growth potential, with technology adoption and financial inclusion driving increased accessibility worldwide.
Report Coverage:
The research report offers an in-depth analysis based on Type, Enterprise Size, and Provider. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand from SMEs will continue to dominate unsecured loan adoption across global markets.
- Banks will maintain market leadership but face stronger competition from fintech entrants.
- AI-driven credit scoring and blockchain will redefine lending efficiency and transparency.
- Embedded finance models will expand loan accessibility within business ecosystems.
- Sustainable and green loan products will emerge as competitive differentiators.
- Regulatory frameworks will tighten, requiring greater compliance and transparency.
- Asia-Pacific will remain the fastest-growing regional market due to SME expansion.
- Cross-border digital lending platforms will create new international opportunities.
- Flexible repayment models will drive borrower confidence and repeat adoption.
- Strategic partnerships between banks and fintech firms will strengthen market growth.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
SME Capital Needs and Accessibility
Small and medium-sized enterprises (SMEs) increasingly require quick, collateral-free financing to manage working capital, expansion, and operational expenses. Unsecured business loans provide a viable alternative to traditional bank loans, especially for businesses lacking sufficient assets or credit history.
Digital Lending Platforms and AI Integration
The rapid adoption of digital lending platforms and AI-driven credit assessment tools has streamlined loan applications, improved risk evaluation, and accelerated disbursal processes. This technological integration enhances accessibility and borrower confidence, fueling market growth.
Flexible Repayment Structures
Lenders are offering more flexible repayment options tailored to business cash flow cycles and seasonal variations, reducing default risk and making unsecured loans more attractive to a wider range of enterprises.
Expansion of Alternative Lending Channels
Peer-to-peer lending platforms and non-banking financial companies (NBFCs) are reaching underserved businesses with faster approvals and simplified terms, increasing competition and broadening market reach beyond traditional banks.
Embedded Finance and Ecosystem Partnerships
The integration of lending solutions into business platforms such as payment gateways and e-commerce systems enables businesses to access financing at the point of need, driving adoption and embedding unsecured loans within broader digital business ecosystems.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Unsecured business loans market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Unsecured business loans market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the Unsecured business loans market?
Who are the leading companies in the Unsecured business loans market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Term Business Loan
- 1.2.2 Overdraft
- 1.2.3 Loan on Business Credit Cards
- 1.2.4 Working Capital Loan
- 1.2.5 Others
- 1.3 By Provider
- 1.3.1 Banks
- 1.3.2 Non-Banking Financial Companies (NBFCs)
- 1.3.3 Credit Unions
- 1.4 By Enterprise Size
- 1.4.1 Large Enterprises
- 1.4.2 Small & Medium-Sized Enterprises (SMEs)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5,992.8 million → 2032: USD 14,522.9 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Unsecured Business Loans Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Unsecured Business Loans Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Unsecured Business Loans Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Unsecured Business Loans Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Unsecured Business Loans Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Unsecured Business Loans Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Unsecured Business Loans Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Unsecured Business Loans Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5,992.8 million → 2032: USD 14,522.9 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Unsecured Business Loans Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Term Business Loan
- 12.3.6.2 Overdraft
- 12.3.6.3 Loan on Business Credit Cards
- 12.3.6.4 Working Capital Loan
- 12.3.6.5 Others
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Provider - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Banks
- 12.4.6.2 Non-Banking Financial Companies (NBFCs)
- 12.4.6.3 Credit Unions
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Enterprise Size - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Large Enterprises
- 12.5.6.2 Small & Medium-Sized Enterprises (SMEs)
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Unsecured Business Loans Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Unsecured Business Loans Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Energy Efficiency and Resource Management
- 14.7 Sustainability, Recycling and Circularity
- 14.8 Technology Roadmap, 2024-2032
- 14.9 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Unsecured Business Loans Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 American Express Company
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 Bank of America Corporation
- 17.4 Funding Circle
- 17.5 OnDeck
- 17.6 HDFC Bank Ltd
- 17.7 Bajaj Finserv Ltd
- 17.8 JPMorgan Chase & Co.
- 17.9 HSBC Holdings PLC
- 17.10 Barclays PLC
- 17.11 Citigroup Inc.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

