
Market Overview
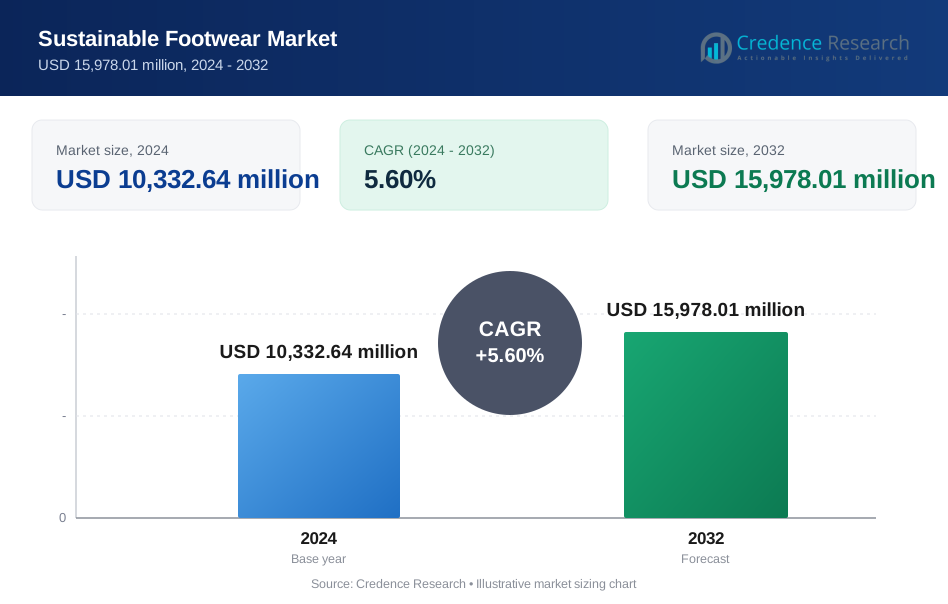
Sustainable Footwear Market size was valued at USD 10332.64 million in 2024 and is anticipated to reach USD 15978.01 million by 2032, at a CAGR of 5.60% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Sustainable Footwear Market Size 2024 | USD 10332.64 Million |
| Sustainable Footwear Market, CAGR | 5.60% d |
| Sustainable Footwear Market Size 2032 | USD 15978.01 Million |
The Sustainable Footwear Market grows on strong drivers such as rising consumer demand for eco-friendly products, stricter environmental regulations, and increasing adoption of recycled and plant-based materials in footwear production. Brands invest in ethical sourcing, circular economy models, and advanced manufacturing technologies to align with shifting consumer expectations. Key trends include the integration of digital transparency tools, expansion of e-commerce channels, and the rising popularity of athleisure and lifestyle footwear made with sustainable components. It reflects a market increasingly defined by innovation, inclusivity, and accountability, reinforcing sustainability as both a competitive advantage and a long-term growth strategy.
The Sustainable Footwear Market shows strong geographical presence across North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa, each reflecting distinct growth drivers shaped by consumer awareness, regulatory frameworks, and retail expansion. North America and Europe lead adoption with advanced sustainability initiatives and high consumer demand, while Asia-Pacific grows rapidly through manufacturing scale and rising eco-consciousness. Key players influencing competition include Adidas AG, Nike, PUMA SE, Timberland, Allbirds, Veja, Rothy’s, TOMS Shoes, Ecco Sko A/S, and Reebok.
Market Insights
- The Sustainable Footwear Market was valued at USD 10,332.64 million in 2024 and is projected to reach USD 15,978.01 million by 2032 at a CAGR of 5.60%.
- Rising consumer preference for eco-friendly products and adoption of recycled and plant-based materials drive market expansion.
- Stricter environmental regulations and corporate sustainability commitments push brands to adopt greener production practices.
- Key trends include growth in athleisure, lifestyle footwear, and digital transparency tools such as blockchain and QR codes.
- Competition intensifies as global leaders and niche innovators focus on ethical sourcing, circular economy models, and material innovation.
- Restraints include higher production costs, supply chain complexities, and lack of standardization in sustainability certifications.
- North America and Europe dominate with advanced initiatives, Asia-Pacific grows rapidly through manufacturing scale, while Latin America and Middle East & Africa show rising eco-consciousness supported by urbanization and retail expansion.

Market Drivers
Rising Consumer Preference for Eco-Friendly Materials
The Sustainable Footwear Market gains momentum from growing consumer awareness of environmental impact and demand for eco-friendly products. Shoppers actively seek shoes made from organic cotton, recycled plastics, natural rubber, and plant-based alternatives. Brands that replace synthetic components with renewable inputs strengthen credibility and customer loyalty. It accelerates adoption when products meet both style and sustainability expectations. Government regulations promoting reduced carbon footprints further support the shift toward sustainable raw materials. This driver reinforces the transition of footwear manufacturing into more environmentally responsible practices.
- For instance, Adidas produced over 30 million pairs of shoes in 2023 using recycled ocean plastic through its partnership with Parley for the Oceans, demonstrating large-scale integration of eco-materials into mainstream footwear.
Strong Growth in Ethical Fashion and Conscious Consumerism
Ethical fashion movements continue to influence the Sustainable Footwear Market. Consumers demand transparency in sourcing, labor practices, and production methods, driving brands to publish sustainability reports and adopt third-party certifications. It increases trust when companies demonstrate fair labor and ethical supply chain management. Younger demographics, particularly millennials and Gen Z, are most vocal in supporting brands aligned with ethical values. Social media platforms amplify awareness, helping niche sustainable footwear brands reach wider audiences. Ethical consumerism sets a standard that traditional footwear companies adapt to remain competitive.
- For instance, Allbirds reported in its 2023 Sustainability Report that it reduced its average product carbon footprint to 7.12 kg CO₂e per pair, down from 10.9 kg CO₂e in 2019, highlighting measurable progress in ethical and environmentally conscious footwear production.
Technological Advancements in Sustainable Manufacturing
Innovation in manufacturing processes supports expansion of the Sustainable Footwear Market. Advances in 3D knitting, waterless dyeing, and automated recycling technologies enable lower waste and higher production efficiency. It reduces reliance on resource-intensive methods and enhances scalability of sustainable footwear. Leading brands invest in research and development to design biodegradable soles, compostable materials, and modular shoes. Partnerships with material science firms accelerate the adoption of new technologies. This driver positions sustainability not only as an ethical priority but also as a platform for technical innovation.
Expansion of E-Commerce and Omnichannel Retail Strategies
Digital retailing strengthens the Sustainable Footwear Market by widening consumer access to eco-friendly products. Online platforms allow smaller sustainable brands to compete directly with global players, offering curated collections and transparent product information. It creates higher consumer confidence when platforms highlight certifications, material sources, and environmental impact data. Omnichannel strategies that integrate physical stores with digital experiences increase visibility of sustainable footwear. Subscription models and direct-to-consumer channels improve brand-customer relationships while reducing middlemen costs. This retail expansion ensures sustainable footwear reaches mainstream buyers and accelerates overall market penetration.
Market Trends
Adoption of Recycled and Plant-Based Materials
The Sustainable Footwear Market reflects strong momentum in the use of recycled plastics, plant-based leathers, and natural fibers. Brands focus on reducing dependency on virgin synthetics by incorporating recycled polyester, algae-based foams, and pineapple or mushroom leather alternatives. It aligns with consumer demand for eco-friendly products while reducing environmental impact. Large footwear companies invest in partnerships with material innovators to scale these options into mainstream collections. Smaller niche brands adopt plant-based materials as a key differentiator in competitive markets. This trend expands the material palette available to designers while strengthening sustainability credentials.
- For instance, Nike revealed in its 2023 Impact Report that it diverted over 109 million pounds of textile waste from landfills and used this material to produce Flyknit uppers across multiple footwear lines, showcasing measurable integration of recycled inputs at scale.
Growth of Circular Economy and Closed-Loop Systems
Circular economy models increasingly shape strategies in the Sustainable Footwear Market. Brands experiment with closed-loop programs that allow customers to return worn shoes for recycling or repurposing. It reduces landfill waste while creating new revenue streams through resale or material recovery. Advances in modular shoe design simplify disassembly and reuse of individual parts. Several companies explore compostable footwear solutions that fully biodegrade after use. This trend reinforces sustainability as a life cycle concept rather than a single product attribute.
- For instance, PUMA launched its RE:SUEDE pilot project in 2022, collecting over 500 pairs of biodegradable sneakers to test industrial composting, and expanded its “Bring Me Back” recycling program that gathered more than 120,000 pairs of used footwear across Europe.
Integration of Digital Tools and Transparency Practices
Digital platforms support consumer trust and awareness in the Sustainable Footwear Market. Brands use QR codes, blockchain tracking, and digital passports to showcase sourcing, carbon footprint, and production details. It allows customers to verify claims and make informed purchasing decisions. Social media campaigns amplify brand stories and educate buyers on sustainability initiatives. Online configurators enable personalized eco-friendly designs that appeal to style-conscious buyers. Transparent communication strengthens long-term loyalty in an increasingly competitive retail landscape.
Rising Influence of Lifestyle and Athleisure Segments
Lifestyle and athleisure categories dominate growth within the Sustainable Footwear Market, reflecting consumer demand for versatile, stylish, and functional designs. It gains traction as everyday sneakers, sandals, and casual footwear integrate eco-friendly features without compromising performance. Sportswear giants and fashion brands alike introduce sustainable activewear collections to capture demand from health-conscious and eco-aware buyers. Athleisure’s popularity ensures higher adoption rates for sustainable footwear across urban and suburban demographics. Expanding assortments of lightweight, performance-driven, and durable products further enhance market visibility. This trend establishes sustainable footwear as a mainstream lifestyle choice.
Market Challenges Analysis
High Production Costs and Supply Chain Constraints
The Sustainable Footwear Market faces challenges from elevated production costs associated with eco-friendly raw materials and innovative manufacturing processes. Organic cotton, plant-based leathers, and recycled polymers often require specialized sourcing and treatment, increasing expenses compared to conventional materials. It limits affordability for mass-market consumers and reduces margins for brands operating in competitive segments. Supply chain fragmentation further complicates procurement, with sustainable materials sourced from limited regions and subject to variable availability. Smaller brands often struggle to scale due to capital-intensive investments in ethical sourcing and certifications. These cost pressures slow down widespread adoption of sustainable footwear in price-sensitive markets.
Limited Standardization and Consumer Awareness Gaps
Standardization issues remain a barrier in the Sustainable Footwear Market, with inconsistent definitions and certifications for sustainability across regions. Consumers often find it difficult to distinguish authentic eco-friendly products from greenwashed alternatives, which undermines trust. It also places pressure on brands to prove transparency while competing with misleading claims. Awareness gaps persist in emerging markets where affordability outweighs environmental concerns. Retailers struggle to balance education with marketing, while ensuring clarity in product labeling and communication. This lack of uniform standards creates confusion in the marketplace and reduces the impact of sustainability initiatives.
Market Opportunities
Expansion of Premium and Lifestyle Segments
The Sustainable Footwear Market holds strong opportunities in the premium and lifestyle categories, where consumers are willing to pay for quality, design, and eco-friendly value. Growing urban populations demand stylish shoes that combine sustainability with performance, creating space for brands to expand fashion-forward sustainable lines. It supports differentiation when companies introduce limited-edition collaborations and luxury collections using responsibly sourced materials. Lifestyle sneakers, sandals, and casual footwear gain traction in both developed and emerging markets, driven by rising health and wellness culture. Retailers that merge comfort, durability, and environmental responsibility position themselves to attract long-term loyalty. This opportunity broadens sustainable footwear’s reach into mainstream fashion.
Growth Through Digital Channels and Innovation in Materials
Digital transformation creates new pathways for the Sustainable Footwear Market, enabling brands to scale globally through e-commerce and direct-to-consumer platforms. Online channels enhance visibility for smaller sustainable labels and allow larger companies to showcase transparency through traceability tools and digital product passports. It strengthens consumer trust when platforms highlight certifications and environmental impact data. Material innovation also creates opportunity, with breakthroughs in algae-based foams, mushroom leather, and biodegradable soles expanding product variety. Companies investing in R&D to commercialize these materials gain competitive edge while addressing regulatory and consumer expectations. This combination of technology and material innovation drives future growth potential.
Market Segmentation Analysis:
By Product Type
The Sustainable Footwear Market is segmented into athletic and non-athletic footwear, each catering to different consumer demands. Athletic footwear demonstrates strong growth due to rising fitness awareness and the popularity of athleisure trends. Brands introduce eco-friendly running shoes, trainers, and performance sneakers made with recycled polyester, algae-based foams, and biodegradable soles. It benefits from consumers prioritizing comfort and durability alongside sustainability. Non-athletic footwear, including casual shoes, sandals, and formal styles, represents the larger share due to its daily wear relevance. Expanding collections that combine fashion-forward design with sustainable fabrics appeal strongly to urban buyers. The balance of athletic and non-athletic categories ensures diverse growth across multiple lifestyle segments.
- For instance, Adidas reported selling 27 million pairs of its Ultraboost and Stan Smith models made with at least 50% recycled polyester in 2023, underscoring how sustainable materials are being integrated at scale within athletic product lines.
By Demographics
Demographic segmentation highlights the widespread adoption of eco-friendly footwear across men, women, and kids. Women’s footwear leads demand, supported by wider product variety, greater fashion consciousness, and early adoption of sustainable choices. Men’s footwear reflects steady expansion as brands introduce minimalist sneakers, outdoor shoes, and formal collections made with eco-friendly materials. It benefits from growing interest in ethical consumption among younger male consumers. Kids’ footwear is gaining attention as parents seek safe, non-toxic, and eco-certified options for their children. This segment creates long-term growth potential, with brands building customer loyalty from an early age. The demographic spread highlights the broad reach of sustainability in footwear across all consumer groups.
By Distribution Channel
Distribution channels play a pivotal role in shaping accessibility and awareness in the Sustainable Footwear Market. Online stores lead expansion, offering wide assortments, digital transparency tools, and direct-to-consumer models that reach global audiences. Specialty stores maintain relevance by providing curated collections and personalized experiences that highlight eco-friendly products. It ensures strong visibility for premium and niche sustainable brands. Supermarkets and hypermarkets contribute by integrating affordable eco-friendly footwear into mainstream retail. Other channels, including pop-up stores and eco-focused boutiques, expand brand presence in urban markets and strengthen engagement with conscious consumers. The diversity of retail channels ensures sustainability-driven footwear is accessible across both digital and physical platforms.
- For instance, Allbirds shipped 1,870,000 pairs of shoes directly through its online platform in 2023, while integrating a carbon footprint calculator for each product to enhance transparency for consumers, highlighting the impact of digital channels in promoting sustainable footwear.
Segments:
Based on Product Type:
- Athletic
- Non-Athletic
Based on Demographics:
- Men
- Women
- Kids
Based on Distribution Channel:
- Online Stores
- Specialty Stores
- Supermarket/Hypermarket
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America accounts for 32% of the Sustainable Footwear Market, reflecting its leadership position supported by strong consumer awareness and the presence of global footwear brands. The region benefits from high demand for eco-friendly sneakers, athleisure shoes, and casual footwear driven by urban populations prioritizing health, wellness, and sustainability. The United States dominates regional sales with large-scale adoption of recycled materials and plant-based leathers across mainstream collections. Canada contributes steadily with strong policy support for sustainable fashion initiatives and growing popularity of niche eco-friendly labels. It gains momentum from digital platforms that highlight transparency and sustainability certifications, which influence purchasing behavior. Investments in R&D and collaborations with material science companies further reinforce North America’s dominance in the global market.
Europe
Europe holds 29% of the Sustainable Footwear Market, making it the second-largest region with robust growth opportunities. Strong consumer consciousness about climate impact and strict regulatory standards drive regional demand for eco-certified and ethically produced footwear. Leading markets such as Germany, France, and the UK showcase early adoption of recycled fibers, biodegradable soles, and modular shoe designs. The region also demonstrates significant traction in luxury and premium footwear, where sustainability is positioned as both an ethical and fashionable choice. It benefits from extensive distribution networks that integrate eco-focused footwear into both specialty stores and high-end retail outlets. European Union directives supporting circular economy practices encourage brands to adopt closed-loop systems, further strengthening the region’s influence on global sustainability trends.
Asia-Pacific
Asia-Pacific represents 23% of the Sustainable Footwear Market, reflecting rapid expansion supported by rising disposable incomes and urbanization. Countries such as China, Japan, and India are emerging as key contributors to regional growth. It benefits from large-scale manufacturing capabilities and increasing adoption of sustainable materials within regional supply chains. Japan and South Korea lead in consumer-driven demand for eco-friendly fashion, while China scales production for both domestic consumption and exports. The popularity of online retail platforms accelerates growth by widening access to eco-friendly footwear among younger demographics. Expanding middle-class populations and rising fitness culture further reinforce demand for sustainable athletic and lifestyle footwear.
Latin America
Latin America accounts for 9% of the Sustainable Footwear Market, driven by increasing awareness of ethical consumption and eco-friendly lifestyle choices. Brazil and Mexico are the largest contributors, with growing urban populations and expanding e-commerce platforms boosting sales of sustainable footwear. It benefits from government initiatives promoting environmentally friendly practices in textiles and footwear. Regional manufacturers adopt recycled rubber and natural fibers, leveraging abundant raw material availability. The rise of niche sustainable brands creates differentiation in competitive markets dominated by imported footwear. Despite economic challenges, demand for eco-conscious products continues to strengthen among younger consumers.
Middle East & Africa
The Middle East & Africa represent 7% of the Sustainable Footwear Market, reflecting early-stage adoption compared to other regions. South Africa, the UAE, and Saudi Arabia lead regional demand, driven by rising urban populations and increasing awareness of sustainable fashion trends. It gains traction from premium and luxury footwear segments, where eco-friendly products appeal to affluent consumers. Limited local manufacturing capacity requires reliance on imports, but international brands expand regional presence through specialty stores and online platforms. Growth potential is strong in urban centers, where younger demographics adopt global sustainability trends. Government initiatives to diversify economies and promote sustainable industries further support long-term prospects in this region.
Key Player Analysis
- Timberland (a subsidiary of VF Corporation) – USA
- Veja – France
- TOMS Shoes – USA
- PUMA SE – Germany
- Allbirds – USA
- Rothy’s – USA
- Adidas AG – Germany
- Ecco Sko A/S – Denmark
- Reebok (a subsidiary of Adidas AG) – USA
- Nike, Inc. – USA
Competitive Analysis
The Sustainable Footwear Market include Adidas AG, Nike, Inc., PUMA SE, Reebok, Veja, Allbirds, TOMS Shoes, Ecco Sko A/S, Timberland, and Rothy’s. The Sustainable Footwear Market features a dynamic competitive landscape shaped by global sportswear leaders, premium fashion labels, and innovative start-ups. Large companies leverage scale, advanced manufacturing, and global distribution to integrate sustainable materials such as recycled polyester, natural rubber, and bio-based leathers across product lines. Smaller brands differentiate through agility, transparent supply chains, and niche collections that emphasize eco-friendly innovation. Competition centers on balancing sustainability with performance, affordability, and style to meet diverse consumer expectations. E-commerce expansion and direct-to-consumer models amplify visibility, enabling new entrants to challenge established players. The market reflects a blend of legacy strength and disruptive innovation, where sustainability serves as both a competitive advantage and a strategic necessity.
Recent Developments
- In March 2025, Collaborated with Tokyo-based artisan brand Hender Scheme for a unique heritage-modernity balance in footwear.
- In April 2024, Timberland debuted the Timberloop™ Go Roam sneaker, designed for circularity with components that can be disassembled and recycled. It responsibly sourced materials including 34% recycled rubber outsole.
- In May 2024, the Rothy's launched its collection on Amazon to broaden its reach. The brand’s bestselling shoes, including The Point, The Flat, and The Driving Loafer, are now available on Rothy’s Amazon storefront.
- In June 2024, THE TROPIC FEEL, S.L. launched All-Terrain Sneakers with a 5.5 mm thick rubber. These all-vegan sneakers have 18% recycled content and are also GRS-certified.
Market Concentration & Characteristics
The Sustainable Footwear Market demonstrates moderate concentration, with competition shaped by both established global brands and emerging niche players. It reflects characteristics of a market where sustainability acts as both a differentiator and a necessity, influencing design, material sourcing, and manufacturing practices. Large companies leverage scale, advanced technology, and global distribution to expand eco-friendly collections, while smaller firms compete by emphasizing innovation, transparency, and ethical sourcing. The market shows high product diversity, ranging from athletic footwear to premium lifestyle shoes, catering to eco-conscious consumers across income levels. It benefits from strong demand for recycled, biodegradable, and plant-based materials that align with consumer values. Growth is supported by digital platforms, which enable smaller brands to compete with legacy players and expand internationally. The structure highlights a balance of scale-driven advantages and innovation-led disruption, positioning sustainability as a central characteristic that defines long-term competitiveness.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Demographics, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for eco-friendly materials such as recycled polyester, natural rubber, and bio-based leather will continue to rise.
- Brands will expand investment in circular economy models including take-back and recycling programs.
- Digital tools such as blockchain and QR codes will increase transparency in sourcing and supply chains.
- Premium and lifestyle segments will grow as consumers seek both fashion and sustainability in footwear.
- Innovation in plant-based materials such as mushroom leather and algae foams will gain commercial scale.
- E-commerce and direct-to-consumer platforms will dominate distribution for sustainable footwear.
- Younger demographics will drive demand, with Gen Z and millennials prioritizing ethical consumption.
- Collaborations between footwear brands and material science companies will accelerate new product launches.
- Regulatory pressure in Europe and North America will push brands toward stricter sustainability compliance.
- Market competition will intensify as both global players and start-ups scale eco-friendly product portfolios.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Consumer Preference for Eco-Friendly Materials
Consumers are increasingly seeking footwear made from recycled, organic, and plant-based materials, prompting brands to innovate and expand sustainable product lines. This shift is reinforced by growing environmental awareness and government regulations promoting lower carbon footprints.
Growth in Ethical Fashion and Conscious Consumerism
Demand for transparency in sourcing, fair labor practices, and ethical supply chains is driving brands to adopt third-party certifications and publish sustainability reports. Younger demographics, especially millennials and Gen Z, are particularly influential in supporting brands with strong ethical commitments.
Technological Advancements in Sustainable Manufacturing
Innovations such as 3D knitting, waterless dyeing, and automated recycling technologies are enabling brands to reduce waste and improve production efficiency. These advancements make it easier to scale sustainable footwear while maintaining quality and performance.
Expansion of E-Commerce and Omnichannel Retail Strategies
Digital platforms and direct-to-consumer models are making sustainable footwear more accessible, allowing both established brands and new entrants to reach global audiences. Enhanced transparency tools and online configurators further build consumer trust and drive market penetration.
Adoption of Circular Economy and Closed-Loop Systems
Brands are increasingly implementing take-back, recycling, and modular design programs that reduce landfill waste and extend product lifecycles. These initiatives not only appeal to eco-conscious consumers but also create new revenue streams and reinforce sustainability as a core brand value.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Sustainable Footwear Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Sustainable Footwear Market projected to grow between 2025 and 2032?
Which Sustainable Footwear Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Sustainable Footwear Market?
Who are the leading companies in the Sustainable Footwear Market?
Which region commanded the largest share of the Sustainable Footwear Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Demographics
- 1.2.1 Men
- 1.2.2 Women
- 1.2.3 Kids
- 1.3 By Product Type
- 1.3.1 Athletic
- 1.3.2 Non-Athletic
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 10,332.64 million → 2032: USD 15,978.01 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Sustainable Footwear Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Sustainable Footwear Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Sustainable Footwear Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Sustainable Footwear Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Sustainable Footwear Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Sustainable Footwear Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Sustainable Footwear Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Sustainable Footwear Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 10,332.64 million → 2032: USD 15,978.01 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Sustainable Footwear Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Demographics - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Men
- 12.3.7.2 Women
- 12.3.7.3 Kids
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Athletic
- 12.4.7.2 Non-Athletic
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Sustainable Footwear Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Sustainable Footwear Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Sustainable Footwear Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Adidas AG
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Nike, Inc.
- 17.4 PUMA SE
- 17.5 Timberland
- 17.6 Allbirds
- 17.7 Veja
- 17.8 Rothy’s
- 17.9 TOMS Shoes
- 17.10 Ecco Sko A/S
- 17.11 Reebok
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

