
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
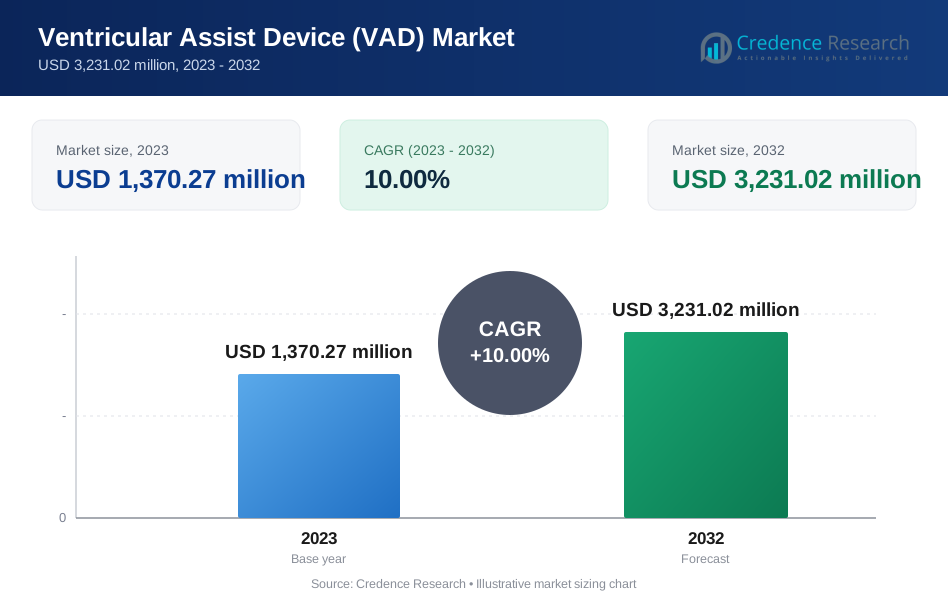
| Ventricular Assist Device (VAD) market Size 2023 | USD 1,370.27 million |
| Ventricular Assist Device (VAD) market, CAGR | 10.00% |
| Ventricular Assist Device (VAD) market Size 2032 | USD 3,231.02 million |
Market Overview
The Ventricular Assist Device (VAD) market is projected to grow from USD 1,370.27 million in 2023 to an estimated USD 3,231.02 million by 2032, reflecting a compound annual growth rate (CAGR) of 10.00% from 2024 to 2032. The rising prevalence of cardiovascular diseases, an aging population, and technological advancements in medical devices continue to drive demand for ventricular assist devices.
Market growth is primarily driven by the increasing incidence of heart disease globally and a growing number of end-stage heart failure patients requiring advanced treatment options. Additionally, advancements in device technology, such as miniaturization and improved biocompatibility, are enhancing patient outcomes and fueling demand. Increased awareness about heart failure treatment options and a surge in research and development activities further bolster market growth. Emerging trends such as fully implantable VADs and smart wearable technology integration promise to enhance the efficiency and patient experience of such devices.
Geographically, North America dominates the market due to a high prevalence of cardiovascular conditions, a robust healthcare infrastructure, and increased adoption of advanced medical technologies. Europe follows closely, driven by growing investments in healthcare and rising awareness of heart failure therapies. The Asia-Pacific region is anticipated to experience significant growth due to the increasing geriatric population and improvements in healthcare access. Key market players include Abbott Laboratories, Medtronic, Berlin Heart GmbH, Abiomed, Inc., and Jarvik Heart, Inc., among others.
Market Drivers
Rising Prevalence of Cardiovascular Diseases
The increasing prevalence of cardiovascular diseases (CVDs), particularly heart failure, is one of the major drivers of the Ventricular Assist Device (VAD) market. According to the World Heart Federation, cardiovascular disease deaths dramatically increased from 12.1 million in 1990 to 20.5 million in 2021. In the United States, an estimated 82.6 million people currently have one or more forms of cardiovascular disease. Cardiovascular diseases remain the leading cause of mortality worldwide, with millions of new cases reported each year. Heart failure is a significant health burden globally, affecting a substantial number of patients with limited treatment options. Specifically, nearly 75% of approximately 5 million patients are older than 65 years, with the incidence reaching around 20% among people over 75 years old. This condition often requires advanced interventions, such as ventricular assist devices, to support and improve heart function, especially in severe cases.VADs provide mechanical circulatory support, either as a bridge to heart transplantation or as a long-term treatment option for patients not eligible for transplant. The rising prevalence of CVDs necessitates efficient management strategies, leading to increased demand for VADs. The device market is further fueled by growing awareness and early diagnosis of heart diseases, which help in timely intervention and patient management.
Technological Advancements and Innovation in VADs
Continuous technological advancements have significantly propelled the Ventricular Assist Device market by making these devices safer, more reliable, and patient-friendly. Technological innovations have dramatically reduced VAD pump sizes, with devices like the Jarvik 2000 weighing just 85 grams, and the HeartWare HVAD weighing 145 grams - representing significant miniaturization compared to earlier models.Innovations such as the development of fully implantable devices, smaller and lighter VADs, and those with advanced sensors and telemetry capabilities have improved patient comfort and outcomes. Newer devices like the HeartMate III now feature artificial pulse generators and sensorless flow estimators, showcasing the rapid technological progression in VAD design. Modern VADs are designed to offer better biocompatibility, reduce complications such as infection and thrombosis, and improve the overall quality of life for patients.Moreover, new models emphasize minimally invasive implantation procedures, which contribute to reduced surgical risk and faster patient recovery. Companies are investing heavily in research and development to introduce more efficient and advanced devices, addressing challenges related to long-term durability, power management, and integration with digital monitoring solutions. The evolution of next-generation devices with wireless energy transfer and remote monitoring capabilities stands to enhance the overall adoption rate of VADs.
Increasing Geriatric Population and Rising Need for Heart Failure Management
The global aging population is a significant driver of the VAD market, as aging is closely associated with a higher risk of cardiovascular diseases. Heart failure represents the leading cause of hospitalization for patients older than 65 years in Western countries. A stark study revealed survival rates that highlight the critical nature of heart conditions: only 19% of black men, 16% of white men, 25% of black women, and 23% of white women survived 6 years after their first heart failure hospitalization.The elderly population often faces severe heart conditions due to age-related decline in cardiac function and comorbidities. The median survival after an initial heart failure hospitalization for 67- to 74-year-olds was just 2.3 to 3.6 years, significantly lower than the estimated life expectancy of 9.5 to 17.5 years for the same age range.As the number of older adults continues to rise, the incidence of heart failure cases is expected to grow, leading to a greater demand for ventricular assist devices. VADs play a critical role in extending and improving the quality of life for elderly patients who may not qualify for a heart transplant or who need mechanical circulatory support for survival.The demographic shift toward a larger elderly population presents a growing market for heart failure therapies, including VADs. Governments and healthcare organizations are focusing more on enhancing elderly patient care, and this trend further supports market growth by driving the adoption of life-saving technologies like VADs.
Expanding Healthcare Infrastructure and Increased Awareness Initiatives
Expanding healthcare infrastructure, especially in emerging economies, plays a pivotal role in driving the VAD market. Several countries are investing heavily in developing their healthcare systems, which include establishing advanced cardiac care facilities and improving access to critical treatments like ventricular assist devices. Enhanced healthcare access and insurance coverage for critical cardiac treatments make these devices more accessible to a broader patient population. Additionally, growing initiatives aimed at raising public awareness about heart failure, its symptoms, and available treatment options have positively impacted the demand for VADs. Healthcare organizations, government bodies, and industry leaders are launching campaigns and collaborating to improve education about heart health and therapies. Increasing patient awareness about advanced treatment options can prompt earlier intervention, resulting in higher demand for VADs. Moreover, the rising focus on value-based care and cost-effective solutions that deliver optimal patient outcomes is likely to further support the adoption of VADs in various regions.
Market Trends
Advancements in Fully Implantable Ventricular Assist Devices (VADs)
One of the most prominent trends in the Ventricular Assist Device (VAD) market is the development and increasing adoption of fully implantable devices. Traditional VADs often require external components, such as power cords and control systems, that extend outside the body, posing risks such as infection and reduced mobility. For instance, two patients have already been implanted with a transcutaneous energy transfer (TET) device, demonstrating the initial progress towards fully implantable VADs. The HeartWare HVAD, introduced in 2006, was a significant innovation that enabled less invasive implantation strategies compared to larger competitors like the Heart Mate II.Recent innovations have focused on overcoming these challenges through fully implantable VAD systems that eliminate the need for external components. These devices are powered wirelessly, often through transcutaneous energy transmission systems, which significantly enhance patient comfort, reduce the risk of infection, and improve overall quality of life. By offering a more seamless and discreet option, fully implantable devices are transforming the treatment landscape for patients with severe heart failure. Companies are also integrating smart technologies and telemetry for remote monitoring and real-time performance feedback, enabling personalized care and reducing hospital visits.
Integration of Artificial Intelligence (AI) and Digital Health Technologies
The integration of artificial intelligence (AI) and digital health technologies is another key trend reshaping the VAD market. AI-driven predictive analytics and advanced software systems are increasingly being employed to monitor VAD performance and patient health metrics. For instance, research groups like Antaki and colleagues have developed Bayesian models that can predict 12-month mortality with an area under the curve (AUC) of 0.70 and right ventricular failure with AUCs between 0.83 and 0.90 for different time points.These solutions enable healthcare professionals to detect complications early, optimize device settings, and enhance clinical decision-making. In another example, researchers have successfully used LVAD waveforms to predict impending pump failure in the HeartMate XVE LVAD and identify cardiac arrhythmias in the Debakey LVAD. Additionally, a telemonitoring study of 11 patients with HeartAssist 5 and acute VAD LVADs generated 6,216 alarm messages, primarily related to low-flow alarms and suspected pump thrombosis.AI algorithms can analyze data from VAD sensors to predict potential issues like pump thrombosis or heart failure exacerbations, thereby allowing timely interventions and improving patient outcomes. The use of connected health solutions, mobile applications, and wearable devices to track patient health in real-time further supports proactive care and improved patient engagement. The convergence of VAD technology with digital health is expected to drive advancements in remote patient management, reduce healthcare costs, and enhance the overall efficacy of VAD therapies. These technological developments represent a shift towards more sophisticated, patient-centered approaches in the VAD market.
Market Restraints and Challenges
High Cost of Implantable Ventricular Assist Devices and Limited Accessibility
One of the major challenges in the market for implantable ventricular assist devices (VADs) is their high cost, which poses a significant barrier to wider adoption. The costs associated with VADs include not only the device itself but also related expenses such as surgery, hospitalization, and long-term follow-up care. These devices often require highly specialized implantation procedures, which add to the total cost of treatment. For many patients, especially in developing regions with constrained healthcare budgets, the financial burden remains prohibitive. Furthermore, limited insurance coverage and complex reimbursement policies in some regions can exacerbate this issue, restricting access to life-saving VAD therapies. Healthcare providers, insurers, and policymakers must work together to address these economic barriers and explore strategies for cost reduction, broader insurance coverage, and patient financial support mechanisms to ensure equitable access.
Device-Related Complications and Durability Issues
Another significant restraint in the implantable VAD market is the potential for device-related complications and limitations in long-term durability. While VADs have evolved significantly, patients still face risks such as infection, bleeding, thrombosis (blood clotting), and device malfunctions. These complications can lead to extended hospital stays, additional medical procedures, and, in some cases, severe morbidity. Ensuring long-term device reliability and biocompatibility remains a challenge for manufacturers and healthcare providers. Additionally, the mechanical nature of these devices necessitates regular monitoring and maintenance, which can add to patient burden and healthcare costs. Addressing these issues requires continued innovation in device design, biocompatible materials, and preventive therapies to minimize complications. Overcoming these challenges will be critical to improving patient outcomes, enhancing trust in VAD therapy, and promoting broader market acceptance.
Market Segmentation Analysis
By Type
The market for ventricular assist devices can be segmented by type into pulsatile flow and continuous flow devices. Continuous flow VADs dominate the market due to their superior efficiency, smaller size, longer durability, and better patient outcomes. Continuous flow devices generate less wear and tear, leading to fewer mechanical failures and a longer lifespan. Pulsatile flow devices, while historically significant, are being gradually replaced by continuous flow devices due to their bulkier design and reduced longevity. However, pulsatile flow VADs may still hold value in specific cases where a more natural pumping action is required.
By Application
In terms of application, ventricular assist devices serve various therapeutic needs. The "Bridge to Transplant" application, which provides critical circulatory support for patients awaiting a heart transplant, remains one of the most prominent market segments. The "Destination Therapy" segment is gaining traction, especially among patients not eligible for heart transplants, offering long-term mechanical support. "Bridge to Candidacy" and "Bridge to Recovery" are also significant segments, with the former targeting patients who need mechanical support while waiting to become eligible for transplantation, and the latter focused on temporary support while allowing for potential cardiac recovery. These segments reflect the versatility and importance of VADs in heart failure management.
Segments
Based on type
- Pulsatile Flow
- Continuous Flow
Based on application
- Bridge to transplant
- Bridge to Candidacy
- Destination to Therapy
- Bridge to Recovery
- Others
Based on end user
- Hospital & ASCs
- Specialty Clinic
- Others
Based on product
- Left Ventricular Assist Device
- Right Ventricular Assist Device
- Bi- Ventricular Assist Device
Based on region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America (45%)
North America holds the largest market share for ventricular assist devices, accounting for approximately 45% of the global market. The region's dominance stems from a high prevalence of cardiovascular diseases and a well-established healthcare system capable of delivering advanced cardiac care. A strong focus on research and development, widespread adoption of technologically advanced VADs, and favorable reimbursement policies further bolster market growth. The United States leads this region with significant investments in medical innovation, a large number of heart failure patients requiring VADs, and specialized care centers. Canada also contributes with growing VAD adoption and a focus on advanced treatment for end-stage heart failure patients.
Europe (30%)
Europe represents around 30% of the global market share for ventricular assist devices, positioning it as a key region. Factors driving this market include increasing awareness about heart failure therapies, supportive government policies, and a robust medical device industry. Countries such as Germany, France, and the United Kingdom are at the forefront due to their advanced healthcare infrastructure and high healthcare expenditure. In addition, the region benefits from ongoing research collaborations and clinical trials, aiming to enhance VAD technology and treatment protocols. The European market is further supported by the growing number of cardiovascular centers specializing in mechanical circulatory support.
Key players
- Berlin Heart Overview
- ABIOMED
- Abbott
- Jarvik Heart, Inc.
Competitive Analysis
The Ventricular Assist Device (VAD) market is highly competitive, with key players such as Berlin Heart, ABIOMED, Abbott, and Jarvik Heart, Inc., driving innovation and market expansion. Berlin Heart specializes in both pediatric and adult VAD solutions, emphasizing device safety and clinical effectiveness. ABIOMED is known for its Impella heart pumps, offering minimally invasive solutions and a strong market presence. Abbott leverages its expertise in cardiovascular health to provide a comprehensive VAD portfolio, including the HeartMate series. Jarvik Heart, Inc. focuses on innovative VAD designs aimed at improving patient outcomes through durable and efficient devices. Companies in this market compete based on technological innovation, product differentiation, strategic collaborations, and expanding their global reach, reflecting a commitment to addressing the rising burden of heart failure.
Recent Developments
- In August 2023, Berlin Heart completed enrollment in the Berlin Heart EXCOR Active Driver Trial. This trial aims to gain FDA approval for their new EXCOR Active device.
- In December 2022, Johnson & Johnson acquired ABIOMED, a leader in heart recovery technologies, for $17.3 billion. This acquisition represents a significant development in the VAD market.
- In February 2023, Abbott launched the TEAM-HF trial. This trial is designed to assess the benefits of early use of the HeartMate 3 LVAD for patients with advanced heart failure.
Market Concentration and Characteristics
The Ventricular Assist Device (VAD) market is characterized by a moderate to high level of market concentration, with a few key players dominating the global landscape. Companies such as Abbott, ABIOMED, Berlin Heart, and Jarvik Heart, Inc. hold significant market shares due to their strong product portfolios, technological innovations, and established brand recognition in the field of mechanical circulatory support. The market is driven by continual advancements in device technology, regulatory approvals, and the development of minimally invasive and fully implantable solutions. Despite the presence of dominant players, there is room for emerging competitors to capture market share by introducing novel and cost-effective VAD solutions, addressing gaps in patient care, and expanding access in underserved regions. Market characteristics also include a focus on improving patient outcomes, reducing device complications, and integrating smart monitoring technologies to enhance the overall quality of life for patients.
Report Coverage
The research report offers an in-depth analysis based on type, application, end user, product and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will see the development of more advanced, smaller, and fully implantable VADs, enhancing patient comfort and reducing complications.
- AI-driven analytics and remote monitoring capabilities will be increasingly integrated with VADs to enable real-time tracking and proactive healthcare interventions.
- VADs are expected to be utilized for a wider range of patient profiles, including those with less severe heart failure, as therapies become more refined and accessible.
- Advancements in minimally invasive implantation techniques will reduce surgical risks and recovery times, encouraging broader adoption of VAD therapies.
- Increased healthcare infrastructure investment and growing awareness will drive VAD adoption in Asia-Pacific, Latin America, and the Middle East.
- Research and development efforts will focus on enhancing device durability and biocompatibility, addressing challenges like clotting and infection.
- With improved device efficacy and safety, VADs will increasingly be used as destination therapy for patients ineligible for heart transplants.
- Partnerships among healthcare providers, research institutions, and medical device companies will accelerate innovation and clinical trial success.
- Improved insurance coverage and reimbursement schemes in key markets will make VAD therapies more accessible to patients across socioeconomic strata.
- Efforts to reduce the cost of VAD devices and related care will drive affordability, promoting market penetration and increasing patient access to advanced therapies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Cardiovascular Diseases
The increasing incidence of cardiovascular diseases, particularly heart failure, is driving demand for ventricular assist devices as more patients require advanced mechanical circulatory support. This trend is amplified by the global burden of heart disease and the limited availability of donor hearts for transplantation.
Technological Advancements and Innovation in VADs
Continuous improvements in device miniaturization, biocompatibility, and the development of fully implantable and smart VADs are making these devices safer, more effective, and more comfortable for patients, thereby expanding their adoption.
Increasing Geriatric Population
As the global population ages, the number of elderly patients at risk for heart failure rises, leading to greater demand for VADs as both bridge-to-transplant and destination therapy options for those ineligible for heart transplants.
Expanding Healthcare Infrastructure and Awareness
Investment in healthcare infrastructure, especially in emerging markets, and increased awareness of advanced heart failure therapies are making VADs more accessible to a broader patient base, supporting market growth.
Integration of Digital Health and AI
The adoption of AI-driven analytics and remote monitoring technologies with VADs enables proactive patient management, early detection of complications, and improved clinical outcomes, further encouraging the use of these devices.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size and projected growth of the VAD market?
What factors are driving the growth of the VAD market?
How do VADs help patients with heart failure?
What are the latest trends in VAD technology?
Who are the major players in this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Pulsatile Flow
- 1.2.2 Continuous Flow
- 1.3 By Product
- 1.3.1 Left Ventricular Assist Device
- 1.3.2 Right Ventricular Assist Device
- 1.3.3 Bi-Ventricular Assist Device
- 1.4 By End User
- 1.4.1 Hospital & ASCs
- 1.4.2 Specialty Clinic
- 1.4.3 Others
- 1.5 By Application
- 1.5.1 Bridge to Transplant
- 1.5.2 Bridge to Candidacy
- 1.5.3 Destination Therapy
- 1.5.4 Bridge to Recovery
- 1.5.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 1,370.27 million → 2032: USD 3,231.02 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Ventricular Assist Device (VAD) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Ventricular Assist Device (VAD) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Ventricular Assist Device (VAD) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Ventricular Assist Device (VAD) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Ventricular Assist Device (VAD) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Ventricular Assist Device (VAD) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Ventricular Assist Device (VAD) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Ventricular Assist Device (VAD) Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 1,370.27 million → 2032: USD 3,231.02 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Ventricular Assist Device (VAD) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Pulsatile Flow
- 12.3.7.2 Continuous Flow
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Left Ventricular Assist Device
- 12.4.7.2 Right Ventricular Assist Device
- 12.4.7.3 Bi-Ventricular Assist Device
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End User - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Hospital & ASCs
- 12.5.7.2 Specialty Clinic
- 12.5.7.3 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Bridge to Transplant
- 12.6.7.2 Bridge to Candidacy
- 12.6.7.3 Destination Therapy
- 12.6.7.4 Bridge to Recovery
- 12.6.7.5 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Ventricular Assist Device (VAD) End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Ventricular Assist Device (VAD) Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Ventricular Assist Device (VAD) Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Ventricular Assist Device (VAD) Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Abbott Laboratories
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Medtronic
- 18.4 Berlin Heart GmbH
- 18.5 Abiomed, Inc.
- 18.6 Jarvik Heart, Inc.
- 18.7 Terumo Corporation
- 18.8 Sun Medical Technology Research Corp.
- 18.9 SynCardia Systems LLC
- 18.10 ReliantHeart Inc.
- 18.11 LivaNova PLC
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

