
Market Overview
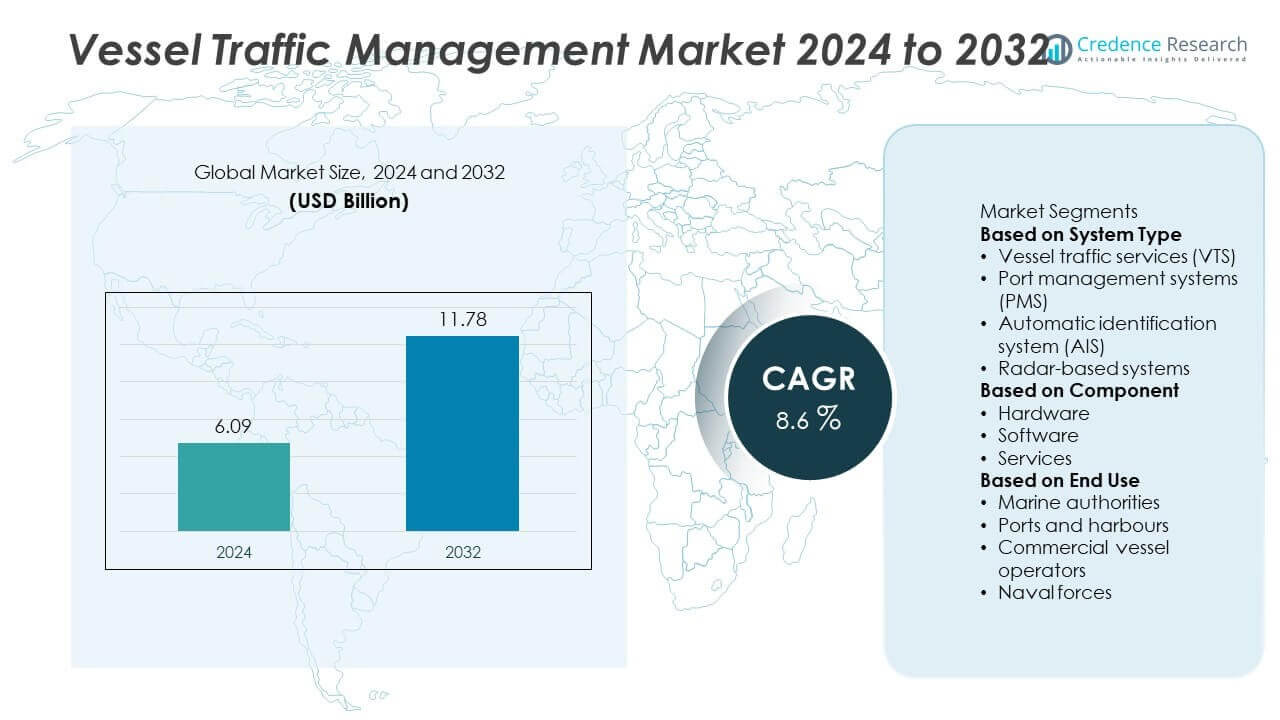
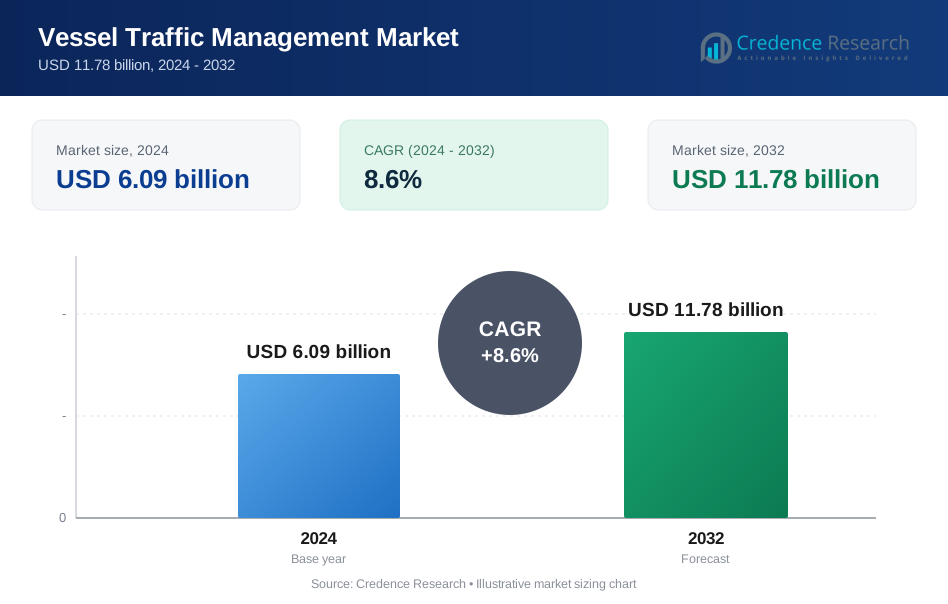
The Vessel Traffic Management Market size was valued at USD 6.09 billion in 2024 and is anticipated to reach USD 11.78 billion by 2032, growing at a CAGR of 8.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Vessel Traffic Management Market Size 2024 | USD 6.09 Billion |
| Vessel Traffic Management Market, CAGR | 8.6% |
| Vessel Traffic Management Market Size 2032 | USD 11.78 Billion |
The Vessel Traffic Management Market grows through rising global trade, expanding port operations, and increasing maritime safety requirements. Ports adopt advanced traffic management systems to optimize docking, reduce congestion, and improve turnaround times.
The Vessel Traffic Management Market shows strong geographical expansion across North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa, each region contributing with unique drivers. North America leads with adoption of advanced maritime safety systems supported by strong investments in port modernization and defense applications. Europe emphasizes digital transformation of ports, sustainability initiatives, and regulatory compliance, fostering demand for innovative vessel traffic technologies. Asia-Pacific grows rapidly with China, Japan, and South Korea investing heavily in smart ports and large-scale maritime trade routes. Latin America and the Middle East & Africa present emerging opportunities driven by port expansion projects and increasing trade flows. Key players such as Wärtsilä Corporation, Thales Group, Saab AB, and Transas focus on innovation, automation, and integration of advanced systems like radar, AIS, and analytics. Their strategies strengthen safety, efficiency, and competitiveness, ensuring wider adoption across global maritime operations.
Market Insights
- The Vessel Traffic Management Market was valued at USD 6.09 billion in 2024 and is projected to reach USD 11.78 billion by 2032, growing at a CAGR of 8.6%.
- Rising demand for maritime safety and efficiency drives adoption of vessel traffic management systems in ports and coastal regions.
- Trends highlight integration of radar, AIS, satellite, and real-time analytics to improve navigation and reduce port congestion.
- Leading companies including Wärtsilä Corporation, Thales Group, Saab AB, and Transas compete through innovation, automation, and advanced monitoring solutions.
- High installation costs, complex integration requirements, and regulatory variations act as restraints, limiting adoption in smaller ports.
- North America leads with advanced port modernization projects, Europe emphasizes sustainability and compliance, and Asia-Pacific records rapid growth with smart port investments.
- Latin America and the Middle East & Africa show gradual adoption supported by expanding trade routes, port development projects, and international collaborations.
Market Drivers
Rising Global Maritime Trade and Expanding Port Infrastructure
The Vessel Traffic Management Market is strongly driven by the growth of international maritime trade. Expanding global shipping volumes increase demand for efficient vessel tracking and navigation systems. It supports ports and coastal authorities in managing dense traffic, reducing risks of congestion, and improving safety. Large-scale port infrastructure projects worldwide integrate vessel traffic management solutions to streamline operations. Governments prioritize maritime trade as a backbone of economic growth, creating consistent investments in advanced traffic control systems. It reinforces the role of vessel traffic management in enabling secure and efficient shipping lanes.
- For instance, Wärtsilä deployed its Navi-Harbour VTMS at Peru’s Port of Callao, which handles more than 70% of the nation’s import and export cargo, enhancing safety and vessel coordination across multiple terminals.
Growing Emphasis on Maritime Safety and Accident Prevention
The Vessel Traffic Management Market benefits from rising awareness about safety in maritime operations. High-profile accidents, oil spills, and collisions highlight the need for advanced monitoring systems. It provides real-time data on vessel movements, weather conditions, and navigational hazards to prevent mishaps. International regulations from the International Maritime Organization (IMO) and national authorities push operators to adopt vessel traffic systems. Coastal security agencies and port operators prioritize safety as part of broader risk management strategies. It strengthens the case for widespread adoption of these solutions.
- For instance, Transas, part of Wärtsilä, implemented a Vessel Traffic Management System for Kenya’s Port of Mombasa with control centers and sensor nodes at Ras Serani Station, Likoni Sector Light, and KPA headquarters to improve navigational safety and accident prevention.
Technological Advancements in Digital Navigation Systems
The Vessel Traffic Management Market gains momentum from continuous innovation in navigation and surveillance technologies. Integration of radar, Automatic Identification Systems (AIS), GPS, and satellite-based monitoring improves accuracy and coverage. It enables operators to manage complex traffic flows with real-time insights and predictive analytics. The use of AI and machine learning enhances decision-making and resource optimization. Digitalization of ports and adoption of smart technologies expand opportunities for intelligent vessel traffic solutions. It positions vessel traffic management as a central component of modern maritime infrastructure.
Government Investments and Regulatory Mandates in Maritime Operations
The Vessel Traffic Management Market grows through strong government initiatives and compliance requirements. Public sector agencies invest in coastal surveillance, smart ports, and traffic management infrastructure. It ensures safe navigation in both domestic and international waters. Regulatory frameworks mandate the adoption of vessel tracking systems in busy shipping routes and strategic trade corridors. Rising defense spending also supports deployment of advanced vessel traffic management systems to enhance national security. It aligns maritime modernization programs with long-term safety and sustainability goals.
Market Trends
Integration of Smart Port and Digital Maritime Solutions
The Vessel Traffic Management Market is witnessing strong adoption of smart port technologies. Ports worldwide are deploying digital traffic monitoring and predictive analytics to optimize vessel movement. It allows operators to reduce delays, manage congestion, and improve fuel efficiency. Integration with port community systems supports data exchange among stakeholders, ensuring seamless logistics. Smart port initiatives link vessel traffic management with broader digitalization goals. It positions advanced traffic systems as key enablers of efficient port ecosystems.
- For instance, Wärtsilä secured the prototyping contract for Singapore’s Next-Generation Vessel Traffic Management System (NGVTMS), designed to manage more than 1,000 vessel calls daily in one of the world’s busiest ports through advanced digital monitoring and predictive analytics.
Rising Adoption of AI and Machine Learning for Predictive Navigation
The Vessel Traffic Management Market benefits from rapid advances in artificial intelligence and machine learning. These technologies enhance real-time vessel tracking, anomaly detection, and route optimization. It helps reduce human error and improves response to dynamic maritime conditions. Predictive algorithms enable faster decision-making during peak traffic or emergencies. Maritime operators adopt AI-driven tools to improve safety compliance and operational planning. It reinforces vessel traffic management as a data-driven decision support system.
- For instance, ABB launched its Flexley Mover P603 autonomous mobile robot equipped with Visual SLAM and AI-driven positioning achieving ±5 mm accuracy, showcasing the same predictive navigation algorithms now being adapted into maritime traffic management for real-time route optimization.
Expansion of Satellite-Based and Remote Monitoring Capabilities
The Vessel Traffic Management Market is shaped by growing reliance on satellite-based systems for navigation. Satellite connectivity ensures vessel monitoring in remote waters and congested trade corridors. It improves global coverage where traditional radar or terrestrial systems face limitations. Remote monitoring solutions enhance visibility across international shipping lanes and Exclusive Economic Zones. Governments and defense agencies adopt these systems for improved maritime domain awareness. It highlights satellite integration as a core trend in traffic management.
Emphasis on Sustainability and Emission Reduction in Shipping
The Vessel Traffic Management Market aligns with global sustainability and decarbonization goals. Efficient vessel traffic solutions help reduce fuel consumption and greenhouse gas emissions. It supports compliance with International Maritime Organization (IMO) emission targets. Ports are adopting green traffic management systems that optimize docking schedules and minimize idle time. Maritime operators view these systems as tools to achieve environmental and operational efficiency. It underscores the trend of linking vessel traffic systems with sustainable shipping practices.
Market Challenges Analysis
High Implementation Costs and Infrastructure Constraints
The Vessel Traffic Management Market faces challenges from the high capital investment required for advanced systems. Modern solutions integrating radar, AIS, satellite, and analytics demand significant infrastructure upgrades. It creates barriers for small ports and developing regions with limited budgets. Maintenance and training costs further add to the financial burden. Integration with legacy port systems can be complex and time-consuming, slowing deployment. It restricts faster adoption in regions where port modernization is still at an early stage.
Operational Limitations and Regulatory Inconsistencies
The Vessel Traffic Management Market also struggles with operational limitations linked to environmental and regulatory challenges. Systems may underperform in extreme weather or congested waterways with heavy vessel density. It increases reliance on human intervention, reducing efficiency gains from automation. Regulatory frameworks vary across regions, creating uncertainty for global shipping operators. Lack of uniform standards complicates cross-border adoption of advanced vessel management practices. It highlights the need for international collaboration to ensure smoother implementation and reliable outcomes.
Market Opportunities
Expansion of Smart Ports and Global Trade Networks
The Vessel Traffic Management Market presents strong opportunities through the expansion of smart ports and rising global trade volumes. Governments and port authorities are investing in digital infrastructure to handle larger ships and higher traffic density. It enables efficient coordination of shipping schedules, reduces port congestion, and improves turnaround times. The growth of international trade routes across Asia-Pacific, Europe, and the Middle East strengthens adoption potential. Ports modernizing their facilities seek advanced traffic management to stay competitive. It creates sustained demand for solutions that enhance efficiency and global connectivity.
Integration of Emerging Technologies and Green Shipping Initiatives
The Vessel Traffic Management Market also benefits from opportunities linked to new technologies and environmental regulations. Artificial intelligence, IoT, and blockchain integration allow advanced analytics, predictive navigation, and secure data sharing. It enhances decision-making for both commercial and defense applications. Increasing focus on green shipping and emission reduction creates prospects for eco-friendly vessel management systems. Smart scheduling and fuel optimization features align with International Maritime Organization goals. It positions advanced traffic management solutions as central to achieving sustainability and digital transformation in maritime operations.
Market Segmentation Analysis:
By System Type
The Vessel Traffic Management Market by system type is divided into port management systems, coastal surveillance systems, and others. Port management systems hold a strong share, driven by rising adoption in busy commercial ports to optimize vessel traffic flow and reduce congestion. It ensures safer docking, faster turnaround, and improved resource utilization. Coastal surveillance systems are gaining importance as governments invest in maritime safety, border security, and anti-smuggling operations. Integration of radar, AIS, and satellite technology supports continuous monitoring in national waters. It highlights how system types serve both commercial efficiency and national security objectives.
- For instance, Transas, part of Wärtsilä, deployed a Vessel Traffic Management System at Kenya’s Port of Mombasa, installing nodes at Ras Serani Station, Likoni Sector Light, and KPA headquarters to oversee traffic movements across a coastline handling over 1,700 vessel calls annually.
By Component
The Vessel Traffic Management Market by component includes hardware, software, and services. Hardware such as radar, communication devices, and AIS transponders form the backbone of vessel monitoring operations. It ensures reliable navigation and communication between ships and port authorities. Software solutions are expanding rapidly with demand for real-time data analytics, predictive modeling, and automation. These platforms integrate seamlessly with port operations and logistics systems, enabling smarter decision-making. Services, including maintenance, training, and system upgrades, contribute significantly to long-term operational reliability. It shows how each component plays a crucial role in delivering end-to-end traffic management solutions.
- For instance, Wärtsilä's Navi-Harbour 5 VTMS integrates data from sensors, including radars and AIS, offering 3D views to enhance situational awareness at busy ports. Services, including maintenance, training, and system upgrades, contribute significantly to long-term operational reliability. It shows how each component plays a crucial role in delivering end-to-end traffic management solutions
By End Use
The Vessel Traffic Management Market by end use is segmented into commercial and defense applications. Commercial adoption dominates as global trade expands and port authorities seek greater efficiency in vessel handling. It provides operators with tools to manage increasing cargo volumes while ensuring compliance with safety standards. Defense end use is also growing, driven by the need for enhanced coastal monitoring, naval operations, and maritime domain awareness. Advanced traffic management systems strengthen national security by detecting unauthorized vessel movements. It demonstrates how the market supports both civilian and defense objectives with tailored solutions for each sector.
Segments:
Based on System Type
- Vessel traffic services (VTS)
- Port management systems (PMS)
- Automatic identification system (AIS)
- Radar-based systems
Based on Component
- Hardware
- Software
- Services
Based on End Use
- Marine authorities
- Ports and harbours
- Commercial vessel operators
- Naval forces
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America accounts for a 32% share of the Vessel Traffic Management Market, supported by advanced port infrastructure and strong adoption of maritime technologies. The United States leads the region with significant investments in modernizing coastal surveillance and traffic management systems. It benefits from the presence of high-traffic ports such as Los Angeles, New York, and Houston, which require advanced systems for safety and efficiency. Canada contributes through development of smart port initiatives and strengthening Arctic navigation safety. Mexico expands adoption with investments in oil and gas terminals and container ports. Rising focus on enhancing maritime domain awareness for security and trade efficiency ensures steady demand. It positions North America as a leader in technological innovation and operational adoption.
Europe
Europe holds a 28% share of the Vessel Traffic Management Market, driven by busy shipping routes and strong regulatory frameworks. Countries such as Germany, the UK, France, and the Netherlands invest heavily in traffic management solutions to support their global trade hubs. It benefits from the European Union’s emphasis on maritime safety and environmental compliance, which encourages digitalization of ports. Advanced radar, AIS, and satellite-based traffic systems are deployed across key commercial routes in the North Sea, Baltic Sea, and Mediterranean. Growing adoption of green port strategies also aligns vessel traffic management with broader sustainability goals. The region remains a strong market with its focus on safety, automation, and environmental responsibility.
Asia-Pacific
Asia-Pacific commands a 26% share of the Vessel Traffic Management Market, making it one of the fastest-growing regions. China leads adoption through massive investments in port expansions and smart logistics hubs. It also focuses on securing high-traffic maritime routes in the South China Sea. Japan and South Korea advance adoption with highly automated ports, supporting trade, defense, and industrial shipping. India shows strong growth, driven by modernization projects across major ports under government-led maritime development programs. Rising container traffic, coupled with growing naval operations, accelerates demand across the region. It highlights Asia-Pacific as a dynamic and high-potential market with diverse commercial and defense applications.
Latin America
Latin America contributes a 7% share of the Vessel Traffic Management Market, supported by modernization of ports and growing maritime trade. Brazil drives adoption with its large shipping terminals serving agriculture and energy exports. Mexico and Chile also invest in upgrading vessel monitoring systems to strengthen operational safety. Expanding oil and gas trade routes further stimulate adoption of traffic management solutions. Limited budgets and slower technology adoption in smaller ports act as constraints, but regional modernization initiatives offer opportunities. It reflects a growing market where international partnerships and government programs are key enablers.
Middle East & Africa
The Middle East & Africa account for a 7% share of the Vessel Traffic Management Market, supported by strong investments in maritime security and port development. Gulf countries such as Saudi Arabia and the UAE lead adoption, integrating vessel traffic management with global trade hubs and oil export facilities. It benefits from rising container traffic through ports like Jebel Ali and King Abdullah Port. Africa, led by South Africa and Nigeria, adopts vessel traffic systems to support growing energy exports and regional trade. Limited infrastructure and funding challenges slow widespread adoption, but international collaborations support growth. It positions the region as an emerging market with long-term opportunities tied to global shipping and energy exports.
Key Player Analysis
- IBM Corporation
- Navantia
- Hexagon AB
- Transas
- Indra Sistemas
- MarineTraffic
- Wärtsilä Corporation
- Thales Group
- SRT Marine Systems
- Saab AB
Competitive Analysis
The competitive landscape of the Vessel Traffic Management Market features leading players such as Wärtsilä Corporation, Thales Group, Saab AB, Transas, Navantia, Indra Sistemas, IBM Corporation, SRT Marine Systems, Hexagon AB, and MarineTraffic. These companies focus on expanding their portfolios by integrating advanced radar, AIS, satellite communication, and real-time data analytics to enhance maritime safety and efficiency. They invest heavily in automation, artificial intelligence, and cloud-based platforms to deliver scalable solutions for ports, coastal surveillance, and offshore operations. Strategic collaborations with governments, naval authorities, and port operators strengthen their market presence while ensuring compliance with global maritime regulations. Innovation in smart port infrastructure and digital monitoring technologies drives competition, as players aim to provide end-to-end solutions that optimize vessel routing, reduce congestion, and improve environmental compliance. With rising demand for secure and efficient maritime operations, these companies emphasize technological leadership, regional expansion, and long-term service contracts to maintain a strong competitive edge.
Recent Developments
- In August 2025, Navantia signed a contract with the Royal Thai Navy to modernize two Pattani-class Offshore Patrol Vessels (OPVs), integrating advanced combat management and surveillance systems to enhance rapid response and operational capacity, each designed for maritime traffic surveillance, search and rescue, and supporting multiple vessel control tasks.
- In February 2025, Indra Sistemas launched the SMAUG RDI project, bringing together entities from seven European countries to collaborate on underwater threat detection using their iSIM system.
- In September 2024, Wärtsilä Corporation secured the prototyping contract for Singapore’s Next‑Generation Vessel Traffic Management System (NGVTMS) project awarded by the Maritime and Port Authority of Singapore (MPA).
Report Coverage
The research report offers an in-depth analysis based on System Type, Component, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand with rising demand for safe and efficient maritime operations.
- Ports will adopt advanced vessel traffic solutions to improve real-time navigation management.
- Artificial intelligence and automation will enhance decision-making in traffic monitoring systems.
- Cloud-based platforms will gain traction for scalable and cost-effective maritime solutions.
- Integration of satellite and AIS technologies will strengthen surveillance and tracking capabilities.
- Smart port development will drive adoption of digital vessel traffic management systems.
- Naval and defense applications will expand through modernization of coastal security systems.
- Emerging economies will invest in advanced maritime infrastructure to support trade growth.
- Cybersecurity solutions will become critical to safeguard connected vessel traffic platforms.
- Strategic partnerships will shape innovation and global expansion of leading market players.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Vessel Traffic Management, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Vessel Traffic Management market projected to grow between 2025 and 2032?
Which Vessel Traffic Management market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Vessel Traffic Management market?
Who are the leading companies in the Vessel Traffic Management market?
Which region commanded the largest share of the Vessel Traffic Management market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Vessel Traffic Management Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Vessel Traffic Management Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 6.09 billion → 2032: USD 11.78 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Vessel Traffic Management Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Vessel Traffic Management Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Vessel Traffic Management Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Vessel Traffic Management Market Drivers
- 3.3 Vessel Traffic Management Market Restraints & Challenges
- 3.4 Vessel Traffic Management Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Vessel Traffic Management Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Vessel Traffic Management Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Vessel Traffic Management category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Vessel Traffic Management Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Vessel Traffic Management Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Vessel Traffic Management market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Vessel Traffic Management Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Vessel Traffic Management Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Vessel Traffic Management Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Vessel Traffic Management (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Vessel Traffic Management Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Vessel Traffic Management Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Vessel Traffic Management Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Vessel Traffic Management Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Vessel Traffic Management Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Vessel Traffic Management Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Vessel Traffic Management Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Vessel Traffic Management Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Vessel Traffic Management Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
