
Market Overview
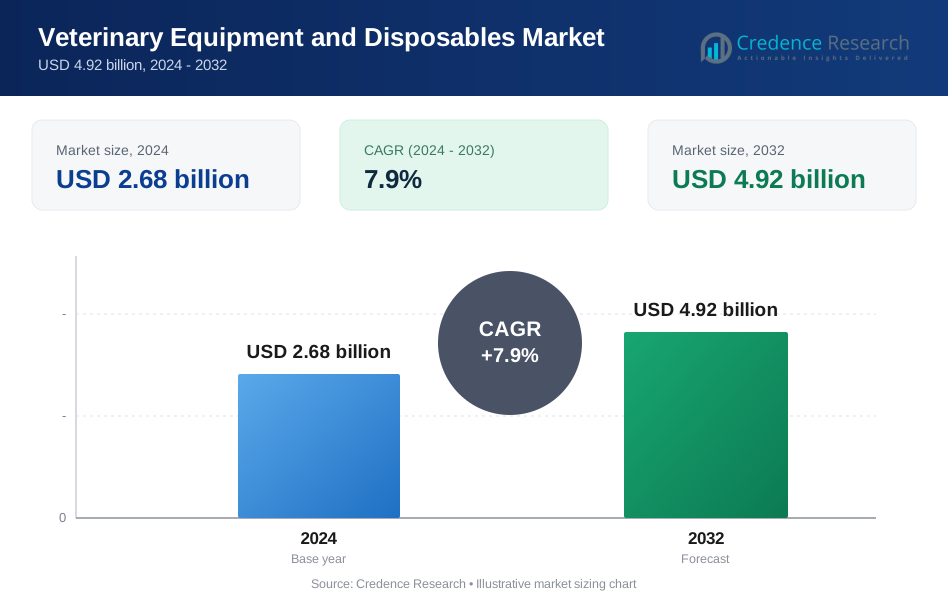
The veterinary equipment and disposables market was valued at USD 2.68 billion in 2024 and is projected to reach USD 4.92 billion by 2032, expanding at a CAGR of 7.9% over the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Veterinary Equipment And Disposables Market Size 2024 | USD 2.68 Billion |
| Veterinary Equipment And Disposables Market, CAGR | 7.9% |
| Veterinary Equipment And Disposables Market Size 2032 | USD 4.92 Billion |
The veterinary equipment and disposables market is driven by strong competition among leading players such as Midmark Corporation, Medtronic, Henry Schein, Inc., 3M, B. Braun Melsungen AG, Smiths Group plc, Shenzhen Mindray Bio-Medical Electronics Co., Jorgensen Labs, and DRE Veterinary. These companies strengthen their market presence through advancements in anesthesia delivery, monitoring systems, surgical consumables, and fluid therapy equipment tailored for both companion and livestock care. North America leads the global market with approximately 38% share, supported by advanced veterinary infrastructure and high treatment adoption rates, while Europe follows with around 30%, driven by stringent clinical standards and strong preventive animal healthcare programs.
Market Insights
- The veterinary equipment and disposables market was valued at USD 2.68 billion in 2024 and is projected to reach USD 4.92 billion by 2032, growing at a CAGR of 7.9% during the forecast period.
- Rising companion animal adoption and higher surgical procedure volumes drive demand for anesthesia systems, critical-care consumables, and monitoring equipment, with the companion animal segment holding the dominant share due to higher care utilization.
- Key trends include increasing adoption of portable monitoring devices, digital anesthesia systems, and single-use consumables that enhance infection control and operational efficiency in clinics and hospitals.
- Competition intensifies as major players such as Midmark Corporation, Medtronic, Henry Schein, 3M, B. Braun, and Mindray expand product portfolios while smaller manufacturers gain traction with cost-efficient disposable offerings; however, high equipment costs restrain adoption in small clinics.
- Regionally, North America leads with ~38%, followed by Europe at ~30% and Asia-Pacific at ~22%, supported by rapid clinic expansion and rising pet healthcare spending.
Market Segmentation Analysis:
By Animal Type
The companion animal segment dominates the veterinary equipment and disposables market with the largest market share, driven by rising pet ownership, higher expenditure on preventive and critical care, and greater adoption of advanced diagnostic and surgical tools in small-animal clinics. Increased prevalence of chronic diseases such as osteoarthritis, cardiac disorders, and diabetes in dogs and cats further fuels demand for anesthesia systems, fluid therapy sets, and monitoring consumables. Livestock applications continue to grow steadily due to herd health management programs and greater emphasis on productivity, but companion animals remain the primary revenue contributor due to higher care intensity and frequency of clinical interventions.
- For instance, Midmark’s 12.1-inch multiparameter veterinary monitor supports ECG, SpO₂, CO₂, and dual-channel temperature tracking, while incorporating species-specific NIBP algorithms for dogs and cats, enabling precise monitoring during orthopedic or cardiology procedures.
By Product Type
Critical care consumables represent the dominant product segment, holding the highest share owing to their essential role in routine procedures, surgical interventions, emergency care, and postoperative monitoring. High-volume demand for items such as wound care products, fluid therapy consumables, diagnostic disposables, and airway management components strengthens this segment’s leadership. Anesthesia and fluid management equipment follow as major contributors, supported by increasing surgical case volumes and advancements in precision monitoring. Temperature management and resuscitation equipment gain momentum as clinics upgrade standards for perioperative safety. The broad demand base and frequent replacement cycles of critical care consumables ensure sustained segment expansion.
- For instance, 3M’s VetBond™ tissue adhesive polymerizes in 10–20 seconds, enabling rapid closure of minor wounds and surgical incisions, while B. Braun’s Intrafix® SafeSet IV administration set delivers controlled infusion with a 15-micron fluid filter that maintains sterility during small-animal procedures.
By End-user
Veterinary hospitals account for the largest share in end-user segmentation, driven by their higher patient inflow, broader service portfolio, and adoption of advanced equipment for critical care, anesthesia, and surgical procedures. Their ability to perform complex interventions including orthopedics, cardiology, and emergency care creates strong demand for consumables with higher turnover rates. Veterinary surgical centers form the second-largest segment, benefiting from the increasing shift toward specialized procedures and outpatient surgeries. However, hospitals retain dominance due to integrated diagnostic capabilities, inpatient care infrastructure, and continuous procurement cycles for high-use disposable products.

Key Growth Drivers
Rising Companion Animal Ownership and Higher Clinical Care Utilization
Growing global pet ownership continues to expand demand for veterinary equipment and disposables, especially in developed markets where owners increasingly seek advanced medical care for chronic, age-related, and emergency conditions. Clinics report rising case loads for orthopedic surgeries, dental procedures, fluid resuscitation, and anesthesia-supported interventions, creating consistent demand for monitoring consumables, wound care products, IV administration sets, and single-use surgical materials. Additionally, expanding pet insurance adoption improves affordability for advanced treatments, directly boosting usage of high-value consumables and diagnostic equipment. Increasing prevalence of lifestyle-related conditions such as obesity, diabetes, and cardiovascular disorders in pets further necessitates routine monitoring, fluid therapy, and anesthesia-based procedures. This growing clinical intervention intensity supports continuous equipment replacement cycles and accelerates demand for reliable, sterile disposable products.
- For instance, IDEXX’s Catalyst One chemistry analyzer processes up to 25 diagnostic tests in a single run and delivers results in about 8 minutes, which supports fast decision-making in clinics with growing caseloads.
Expansion of Veterinary Surgical Capacities and Emergency Care Infrastructure
The rapid upgrade of veterinary hospitals and specialty surgical centers significantly accelerates demand for life-support equipment and high-turnover consumables. Clinics increasingly invest in anesthesia workstations, multiparameter monitors, infusion pumps, oxygen therapy devices, and temperature management systems to meet rising surgical volumes and regulatory expectations for perioperative safety. Higher demand for minimally invasive surgeries orthopedics, soft-tissue repair, and oncology elevates usage of sterile disposables, electrosurgical consumables, and fluid therapy components. Emergency care expansion, especially in urban centers, amplifies the need for rapid-response equipment such as resuscitation kits, airway management devices, and shock stabilization consumables. Hospitals also integrate advanced sterilization and infection-control protocols, driving repeat demand for disposable tubing, catheters, syringes, and wound dressings. The shift toward 24/7 emergency care further reinforces consistent equipment utilization and consumable replenishment cycles.
- For instance, Midmark’s Matrx VME2 veterinary anesthesia machine is designed for small-animal inhalation anesthesia and supports oxygen flowmeter settings up to 4 L/min with vaporizers calibrated for agents such as isoflurane or sevoflurane. Mindray’s WATO EX-35 Vet anesthesia workstation provides integrated ventilation monitoring, including tidal-volume measurement across a 20–1500 mL range, which allows veterinarians to manage anesthesia for both small and large animals with precision.
Growth of Livestock Health Management and Preventive Veterinary Programs
Rising emphasis on herd productivity, disease surveillance, and preventive veterinary care strengthens demand for equipment and disposables across livestock farms. The emergence of structured vaccination programs, mastitis control strategies, metabolic disorder management, and reproductive monitoring increases clinical interventions requiring fluid therapy sets, diagnostic consumables, thermoregulation tools, and portable anesthesia devices for field procedures. Intensifying pressure to reduce antimicrobial usage encourages farms to adopt early diagnostic and supportive care solutions, boosting sales of consumables for hydration, airway management, and wound care. Expansion of commercial dairy and poultry operations also drives adoption of automated equipment for handling large animal volumes, enhancing demand for durable equipment and single-use accessories. The need for biosecurity, contamination prevention, and safe on-site medical interventions pushes steady procurement of sterile disposables that support rapid, hygienic veterinary procedures in farm environments.
Key Trends & Opportunities
Advancement of Portable, Digital, and Smart Veterinary Equipment
A major trend redefining the market is the adoption of portable, connected, and digitally enabled veterinary equipment that supports remote diagnostics, point-of-care intervention, and faster emergency response. Portable anesthesia machines, handheld monitors, compact fluid pumps, and digital otoscopes enable veterinarians to deliver hospital-grade care during home visits and field operations. Integration of Bluetooth-enabled sensors and cloud-based patient monitoring platforms creates opportunities for continuous vital tracking and data-driven decision-making, improving clinical outcomes. Digital thermoregulation systems, automated infusion devices, and smart fluid delivery tools enhance precision and operational efficiency while reducing human error. As tele-veterinary services expand, manufacturers offering mobile-compatible diagnostic disposables, rapid test cartridges, and sterile consumables stand to gain significant traction. The shift toward mobility and digital workflows presents strong opportunities for companies innovating compact, battery-efficient, and IoT-integrated equipment portfolios.
- For instance, Butterfly Network’s Butterfly iQ+ Vet handheld ultrasound system uses a single silicon-chip probe supporting up to 15 imaging modes and links wirelessly to mobile devices for real-time cloud storage and AI-assisted workflow tools.
Increasing Use of Disposable and Single-Use Devices for Infection Control
Growing awareness of infection control protocols in veterinary settings fuels the adoption of single-use devices across surgical, emergency, and routine care procedures. Clinics increasingly standardize disposable suction tubing, cannulas, IV sets, temperature probes, airway devices, and sterile wound dressings to minimize cross-contamination risks and comply with modern hygiene standards. Enhanced regulatory scrutiny around sterilization practices and growing concerns about zoonotic pathogen transmission further accelerate demand for sterile, ready-to-use consumables. This trend creates major opportunities for manufacturers offering eco-friendly biopolymer-based disposables, color-coded safety systems, and ergonomic single-use surgical items. With clinics optimizing workflow efficiency, disposables reduce sterilization time, lower reprocessing costs, and improve procedural consistency. This shift toward high-volume, single-use consumables positions the segment as a major growth avenue for suppliers specializing in sterile product innovation.
- For instance, 3M’s Steri-Drape™ veterinary surgical drapes use a polyethylene film with an adhesive aperture designed to maintain a sterile field and are available in barrier thicknesses up to 0.05 mm, while B. Braun’s Intrafix® SafeSet IV line incorporates a 15-micron fluid filter to prevent particle contamination during infusion.
Expansion of Specialty Veterinary Services and Advanced Therapeutics
The rise of veterinary specialties oncology, cardiology, neurology, orthopedics, and critical care creates new avenues for technology-intensive equipment and related disposables. Specialty centers increasingly adopt advanced anesthesia stations, critical-care ventilators, fluid warmers, and multi-parameter monitors, all of which require compatible consumables for safe operation. Growth in regenerative medicine, minimally invasive surgery, and advanced imaging further drives demand for precision disposables and procedure-specific kits. Opportunities emerge for suppliers offering custom surgical packs, advanced wound-care dressings, specialized airway management devices, and anesthesia accessories tailored for complex interventions. As pet owners pursue higher standards of clinical care, specialty treatment expansion becomes a significant catalyst for disposable product innovation and recurring consumable usage.
Key Challenges
High Capital Costs and Budget Constraints in Small and Mid-Sized Clinics
Despite rising demand, many small and medium veterinary clinics face substantial financial barriers when upgrading equipment or maintaining consistent disposable inventory levels. High upfront costs associated with anesthesia systems, monitoring devices, and fluid therapy equipment often limit adoption, particularly in developing regions where clinics operate with restricted budgets. Additionally, recurring expenses for consumables such as sterile tubing, IV administration sets, syringes, and surgical disposables strain operational finances for smaller practices. Unpredictable demand patterns, low patient volumes, and limited reimbursement mechanisms further constrain investment capability. These financial obstacles slow technology modernization, restrict scaling of surgical services, and challenge manufacturers aiming for broad adoption across fragmented clinic environments.
Limited Skilled Workforce and Variability in Clinical Standards
A shortage of trained veterinary professionals and technicians hinders optimal use of advanced equipment, particularly in emerging markets. Complex anesthesia machines, digital monitoring systems, and emergency care devices require specialized training, and insufficient staff proficiency can limit utilization and procedural safety. Variability in clinical standards across clinics also affects adoption of consistent disposables, infection control practices, and equipment maintenance routines. Inadequate training on sterilization, fluid management, and resuscitation devices increases operational risk and reduces equipment lifespan. These gaps challenge manufacturers to provide extensive training, user-friendly interfaces, and robust support systems. Workforce limitations remain a significant structural barrier to uniform equipment deployment and high-quality procedural execution.
Regional Analysis
North America
North America maintains the largest share of around 38%, supported by its advanced veterinary healthcare infrastructure, high companion animal adoption, and widespread availability of specialized surgical and diagnostic services. Strong penetration of pet insurance increases affordability for complex procedures, driving sustained demand for anesthesia devices, monitoring consumables, and surgical disposables. The region also benefits from well-regulated clinical standards and continuous investments by veterinary hospital chains in critical care and emergency equipment. The presence of major manufacturers and frequent product upgrades further strengthens North America’s leadership in the global market.
Europe
Europe holds approximately 30% of the market, propelled by robust veterinary service regulations, widespread preventive animal healthcare programs, and high spending on companion animal wellness. The region’s growing network of veterinary specialty centers accelerates adoption of advanced anesthesia, fluid therapy, and temperature-management systems. Strong livestock health monitoring programs, especially in Germany, France, and the U.K., reinforce demand for diagnostic consumables and portable care equipment. Favorable reimbursement structures in several countries and increased focus on infection control continue to support strong growth across both hospitals and specialized veterinary surgical clinics.
Asia-Pacific
Asia-Pacific accounts for nearly 22% of the market and represents the fastest-growing region due to rapid expansion of veterinary clinics, rising pet ownership in urban centers, and increasing investments in modern surgical and critical-care capabilities. Countries such as China, India, Japan, and Australia are witnessing sharp increases in small-animal caseloads, driving demand for anesthesia equipment, critical-care consumables, and fluid-management systems. Growing awareness of pet wellness and expanding livestock health management programs further contribute to market momentum. Increasing adoption of Western veterinary standards and the emergence of corporate hospital chains strengthen long-term growth prospects.
Latin America
Latin America captures about 6% of the market, supported by steady improvements in veterinary infrastructure and rising demand for advanced medical care for companion animals. Brazil, Mexico, and Argentina lead the region in the adoption of surgical equipment, fluid therapy devices, and infection-control consumables. Growth in livestock production, particularly in poultry and cattle, drives demand for diagnostic disposables and portable anesthesia units used during field procedures. However, budget constraints and uneven access to advanced veterinary facilities limit widespread adoption, though ongoing clinic modernization efforts continue to strengthen the regional market outlook.
Middle East & Africa
The Middle East & Africa region represents approximately 4% of the global market, driven by increasing investments in veterinary hospitals, rising pet ownership in urban hubs such as the UAE and Saudi Arabia, and expansion of livestock healthcare programs across Africa. Demand for critical-care consumables, diagnostic disposables, and anesthesia equipment continues to rise as clinics upgrade their service offerings. Growth remains concentrated in developed sub-regions with better clinical infrastructure, while rural markets face limited access to advanced technologies. Nevertheless, expanding government livestock immunization programs and private veterinary facility development support steady market growth.
Market Segmentations:
By Animal Type
- Companion Animal
- Livestock Animal
By Product Type
- Critical Care Consumables
- Anesthesia Equipment
- Fluid Management Equipment
- Temperature Management Equipment
- Rescue & Resuscitation Equipment
- Others
By End-user
- Veterinary Hospitals
- Veterinary Surgical Centers
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the veterinary equipment and disposables market is characterized by a mix of global manufacturers, specialized veterinary technology companies, and rapidly expanding regional suppliers focused on high-volume consumables. Leading players emphasize innovation in anesthesia delivery systems, multiparameter monitoring, fluid therapy devices, and critical care consumables to meet rising clinical standards across hospitals and specialty centers. Companies increasingly integrate digital monitoring, ergonomic designs, and improved sterilization compatibility into their product portfolios to align with modern veterinary workflows. Strategic expansions including mergers, product line upgrades, and distribution partnerships strengthen global presence and improve access to high-demand disposable products. Market leaders also invest in training programs, aftersales service networks, and bundled equipment–consumable offerings to enhance customer retention. Growing competition in single-use devices encourages continuous product differentiation, while regulatory compliance and quality certification remain decisive factors in shaping vendor competitiveness.
Key Player Analysis
- Midmark Corporation
- Smiths Group plc
- Medtronic
- Jorgensen Labs
- B. Braun Melsungen AG
- Henry Schein, Inc.
- Shenzhen Mindray Bio-Medical Electronics Co.
- 3M
- DRE Veterinary
Recent Developments
- In May 2025, Mindray received U.S. clearance (510(k)) for an “Ultrasonic Pulsed Doppler Imaging System” which broadens its imaging product offerings potentially usable in veterinary diagnostics.
- In October 2024, Mindray Animal Medical broke ground on a new “Animal Tech Park,” indicating a strategic long-term investment in veterinary R&D and manufacturing infrastructure.
- In February 2024, Midmark Corporation introduced a new line of multiparameter monitors designed for veterinary use. The new monitors feature integrated safety elements and a user-friendly interface to help veterinary teams manage anesthesia and critical-care procedures more efficiently.
Report Coverage
The research report offers an in-depth analysis based on Animal type, Product type, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for advanced anesthesia, monitoring, and critical-care systems will continue to rise as veterinary hospitals upgrade surgical and emergency care capabilities.
- Adoption of single-use and sterile disposables will accelerate due to stricter infection-control standards across clinics and specialty centers.
- Portable and digital veterinary devices will gain traction, supporting home-care services, field operations, and tele-veterinary workflows.
- Growth in companion animal surgeries will drive consistent consumption of high-turnover items such as fluid therapy sets, airway devices, and wound-care consumables.
- Veterinary hospitals will expand investments in integrated critical-care equipment as caseload complexity increases.
- Livestock health programs will strengthen demand for durable equipment and field-ready disposable products.
- Specialty services such as oncology, orthopedics, and cardiology will create opportunities for advanced consumables and procedure-specific kits.
- Manufacturers will prioritize ergonomic designs, user-friendly interfaces, and automation features to reduce clinical workload.
- Sustainability initiatives will encourage development of eco-friendly, recyclable, and biopolymer-based veterinary disposables.
- Market consolidation will increase as leading companies pursue acquisitions and distribution partnerships to expand global access.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Companion Animal Ownership and Higher Clinical Care Utilization
Increasing global pet ownership, especially in developed markets, is driving demand for advanced veterinary equipment and disposables as owners seek higher standards of care for chronic, age-related, and emergency conditions. This leads to greater utilization of anesthesia systems, monitoring consumables, and surgical disposables in clinics and hospitals.
Expansion of Veterinary Surgical Capacities and Emergency Care Infrastructure
Veterinary hospitals and specialty centers are upgrading their surgical and emergency care capabilities, investing in advanced anesthesia workstations, multiparameter monitors, and critical care consumables. This expansion supports higher surgical volumes and more complex interventions, fueling recurring demand for both equipment and disposables.
Growth of Livestock Health Management and Preventive Veterinary Programs
Structured herd health programs, disease surveillance, and preventive care initiatives in livestock farming are increasing the need for diagnostic consumables, fluid therapy sets, and portable anesthesia devices. The push for productivity and biosecurity in commercial operations further boosts demand for durable equipment and single-use accessories.
Advancement of Portable, Digital, and Smart Veterinary Equipment
The adoption of portable, digitally enabled veterinary devices is enabling remote diagnostics, point-of-care interventions, and tele-veterinary workflows. This trend is expanding the market for compact monitors, mobile anesthesia machines, and digital consumables that support both in-clinic and field-based care.
Increasing Use of Disposable and Single-Use Devices for Infection Control
Stricter infection control protocols and regulatory scrutiny are accelerating the shift toward single-use consumables in veterinary settings. Clinics are standardizing disposable tubing, IV sets, and wound dressings to minimize cross-contamination, driving sustained growth in the disposables segment.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Veterinary Equipment and Disposables market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Veterinary Equipment and Disposables market projected to grow between 2024 and 2032?
Which Veterinary Equipment and Disposables segment held the largest share in 2024?
What are the primary factors fueling growth in the Veterinary Equipment and Disposables market?
Who are the leading companies in the Veterinary Equipment and Disposables market?
Which region commanded the largest share of the Veterinary Equipment and Disposables market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-user
- 1.2.1 Veterinary Hospitals
- 1.2.2 Veterinary Surgical Centers
- 1.3 By Animal Type
- 1.3.1 Companion Animal
- 1.3.2 Livestock Animal
- 1.4 By Product Type
- 1.4.1 Critical Care Consumables
- 1.4.2 Anesthesia Equipment
- 1.4.3 Fluid Management Equipment
- 1.4.4 Temperature Management Equipment
- 1.4.5 Rescue & Resuscitation Equipment
- 1.4.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2.68 billion → 2032: USD 4.92 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Veterinary Equipment and Disposables Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Veterinary Equipment and Disposables Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Veterinary Equipment and Disposables Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Veterinary Equipment and Disposables Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Veterinary Equipment and Disposables Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Veterinary Equipment and Disposables Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Veterinary Equipment and Disposables Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Veterinary Equipment and Disposables Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2.68 billion → 2032: USD 4.92 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Veterinary Equipment and Disposables Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-user - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Veterinary Hospitals
- 12.3.7.2 Veterinary Surgical Centers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Animal Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Companion Animal
- 12.4.7.2 Livestock Animal
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Critical Care Consumables
- 12.5.7.2 Anesthesia Equipment
- 12.5.7.3 Fluid Management Equipment
- 12.5.7.4 Temperature Management Equipment
- 12.5.7.5 Rescue & Resuscitation Equipment
- 12.5.7.6 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Veterinary Equipment and Disposables End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Veterinary Equipment and Disposables Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Veterinary Equipment and Disposables Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Veterinary Equipment and Disposables Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Midmark Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Medtronic
- 18.4 Henry Schein, Inc.
- 18.5 3M
- 18.6 B. Braun Melsungen AG
- 18.7 Smiths Group plc
- 18.8 Shenzhen Mindray Bio-Medical Electronics Co.
- 18.9 Jorgensen Labs
- 18.10 DRE Veterinary
- 18.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

