
Market Overview:
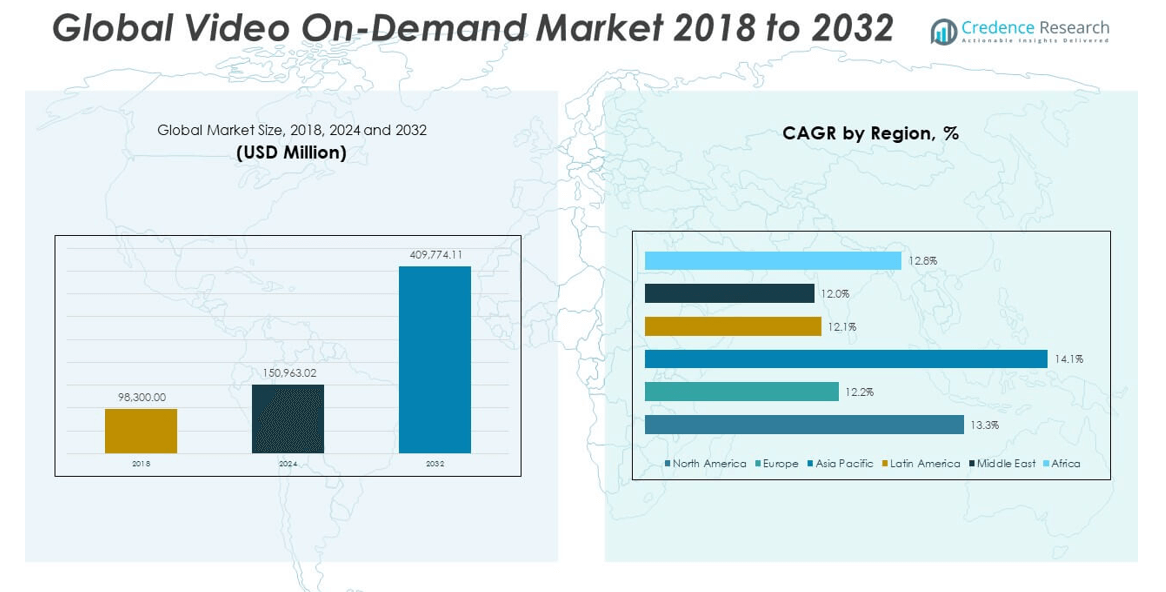
The Video On-Demand Market size was valued at USD 98,300.00 million in 2018 to USD 150,963.02 million in 2024 and is anticipated to reach USD 409,774.11 million by 2032, at a CAGR of 13.36% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Video On-Demand Market Size 2024 | USD 150,963.02 million |
| Video On-Demand Market, CAGR | 13.36% |
| Video On-Demand Market Size 2032 | USD 409,774.11 million |
The market is being driven by increasing consumer preference for personalized content, rising broadband penetration, and the proliferation of smart devices globally. The shift from traditional cable to internet-based streaming services has gained momentum, fueled by original content creation, user-friendly interfaces, and flexible subscription models. Moreover, the surge in mobile viewing, coupled with advancements in cloud-based content delivery and AI-driven recommendation engines, continues to enhance user engagement, making video on-demand platforms a dominant force in the media and entertainment industry.
Regionally, North America leads the market due to widespread digital infrastructure, high consumer spending, and strong presence of key streaming providers. Europe follows with growing adoption across the UK, Germany, and France, driven by expanding OTT subscriptions. The Asia Pacific region is emerging as a high-growth market, supported by rising smartphone usage, affordable data plans, and increasing demand for regional and multilingual content in countries like India, China, and Southeast Asia. Meanwhile, Latin America and the Middle East are gradually advancing with improved internet access and strategic platform expansions
Market Insights:
- The Video On-Demand Market was valued at USD 98,300.00 million in 2018 and reached USD 150,963.02 million in 2024; it is projected to hit USD 409,774.11 million by 2032, growing at a CAGR of 13.36%.
- Increasing demand for personalized content, real-time access, and mobile streaming continues to drive platform adoption globally.
- High content licensing costs and market saturation create entry barriers and challenge profitability for emerging players.
- North America leads the market share due to robust digital infrastructure and the dominance of key players like Netflix and Amazon.
- Asia Pacific shows the fastest growth due to mobile-first usage, regional content creation, and expanding internet access.
- Europe maintains steady momentum with strong OTT penetration and regulatory support for local content production.
- Latin America, the Middle East, and Africa witness gradual adoption supported by affordable data plans and regional platform investments.
Market Drivers:
Surging Internet Penetration and Digital Infrastructure Fueling Consumer Reach
The rapid expansion of high-speed internet services and the growing affordability of smartphones have significantly broadened access to the Video On-Demand Market. Households in both developed and developing regions now stream content without traditional broadcast delays. Faster mobile networks and widespread Wi-Fi availability enable uninterrupted viewing experiences. Consumers can engage with platforms anytime, enhancing convenience. Telecommunication advancements continue to extend digital coverage to remote areas. Government initiatives promoting digital inclusion strengthen this trajectory. It benefits from rising data consumption per user. The market capitalizes on this foundation to scale viewership and engagement across geographies.
- For example, the Disney+ app saw approximately 8.1 million downloads in the U.S. in the first half of 2024, making it the top Disney-owned mobile product. In Q3 2024 alone, it received almost 4.5 million U.S. downloads, reflecting rapid mobile adoption.
Shift from Linear TV to Personalized Viewing Experiences Enhancing User Retention
Consumer preferences have decisively moved away from linear television toward customized, on-demand experiences. Platforms that allow users to choose what, when, and how they watch are gaining sustained traction. Personalized recommendation engines based on AI and user data analytics increase viewing hours. Binge-watching features and curated content libraries cater to user behavior patterns. It leverages this trend to improve stickiness and reduce churn. Traditional broadcasting models struggle to maintain user loyalty. Subscription-based and freemium models offer flexibility unmatched by cable systems. This behavioral shift propels continuous demand and platform expansion.
Original and Exclusive Content Investment Accelerating Platform Differentiation
Content creators and platforms increasingly invest in original series, films, and documentaries to differentiate their offerings. Viewers seek fresh and diverse narratives unavailable on traditional TV or rival services. Exclusive rights to blockbuster content or celebrity-led productions attract large audiences. The Video On-Demand Market uses such strategies to build brand loyalty and expand subscriber bases. Localized storytelling also gains traction, appealing to regional audiences. High-budget productions, combined with compelling scripts, drive higher user acquisition. It creates a competitive edge that fuels rapid platform growth. This model sustains consumer interest and repeat engagement.
- For example, Netflix’s CFO confirmed 2025 cash content spending of approximately $18 billion, up from $16.2 billion in 2024, reflecting an 11% YoY increase and ongoing commitment to global originals.
Technological Advancements in AI, UX, and Cloud Infrastructure Supporting Scalability
The integration of AI for content curation and search optimization improves user satisfaction. Seamless interfaces, voice control, and cross-device access enhance platform usability. It relies on scalable cloud infrastructure for content delivery, storage, and real-time performance. Technologies like adaptive streaming adjust video quality based on bandwidth. Real-time analytics help platforms respond swiftly to user behavior. Innovations in data compression reduce buffering and load times. These enhancements support expansion without compromising experience. The Video On-Demand Market continues to benefit from evolving tech ecosystems that optimize service delivery.
Market Trends:
Growing Adoption of Hybrid Monetization Models Expanding Revenue Streams
Streaming services are increasingly embracing hybrid models combining subscriptions, advertising, and transactional payments. This shift reflects changing viewer attitudes toward flexible pricing. Ad-supported tiers attract cost-sensitive users without undermining value. Freemium structures introduce new users to premium content. It benefits from diversified income streams while maintaining broad accessibility. Brands leverage targeted ad insertions for precise audience engagement. Microtransactions for single-view content unlock pay-per-use revenue. Partnerships with advertisers help scale platform reach. The Video On-Demand Market aligns monetization with user segmentation to maximize returns.
- For example, Netflix officially reported in its Q1 2024 Letter to Shareholders that its ad-supported plan launched in November 2022 and, within 18 months, attracted 40 million global monthly active users. This is a directly disclosed, verifiable metric showing the rapid adoption of a hybrid.
Cross-Platform and Cross-Device Integration Improving Viewer Convenience
Consumers expect consistent viewing experiences across smart TVs, phones, tablets, and consoles. Developers optimize apps to function uniformly across operating systems and hardware. It adapts by deploying responsive designs and device-agnostic playback features. Synchronization between devices enhances multi-screen engagement. Cloud-based profiles retain preferences and watch histories seamlessly. Voice command and smart assistant integration improve navigation. Content casting and mirroring functions expand usage in shared environments. The Video On-Demand Market gains traction by enabling content mobility and uninterrupted access.
Increased Focus on Niche Content and Regional Language Programming
Platforms are expanding their libraries to include niche genres and regional content to reach underserved audiences. Language-specific shows, documentaries, and indie films appeal to cultural diversity. It leverages data analytics to identify content gaps and viewer interests. Collaborations with local creators strengthen authenticity. Niche genres like anime, true crime, and period dramas gain dedicated followings. Regional distribution deals help scale localized programming. Viewers find more personalized relevance in tailored offerings. The Video On-Demand Market grows by aligning content strategy with demographic diversity.
- For instance, Netflix’s 2024 Content Report notes that its investment in Korean content led to over 60% of all Netflix members worldwide watching at least one Korean title in 2023, with non-English language viewing hours growing by 35% year-over-year. This is an official, quantified example of niche/regional content driving global engagement.
Interactive and Gamified Content Elevating Viewer Engagement
Interactive storytelling and gamified content are emerging as key engagement tools. Platforms experiment with choose-your-own-adventure formats and real-time voting features. It fosters deeper immersion and emotional investment. Educational content adopts interactive quizzes and challenges to enhance learning retention. Gamification techniques reward viewing milestones and encourage participation. Social integration allows viewers to share outcomes or compete with friends. AR and VR elements enrich select formats. The Video On-Demand Market uses such innovations to convert passive viewers into active participants.
Market Challenges Analysis:
Intensifying Competition and Subscription Fatigue Limiting User Growth
The growing number of platforms offering similar content and pricing structures has saturated the market. Consumers face overwhelming choices, leading to selective subscriptions or cancellations. The Video On-Demand Market contends with fluctuating user loyalty as consumers trial multiple services. Original content investments create high entry barriers for new entrants. Smaller players struggle to gain visibility amid major brand campaigns. Pricing wars compress profit margins and complicate differentiation. User fatigue from managing multiple logins and billing cycles dampens engagement. It must constantly innovate to maintain a competitive edge in this fragmented landscape.
Licensing Restrictions and Content Fragmentation Hindering Global Scalability
Licensing challenges restrict the availability of popular titles across regions, creating uneven user experiences. Content fragmentation forces users to subscribe to multiple platforms for full access. It faces difficulties securing global rights due to complex negotiations and distribution deals. Regional censorship laws and content regulations impose further hurdles. Delayed releases or geoblocked content frustrate international viewers. Diverse legal frameworks complicate consistent content rollout. These constraints slow global subscriber growth and limit content discovery. The Video On-Demand Market needs agile strategies to navigate licensing variability.
Market Opportunities:
Expanding in Untapped Rural and Semi-Urban Markets with Affordable Models
Rapid digitalization of rural and tier-2 regions presents a large opportunity for subscriber expansion. Affordable smartphones and low-cost data plans widen access. The Video On-Demand Market can offer budget-friendly tiers with regional content to penetrate these segments. Collaborations with telecom providers help distribute bundled plans. Offline viewing features cater to areas with inconsistent connectivity. Local influencer campaigns build trust and brand awareness. It has the potential to unlock a vast new audience base through rural digital inclusion.
Partnerships with Telecom and Smart Device Manufacturers Enhancing Distribution
Forming alliances with mobile operators and smart TV brands enables direct platform access. Bundling content with devices simplifies user onboarding. The Video On-Demand Market gains visibility through pre-installed apps and device promotions. Co-branded campaigns expand outreach. Telecom billing integration offers frictionless payments. These partnerships reduce acquisition costs and increase active users. It strengthens platform stickiness by embedding itself within user ecosystems.
Market Segmentation Analysis:
By Type
The Video On-Demand Market features multiple content delivery formats tailored to user preferences and infrastructure availability. Internet Protocol Television (IPTV) continues to attract subscribers through its bundled service offerings, especially in regions with high broadband penetration. Over-the-Top (OTT) platforms dominate this segment by providing direct-to-consumer access without intermediary operators. OTT's flexible content access, device compatibility, and rich original programming make it the fastest-growing type. Pay-TV maintains relevance in certain geographies but faces declining growth due to its rigid pricing and lack of on-demand flexibility. The traditional Video on Demand (VoD) model still supports transactional content rentals and purchases, particularly for newly released films. It benefits from audience segments seeking occasional premium content without long-term commitments.
- For example, platforms like Apple’s iTunes and Amazon Prime Video continue to offer TVOD (Transactional Video on Demand), where viewers pay to rent or own newly released films on a per-transaction basis-a preferred model for users seeking premium content without subscriptions.
By Application
The Video On-Demand Market spans diverse application areas beyond entertainment. Media & Entertainment leads the segment, supported by strong consumer demand for movies, TV series, and live events. Education & Training is gaining momentum through e-learning platforms that offer flexibility and repeatable content access. Health & Fitness applications have seen a rise in home-based workout content, guided sessions, and wellness tutorials. It supports growth in these verticals by offering scalable content libraries and real-time accessibility. The "Others" segment includes use cases like corporate training, religious streaming, and virtual events, which are also expanding with enterprise and community-level digital transformation.
By Content Type
The Video On-Demand Market accommodates a wide variety of content formats. TV Entertainment leads the segment with drama series, reality shows, and serial-based programming. Movies continue to drive high engagement, particularly through exclusive releases and cinematic franchises. Sports content maintains a strong following due to real-time streaming, highlights, and regional league coverage. Kids' content sees consistent demand, especially educational and animation-focused programming that supports parental control features. Music streaming expands with concert recordings, karaoke platforms, and genre-based playlists. The "Others" category includes documentaries, news, and niche storytelling, contributing to the platform's content depth. It gains traction by tailoring offerings to diverse viewer interests.
By Device
The Video On-Demand Market thrives across multiple digital devices, with smartphones leading user engagement due to their portability and high data accessibility. Smart TVs offer large-screen experiences and dominate in-home viewing, especially in developed economies. Laptops serve a dual purpose for entertainment and education, providing mobility with advanced display resolution. Tablets appeal to younger viewers and e-learners through touchscreen interactivity. The "Others" category includes gaming consoles, streaming sticks, and desktop computers. It maintains device-agnostic compatibility to ensure seamless content delivery and user flexibility across digital ecosystems.
By Revenue Model
The Video On-Demand Market operates under diverse monetization structures to cater to varying consumer segments. Subscription Video on Demand (SVoD) leads this space, offering unlimited access to content for a recurring fee. Transactional Video on Demand (TVoD) serves users seeking pay-per-view content, especially new movie releases and special events. Advertisement-Based Video on Demand (AVoD) grows steadily with cost-sensitive users preferring free access in exchange for targeted ads. Hybrid models blend subscriptions and advertising to offer customized plans and broaden market reach. It adapts to evolving consumer behavior by aligning revenue strategies with affordability and content value.
- For example, platforms like Amazon Prime Video and Apple’s iTunes serve users preferring one-off rentals or purchases, especially for new releases and exclusive events.
Segmentation:
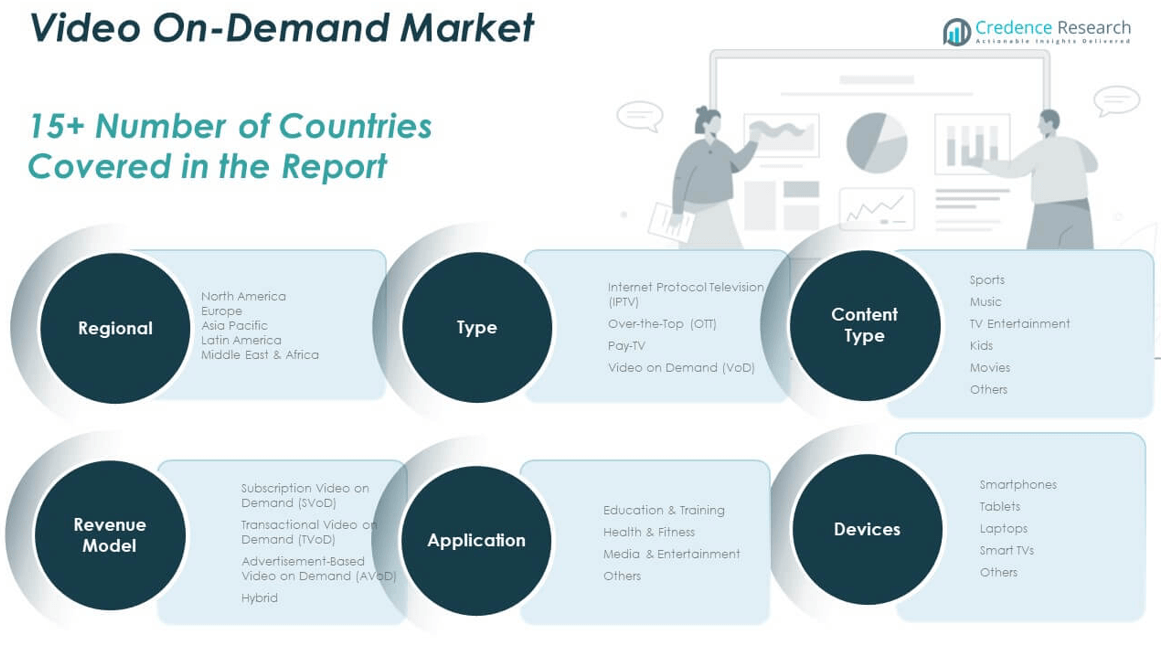
By Type
- Internet Protocol Television (IPTV)
- Over-the-Top (OTT)
- Pay-TV
- Video on Demand (VoD)
By Application
- Education & Training
- Health & Fitness
- Media & Entertainment
- Others
By Content Type
- Sports
- Music
- TV Entertainment
- Kids
- Movies
- Others
By Device
- Smartphones
- Tablets
- Laptops
- Smart TVs
- Others
By Revenue Model
- Subscription Video on Demand (SVoD)
- Transactional Video on Demand (TVoD)
- Advertisement-Based Video on Demand (AVoD)
- Hybrid
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Video On-Demand Market size was valued at USD 24,083.50 million in 2018 to USD 36,320.80 million in 2024 and is anticipated to reach USD 98,095.83 million by 2032, at a CAGR of 13.3% during the forecast period. North America holds a 24.07% share of the global market, driven by strong digital infrastructure and a mature streaming ecosystem. It benefits from widespread broadband penetration and high smart device adoption. Major players like Netflix, Amazon Prime Video, and Disney+ maintain dominant positions through original content and bundled services. High consumer willingness to pay for premium subscriptions contributes to market strength. Strong entertainment production capabilities in the U.S. boost the availability of exclusive content. User personalization and AI integration further enhance viewer engagement. Regulatory flexibility also enables rapid content rollout and innovation.
Europe
The Europe Video On-Demand Market size was valued at USD 18,441.08 million in 2018 to USD 26,776.71 million in 2024 and is anticipated to reach USD 66,937.69 million by 2032, at a CAGR of 12.2% during the forecast period. Europe accounts for 16.34% of the global market, led by the UK, Germany, and France. It demonstrates strong demand for localized content and multilingual programming. Regional players collaborate with telecom providers to broaden distribution. Regulatory frameworks like the EU’s Audiovisual Media Services Directive encourage investment in regional production. Hybrid monetization models are gaining traction among cost-sensitive users. Rising smart TV penetration supports platform accessibility. European users favor curated content experiences with advanced parental controls. Content diversity and digital rights compliance shape regional platform strategies.
Asia Pacific
The Asia Pacific Video On-Demand Market size was valued at USD 44,431.60 million in 2018 to USD 69,872.60 million in 2024 and is anticipated to reach USD 199,526.72 million by 2032, at a CAGR of 14.1% during the forecast period. Asia Pacific represents the largest regional share at 48.69%, propelled by expanding internet access and mobile-first consumption. It thrives on the rising demand for regional language content and affordable subscription plans. Countries like India, China, and Indonesia exhibit exponential user growth. Local platforms compete with global players through hyperlocal content strategies. Smartphone proliferation and declining data costs support continuous streaming activity. Short-form content and mobile-optimized apps appeal to younger demographics. Collaborations with telecom companies drive bundled offerings. Market growth is also aided by rapid digital payment adoption and urbanization.
Latin America
The Latin America Video On-Demand Market size was valued at USD 5,013.30 million in 2018 to USD 7,607.03 million in 2024 and is anticipated to reach USD 18,796.33 million by 2032, at a CAGR of 12.1% during the forecast period. Latin America holds a 4.59% market share, with Brazil and Mexico leading platform adoption. It gains momentum through improved internet infrastructure and expanding smartphone usage. Local content partnerships are essential to regional success. Economic diversity across countries influences pricing strategies. Ad-supported models are gaining preference among users in price-sensitive segments. It faces challenges from content piracy and regulatory inconsistencies. Consumer interest in telenovelas and sports content supports high engagement levels. Payment flexibility and mobile billing integrations help convert free users to paid subscribers.
Middle East
The Middle East Video On-Demand Market size was valued at USD 3,912.34 million in 2018 to USD 5,645.04 million in 2024 and is anticipated to reach USD 13,893.60 million by 2032, at a CAGR of 12.0% during the forecast period. Middle East accounts for 3.39% of the global market and shows steady growth driven by urban digital transformation. It benefits from strong mobile penetration and increasing demand for Arabic-language content. Gulf countries are early adopters due to higher disposable incomes. Content regulation influences platform content libraries and release schedules. Subscription models gain traction in metro areas, while free ad-supported models appeal to broader audiences. It experiences rising demand for religious, educational, and lifestyle-based content. Regional players like Shahid and StarzPlay drive competition. Investments in fiber networks support HD streaming capabilities.
Africa
The Africa Video On-Demand Market size was valued at USD 2,418.18 million in 2018 to USD 4,740.85 million in 2024 and is anticipated to reach USD 12,523.95 million by 2032, at a CAGR of 12.8% during the forecast period. Africa holds a 3.06% market share, with South Africa, Nigeria, and Kenya leading digital adoption. It sees rapid mobile-driven growth despite infrastructural limitations. Affordable smartphone access and data partnerships stimulate user acquisition. The market responds well to regional content and dubbed international series. Telecom bundling and prepaid models support reach in underbanked populations. It faces bandwidth and electricity access challenges in rural areas. Local creators contribute to increasing original African content. Government digital inclusion efforts continue to support expansion potential.
Key Player Analysis:
- Netflix, Inc. (USA)
- com, Inc. (USA)
- Hulu LLC (USA)
- Apple, Inc. (USA)
- Google LLC (USA)
- Comcast Corporation (USA)
- Facebook, Inc. (USA)
- AT&T, Inc. (USA)
- The Walt Disney Company (USA)
- Verizon Communications Inc. (USA)
- Sony Corporation (Japan)
- Rakuten, Inc. (Japan)
- Tencent Holdings Ltd. (China)
- iQIYI, Inc. (China)
- Alibaba Group Holding Limited (China)
- Telefonaktiebolaget LM Ericsson (Sweden)
- Deutsche Telekom AG (Germany)
- Vivendi SE (France)
- Sky Group (UK)
- BBC iPlayer (UK)
Competitive Analysis:
Leading players within the Video On-Demand Market, such as Netflix, Amazon Prime Video, and Disney+, compete fiercely on content quality, platform experience, and global reach. They differentiate through blockbuster originals, exclusive franchise rights, and strategic acquisitions. It leverages user data to refine recommendations and drive engagement. Companies optimize campaigns to capture share in emerging regions while maintaining subscription growth in mature markets. Smaller platforms focus on niche audiences and local content to carve out presence. Technology firms integrate it within bundled services to improve stickiness. Challenges include balancing high content costs with subscriber retention. Competition heats around global expansion, platform innovation, and synergies with telecom partners to gain sustainable advantage.
Recent Developments:
- In June 2025, Netflix announced a partnership with NASA to bring live space programming-including rocket launches and spacewalks-to its global audience. This represents an expansion of Netflix’s live streaming content, a key evolution for its VOD offerings.
- In June 2025, Disney completed its acquisition of Comcast/NBCUniversal’s remaining 33% stake in Hulu, paying approximately $438.7 million. That final payment follows an earlier $8.6 billion that Disney had already paid, closing a valuation and arbitration process that began after Comcast exercised its sale option.
- In March 2025, Google’s acquisition of Wiz, a cloud security platform, aims to bolster Google Cloud’s services-a backbone for its YouTube and Google TV VOD platforms. In July 2025, Google also recruited key talent from Windsurf, an AI code-generation startup, to further accelerate its AI-driven media initiatives.
Market Concentration & Characteristics:
The Video On-Demand Market remains moderately consolidated, with a few dominant platforms holding significant share while numerous niche and regional players coexist. It shows high entry barriers due to content licensing costs and user acquisition expenses. Leading platforms consolidate through mergers, partnerships, and exclusive content deals. Regional services differentiate on local language offerings and tailored pricing. Competition hinges on user experience, content diversity, and affordability. Market dynamics foster multi-platform usage among consumers. Heavy investment in original content by top players increases market polarization. Technology and infrastructure capabilities drive scale, while regulatory frameworks influence regional operations.
Report Coverage:
The research report offers an in-depth analysis based on Type, Application, Content Type, Device and Revenue Model. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The market will continue to expand globally, especially in underserved rural and semi-urban regions with improving digital infrastructure.
- AI-driven personalization will enhance content recommendations, improving viewer engagement and retention across all age groups.
- Investment in exclusive and original content will remain central to platform strategies, enabling differentiation in a competitive landscape.
- Hybrid revenue models combining subscriptions, advertising, and transactional offerings will attract diverse consumer segments.
- Integration with smart TVs, set-top boxes, and voice-enabled devices will promote multi-device accessibility and increase daily user interaction.
- Strategic alliances with telecom operators and device manufacturers will simplify access and encourage bundled service adoption.
- Regional language content and culturally relevant programming will fuel strong growth in Asia Pacific, Latin America, and Africa.
- Government regulations around content licensing, censorship, and digital privacy may shape platform operations and content policies.
- Enhanced analytics tools will help platforms refine viewer insights, optimize ad targeting, and develop data-informed content strategies.
- Immersive formats like AR, VR, and interactive storytelling will transform content consumption into participatory experiences, redefining viewer expectations.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Video on Demand Market?
What factors are driving the growth of the Video on Demand Market?
What are some challenges faced by the Video on Demand Market?
Who are the major players in the Video on Demand Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Video On-Demand Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2018; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Video On-Demand Market Snapshot
- 2.1.1 Market Size – Historical (2018) & Forecast (2018-2032) (2018: USD 98,300.00 million → 2032: USD 409,774.11 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Video On-Demand Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2018 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2018
- 2.3.2 Top 10 Players by Volume Share – 2018 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Video On-Demand Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Video On-Demand Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Video On-Demand Market Drivers
- 3.3 Video On-Demand Market Restraints & Challenges
- 3.4 Video On-Demand Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Video On-Demand Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Video On-Demand Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Video On-Demand category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Video On-Demand Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Video On-Demand Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2018)
- 5.1.2 Global Export Volume by Country (2018) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2018)
- 5.1.4 Global Import Volume by Country (2018) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2018)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2018)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Video On-Demand. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Video On-Demand Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2018
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Video On-Demand Market Share Analysis – 2018
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2018)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Video On-Demand Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Video On-Demand (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Video On-Demand
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Video On-Demand Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2018 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2018-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Video On-Demand Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Video On-Demand Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Video On-Demand Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Video On-Demand Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Video On-Demand Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Video On-Demand Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Video On-Demand Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
