
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Video Analytics Market Size 2024 | USD 17,152.09 million |
| Video Analytics Market, CAGR | 19.04% |
| Video Analytics Market Size 2032 | USD 68,993.69 million |
Market Overview
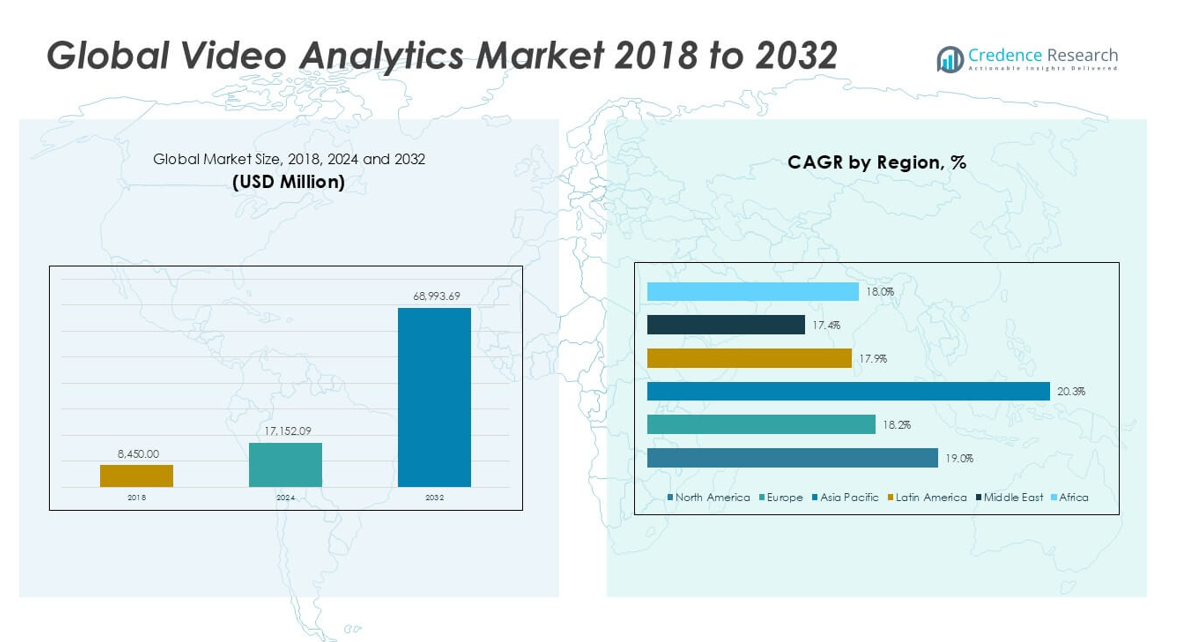
The Global Video Analytics Market is projected to grow from USD 17,152.09 million in 2024 to an estimated USD 68,993.69 million based on 2032, with a compound annual growth rate (CAGR) 19.04% from 2025 to 2032.
Rising demand for real-time monitoring and proactive threat detection is driving the adoption of video analytics solutions worldwide. The integration of AI-powered analytics into existing surveillance systems enables automated alerts, reducing human dependency and improving incident response times. Key trends include the growing use of edge-based analytics, cloud-based video processing, and facial recognition in urban safety and retail intelligence. Privacy concerns and high implementation costs remain challenges; however, continued innovation in software efficiency and regulatory compliance tools is helping mitigate these issues.
North America holds a dominant position in the video analytics market due to early adoption and strong investment in smart city initiatives and homeland security. Europe follows with steady demand across public transportation and government sectors. Asia Pacific is expected to witness the highest growth, fueled by rapid urbanization, infrastructure development, and rising security concerns. Key players in the global market include IBM Corporation, Axis Communications, Cisco Systems, Avigilon (Motorola Solutions), Genetec, Agent Video Intelligence, and Honeywell International.
Market Insights
- The Global Data Center Rack Market is projected to grow from USD 4,696.14 million in 2024 to USD 9,440.06 million by 2032, registering a CAGR of 9.14% from 2025 to 2032.
- Rising demand for scalable and energy-efficient rack systems is driving market growth across cloud computing, hyperscale, and edge data centers.
- Increasing adoption of virtualization, AI workloads, and big data analytics is boosting the need for structured and high-performance rack environments.
- Market growth is challenged by high initial setup costs and space constraints, especially in smaller or legacy data centers.
- North America holds the largest market share, supported by strong hyperscale and cloud service provider presence.
- Asia-Pacific is the fastest-growing region, fueled by rapid digital infrastructure expansion in China, India, and Singapore.
- Europe contributes steadily to the market, driven by data localization regulations and increasing demand for green and energy-efficient data centers.
Market Drivers
Rising Demand for Real-Time Surveillance and Security Intelligence
The Global Video Analytics Market is witnessing strong growth due to the increasing need for real-time surveillance across public and private sectors. Governments and enterprises seek faster incident response, predictive threat detection, and continuous monitoring to enhance safety and reduce manual surveillance efforts. It enables automated alerts and intelligent video filtering, reducing dependency on human operators. Airports, transportation systems, and urban infrastructure projects are integrating video analytics to support smart security frameworks. The need for 24/7 visibility and situational awareness fuels widespread adoption in high-risk and sensitive environments. The market continues to benefit from rising security investments and national surveillance initiatives.
- For instance, by late 2024, more than 8.4 million CCTV cameras were estimated to be connected to AI-enabled analytics platforms globally, and 18,000 airport terminals had deployed video analytics systems with facial recognition capabilities
Integration of Artificial Intelligence and Deep Learning Technologies
The integration of AI and deep learning algorithms into video analytics platforms significantly enhances their capabilities. It improves motion detection, object recognition, facial analysis, and behavior prediction with higher accuracy. These advanced features enable proactive decision-making in security operations and business optimization. The Global Video Analytics Market benefits from the trend of embedding AI at the edge, allowing devices to process data locally without latency. This evolution supports faster response and lowers bandwidth costs. AI-based analytics also opens new applications in traffic management, retail heatmapping, and industrial safety monitoring.
- For instance, in 2024, over 47% of enterprises adopted video analytics platforms embedded with deep learning capabilities, and more than 42,000 public safety projects worldwide implemented AI-based facial recognition analytics
Growth in Smart City Projects and Public Safety Investments
Smart city development plays a central role in driving demand for advanced video analytics. Urban planners and municipalities implement intelligent surveillance solutions to monitor traffic, manage crowds, and enforce regulations. It supports real-time insights that help authorities manage urban safety more effectively. The Global Video Analytics Market is aligned with government-backed programs focusing on digital transformation, law enforcement modernization, and crime prevention. These projects require scalable, automated systems that provide accurate video data interpretation. Public safety concerns across densely populated regions contribute significantly to market expansion.
Operational Efficiency and Business Intelligence in Commercial Applications
Enterprises across retail, banking, and logistics are adopting video analytics to optimize operations and improve customer experience. It delivers actionable insights by analyzing customer behavior, queue lengths, and employee activity. The Global Video Analytics Market supports functions beyond security by enabling data-driven decisions in store layouts, workforce allocation, and service delivery. Businesses use it to enhance performance, reduce shrinkage, and improve sales strategies. The ability to integrate analytics with other enterprise systems strengthens its value proposition. Growing interest in operational intelligence across sectors continues to expand its commercial relevance.
Market Trends
Growing Adoption of Cloud-Based Video Analytics Solutions for Scalability
Cloud-based video analytics is becoming a preferred solution due to its flexibility and scalability. It allows organizations to store and process large volumes of video data without significant infrastructure investments. The Global Video Analytics Market is expanding as companies move toward cloud deployment to support remote access and centralized control. It enables faster software updates, seamless integration, and real-time analytics across multiple locations. Cloud-based platforms also support easier data sharing and collaboration between security teams. The growing demand for cost-effective, scalable solutions is driving organizations to prioritize cloud-based video analytics over traditional on-premises systems.
- For instance, a leading financial services chain deployed a cloud-based video management system across more than 200 bank branches in multiple cities, enabling centralized monitoring and real-time analytics for all locations using a single cloud platform
Increased Integration of Video Analytics with Internet of Things (IoT) Devices
The integration of video analytics with IoT ecosystems is transforming operational processes across industries. IoT-enabled sensors and devices generate valuable data that video analytics systems can process in real-time for improved situational awareness. The Global Video Analytics Market benefits from this trend by offering solutions that combine video feeds with IoT sensor data to create comprehensive security and operational frameworks. It strengthens applications in traffic management, energy monitoring, and automated safety protocols. Video analytics platforms now support cross-device communication to deliver more accurate insights. IoT integration is becoming essential for businesses seeking to maximize the utility of their video surveillance infrastructure.
- For instance, IoT Analytics reported that the number of IoT use cases adopted by enterprises grew by more than 53,000 between 2021 and 2024, with video analytics and sensor integration ranking among the top applications for operational efficiency and real-time monitoring
Rising Use of Edge-Based Video Analytics for Faster Processing
Edge-based video analytics is gaining prominence due to its ability to process data closer to the source. It reduces latency and minimizes bandwidth consumption by analyzing video locally on cameras or edge devices. The Global Video Analytics Market is seeing rapid adoption of edge solutions in sectors that require immediate alerts, such as transportation and critical infrastructure. It supports real-time decision-making where network constraints limit cloud access. Edge computing also enhances data privacy by keeping sensitive information within local networks. The trend toward distributed processing is shaping the future of video analytics deployments worldwide.
Growing Implementation of AI-Powered Facial and Behavior Recognition
AI-powered facial and behavior recognition is becoming a key application within video analytics. It provides advanced capabilities for identifying individuals, analyzing crowd patterns, and detecting suspicious activities with high accuracy. The Global Video Analytics Market is evolving to meet the increasing demand for intelligent features that support security, marketing, and operational needs. It enables real-time identity verification in airports, retail stores, and event venues. Facial and behavior recognition technologies are also improving in reliability and speed, making them suitable for large-scale deployments. This trend is reshaping video analytics by expanding its use beyond traditional surveillance functions.
Market Challenges
High Initial Investment and Complex Integration Hinder Adoption
The Global Video Analytics Market faces challenges due to the high initial investment required for deployment. Advanced analytics solutions often demand significant spending on hardware, software, and network infrastructure. It can be difficult for small and medium-sized businesses to justify these costs, especially when budget constraints are present. Complex integration with legacy systems further delays implementation across organizations. Video analytics platforms must align with existing security frameworks, which can require customization and technical support. The high cost and integration complexity slow market penetration in cost-sensitive regions.
For instance, deploying a comprehensive video analytics system for a mid-sized facility typically requires an upfront investment of $60,000 to $150,000 for hardware, software, and integration, with additional annual maintenance costs ranging from $8,000 to $20,000 depending on system complexity and scale.
Privacy Concerns and Regulatory Compliance Restrict Market Growth
The Global Video Analytics Market encounters resistance from growing privacy concerns and strict regulatory environments. It processes large volumes of personal and sensitive data, raising public fears about surveillance misuse. Compliance with data protection laws such as GDPR imposes additional operational burdens on service providers and end-users. Organizations must implement data encryption, access controls, and consent mechanisms to meet these legal requirements. Navigating evolving privacy regulations across different countries creates barriers to cross-border deployments. Privacy challenges continue to limit the unrestricted expansion of video analytics solutions globally.
Market Opportunities
Expansion in Retail and Transportation Sectors Creates New Growth Avenues
The Global Video Analytics Market holds significant opportunities in retail and transportation sectors. Retailers are using it to analyze customer behavior, optimize store layouts, and improve security. It supports inventory management, loss prevention, and queue monitoring, which help businesses enhance operational efficiency. Transportation hubs such as airports, railways, and highways are investing in video analytics to manage traffic flow, detect incidents, and ensure passenger safety. The rising focus on smart transportation and automated traffic management creates demand for real-time analytics solutions. These expanding applications offer strong growth potential for vendors and service providers.
Emerging Markets and Smart City Projects Offer Untapped Potential
The Global Video Analytics Market can expand rapidly in emerging economies where smart city initiatives are gaining momentum. Governments in Asia Pacific, the Middle East, and Latin America are increasing investments in urban security, intelligent traffic systems, and public safety infrastructure. It aligns well with these projects by providing scalable, automated surveillance solutions that improve city management. Vendors can capitalize on the growing need for affordable, cloud-based video analytics in these regions. Smart city development offers long-term opportunities to integrate advanced analytics into transportation, utilities, and law enforcement networks. The rising urbanization in these markets supports sustained growth for video analytics solutions.
Market Segmentation Analysis
By Type
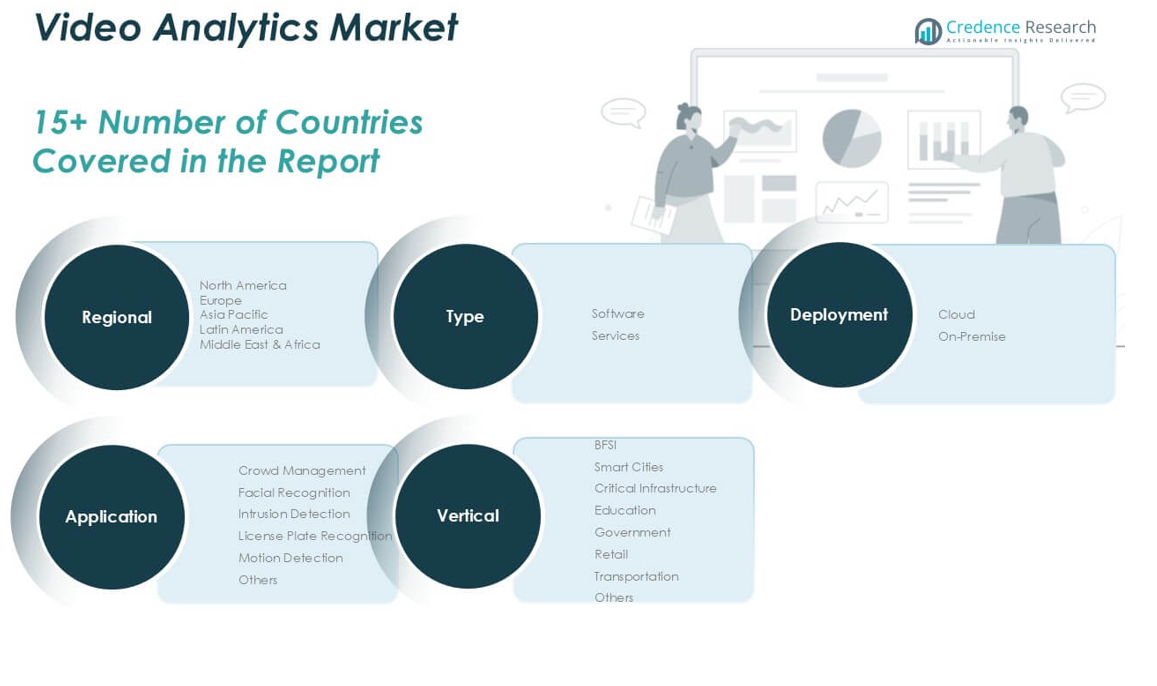
The Global Video Analytics Market is divided into software and services segments. Software holds a significant market share due to the demand for advanced video management, facial recognition, and real-time monitoring solutions. It offers features that support automated analysis, event detection, and reporting, which are critical for security and operational efficiency. Services, including installation, maintenance, and consulting, also contribute to market growth by helping organizations deploy and manage video analytics systems effectively. It supports system integration and ensures continuous performance optimization.
- For instance, Genetec reported that in 2024, it licensed over 2,400,000 video analytics software modules worldwide, while its services division completed more than 25,000 installation and maintenance projects.
By Application
The Global Video Analytics Market covers applications such as crowd management, facial recognition, intrusion detection, license plate recognition, motion detection, and others. Crowd management and facial recognition are leading segments driven by public safety, event security, and retail intelligence needs. Intrusion detection and motion detection are widely used in critical infrastructure, transportation, and urban security. License plate recognition is gaining demand in traffic management and automated parking systems. It supports law enforcement and smart city surveillance across multiple industries.
- For instance, a 2024 Axis Communications survey found that over 800,000 video analytics systems were deployed for crowd management and facial recognition globally, while more than 350,000 systems were used for license plate recognition and traffic monitoring.
By Deployment
The Global Video Analytics Market includes cloud and on-premise deployment options. Cloud-based solutions are gaining popularity for their scalability, remote access, and centralized control capabilities. On-premise systems continue to hold importance where strict data privacy and control are required, especially in government and defense sectors. It supports real-time processing and fast response in both deployment models, depending on specific organizational needs.
By Vertical
The Global Video Analytics Market serves verticals such as BFSI, smart cities, critical infrastructure, education, government, retail, transportation, and others. Smart cities and transportation sectors drive significant demand due to large-scale security and traffic management requirements. BFSI, retail, and government sectors use it to enhance surveillance, customer insights, and operational control. The technology supports safety, efficiency, and intelligent decision-making across diverse industry applications.
Segments
Based on Type
- Software
- Services
Based on Application
- Crowd Management
- Facial Recognition
- Intrusion Detection
- License Plate Recognition
- Motion Detection
- Others
Based on Deployment
- Cloud
- On-Premise
Based on Vertical
- BFSI
- Smart Cities
- Critical Infrastructure
- Education
- Government
- Retail
- Transportation
- Others
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Video Analytics Market
The North America Video Analytics Market holds a significant regional market share, with revenue growing from USD 6,236.40 million in 2024 to an estimated USD 24,968.68 million by 2032. It registers a strong CAGR of 19.0%, driven by widespread adoption in government, transportation, and retail sectors. The region benefits from advanced infrastructure, early technology adoption, and substantial investments in smart city projects and homeland security. The United States leads market demand, supported by stringent regulatory frameworks and extensive deployment of AI-powered video analytics solutions. Canada and Mexico contribute to steady growth, focusing on public safety and critical infrastructure. The region’s mature technology ecosystem fosters continuous innovation and expansion.
Europe Video Analytics Market
Europe commands a substantial regional market share, with market value projected to increase from USD 4,510.53 million in 2024 to USD 17,176.16 million by 2032. It achieves a CAGR of 18.2%, supported by robust public safety initiatives and smart city deployments across countries like Germany, the UK, and France. It emphasizes privacy-compliant solutions that align with GDPR regulations, fostering trust and adoption. The region’s growth also stems from increasing demand in transportation hubs and critical infrastructure sectors. Rising investments in AI-based surveillance and analytics technologies enhance operational efficiency across public and private domains.
Asia Pacific Video Analytics Market
The Asia Pacific Video Analytics Market shows the highest CAGR at 20.3%, expanding from USD 4,494.63 million in 2024 to USD 19,756.40 million by 2032. It captures a growing regional market share fueled by rapid urbanization, infrastructure development, and increasing security concerns. China, India, Japan, and South Korea drive demand through large-scale smart city projects and rising adoption in retail and transportation. The growing middle class and government support for digital transformation accelerate market expansion. It supports scalable cloud-based and AI-integrated video analytics to meet diverse regional needs.
Latin America Video Analytics Market
Latin America holds a smaller but growing regional market share, expected to rise from USD 843.71 million in 2024 to USD 3,139.21 million by 2032. It experiences a CAGR of 17.9%, driven by increased investments in urban security and public safety infrastructure in Brazil, Mexico, and Argentina. Governments focus on upgrading surveillance networks to manage crime rates and traffic. Emerging demand in commercial sectors such as retail and banking supports adoption. The region faces challenges related to infrastructure but continues progressing with government initiatives.
Middle East Video Analytics Market
The Middle East Video Analytics Market, with a CAGR of 17.4%, is projected to grow from USD 562.48 million in 2024 to USD 2,021.89 million by 2032. It holds a growing regional market share, driven by heightened focus on security and critical infrastructure protection in countries like the UAE, Saudi Arabia, and Qatar. Investments in smart city initiatives and border security applications fuel market demand. The region leverages cloud-based and edge analytics to improve response times and operational efficiency. It continues adopting AI-driven surveillance technologies to address geopolitical challenges.
Africa Video Analytics Market
Africa’s Video Analytics Market is expanding at a CAGR of 18.0%, increasing from USD 504.34 million in 2024 to USD 1,931.34 million by 2032. It holds a rising regional market share amid growing urbanization and security concerns in South Africa, Nigeria, and Kenya. Governments and enterprises adopt video analytics for public safety, traffic management, and commercial applications. The market benefits from international investments and infrastructure development. It continues evolving with greater emphasis on scalable and cost-effective solutions to meet diverse regional requirements.
Key players
- Avigilon Corporation (Motorola Solutions, Inc.)
- Canon Inc.
- Cisco Systems, Inc.
- Claro Enterprise Solutions
- Honeywell International Inc.
- Huawei Technologies Co Ltd.
- IBM Corporation
- Irisity AB
- Qualcomm Technologies, Inc.
- Robert Bosch Gmb
Competitive Analysis
The Video Analytics Market remains highly competitive, with key players focusing on technological innovation and strategic partnerships to enhance their market presence. Companies invest heavily in AI, machine learning, and edge computing to improve analytics accuracy and speed. It faces intense competition from both established technology firms and emerging startups offering specialized solutions. Vendors prioritize expanding their product portfolios and entering new geographical markets to capture diverse industry verticals. Differentiation through customization, integration capabilities, and customer support strengthens market positioning. Continuous R\&D and acquisition strategies help maintain a competitive edge in a rapidly evolving environment. The dynamic landscape demands agility and innovation to meet growing security and operational efficiency requirements worldwide.
Recent Developments
- In May 2025, Avigilon Corporation released Unity Video 8.6.0.8, featuring seamless integration with HALO 4 sensors, unified event linking, and enhanced system control
- In March 2025, Cisco Systems introduced Agile Services Networking at Mobile World Congress, delivering real-time visibility and AI-powered assurance for service provider video analytics networks
Market Concentration and Characteristics
The Global Video Analytics Market is moderately concentrated, with a mix of established multinational companies and emerging players competing for market share. It features strong competition driven by continuous technological advancements and increasing customer demand for intelligent surveillance solutions. Leading companies focus on product innovation, AI integration, and cloud-based analytics to strengthen their positions. It offers a wide range of solutions tailored to various industries, including retail, transportation, government, and critical infrastructure. Market participants actively pursue strategic partnerships, mergers, and acquisitions to expand their global footprint and service capabilities. The market favors companies that can deliver scalable, accurate, and real-time analytics supported by reliable customer service.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Deployment, Vertical and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Global Video Analytics Market will continue to grow rapidly, driven by increasing demand for real-time security and surveillance solutions across public and private sectors. It will expand its reach into new industries and applications, strengthening its global impact.
- Cloud-based video analytics solutions will gain strong preference, offering organizations scalable, flexible, and cost-efficient options that enable faster deployment and centralized management. It will attract businesses seeking seamless access to video intelligence.
- Edge-based video analytics will become a key focus area, supporting faster data processing, reduced latency, and improved bandwidth management, especially in transportation, smart cities, and critical infrastructure. It will shape real-time decision-making capabilities.
- Artificial intelligence and deep learning will significantly enhance video analytics capabilities, improving object detection, facial recognition, and behavior analysis accuracy across diverse environments. It will lead to more sophisticated and predictive analytics platforms.
- Privacy-focused solutions will become essential, with companies required to meet evolving global data protection laws and public expectations for secure and ethical video surveillance practices. It will drive investments in compliance technologies.
- The integration of video analytics with Internet of Things (IoT) devices will create advanced, interconnected ecosystems that support smart traffic, automated safety systems, and intelligent building management. It will unlock new operational efficiencies.
- Growing adoption of video analytics in retail, healthcare, and education sectors will support improved customer engagement, operational control, and safety management beyond traditional security applications. It will expand the technology’s commercial relevance.
- Emerging markets, particularly in Asia Pacific, Latin America, and Africa, will offer significant growth opportunities through smart city projects, infrastructure upgrades, and expanding urban security networks. It will fuel regional market penetration.
- Continuous innovation in video compression, storage, and bandwidth optimization will make video analytics more accessible to small and medium-sized businesses. It will enable wider adoption across cost-sensitive industries and regions.
- Strategic collaborations, product portfolio diversification, and mergers among key players will intensify, driving faster innovation cycles and competitive pricing structures. It will create a dynamic market landscape focused on scalability and performance.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Real-Time Surveillance and Security Intelligence
Organizations across public and private sectors are increasingly deploying video analytics to enable real-time monitoring, automated alerts, and proactive threat detection, reducing manual surveillance and improving incident response times.
Integration of AI and Deep Learning
The adoption of AI-powered analytics and deep learning algorithms enhances the accuracy of motion detection, object recognition, and behavior prediction, enabling more sophisticated and predictive video analytics solutions.
Growth in Smart City and Public Safety Investments
Smart city initiatives and government-backed urban safety projects are driving large-scale deployments of video analytics for traffic management, crowd control, and law enforcement modernization.
Cloud-Based and Edge Analytics Adoption
The shift toward cloud-based and edge analytics solutions provides scalability, centralized management, and faster data processing, making video analytics more accessible and efficient for organizations of all sizes.
Expansion in Retail and Transportation Sectors
Retailers and transportation hubs are leveraging video analytics for customer behavior analysis, queue management, loss prevention, and traffic monitoring, broadening the technology’s application beyond traditional security.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Global Data Center Rack Market in 2023 and 2032, and what is its CAGR?
What factors are driving the growth of the Global Data Center Rack Market?
Which region is expected to grow the fastest in the Global Data Center Rack Market?
Who are the key players in the Global Data Center Rack Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Software
- 1.2.2 Services
- 1.3 By Vertical
- 1.3.1 BFSI
- 1.3.2 Smart Cities
- 1.3.3 Critical Infrastructure
- 1.3.4 Education
- 1.3.5 Government
- 1.3.6 Retail
- 1.3.7 Transportation
- 1.3.8 Others
- 1.4 By Deployment
- 1.4.1 Cloud
- 1.4.2 On-Premise
- 1.5 By Application
- 1.5.1 Crowd Management
- 1.5.2 Facial Recognition
- 1.5.3 Intrusion Detection
- 1.5.4 License Plate Recognition
- 1.5.5 Motion Detection
- 1.5.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4,696.14 million → 2032: USD 9,440.06 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Video Analytics Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Video Analytics Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Video Analytics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Video Analytics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Video Analytics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Video Analytics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Video Analytics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Video Analytics Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4,696.14 million → 2032: USD 9,440.06 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Video Analytics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Software
- 12.3.6.2 Services
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Vertical - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 BFSI
- 12.4.6.2 Smart Cities
- 12.4.6.3 Critical Infrastructure
- 12.4.6.4 Education
- 12.4.6.5 Government
- 12.4.6.6 Retail
- 12.4.6.7 Transportation
- 12.4.6.8 Others
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Deployment - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Cloud
- 12.5.6.2 On-Premise
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Base-Year Market Share, 2024
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Crowd Management
- 12.6.6.2 Facial Recognition
- 12.6.6.3 Intrusion Detection
- 12.6.6.4 License Plate Recognition
- 12.6.6.5 Motion Detection
- 12.6.6.6 Others
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Video Analytics End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Video Analytics Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Video Analytics Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Video Analytics Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 IBM Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Axis Communications
- 18.4 Cisco Systems, Inc.
- 18.5 Avigilon (Motorola Solutions)
- 18.6 Genetec
- 18.7 Agent Video Intelligence
- 18.8 Honeywell International Inc.
- 18.9 Canon Inc.
- 18.10 Huawei Technologies Co Ltd.
- 18.11 Robert Bosch GmbH
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

