
Market Overview:
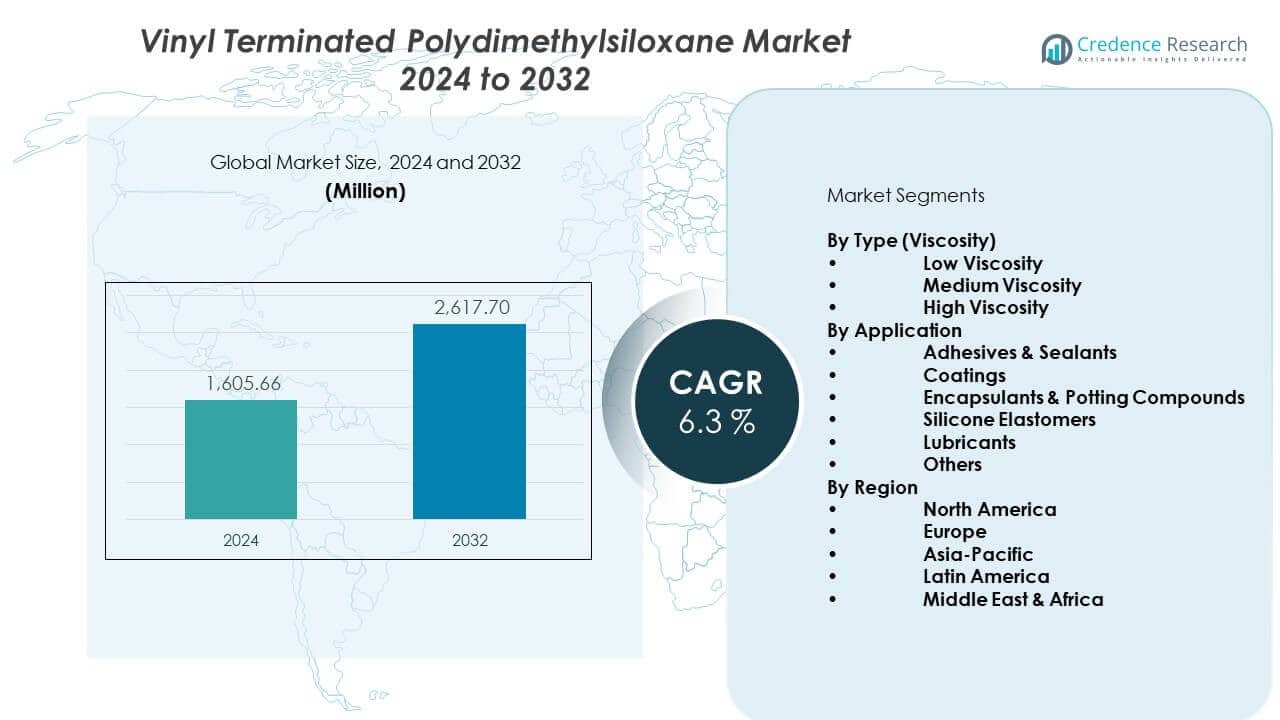
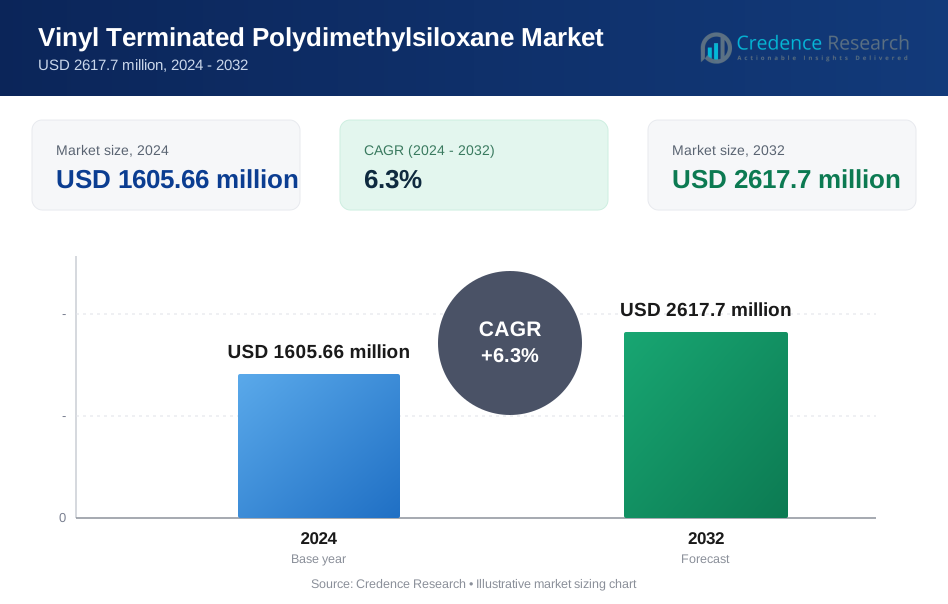
The Vinyl Terminated Polydimethylsiloxane Market is projected to grow from USD 1605.66 million in 2024 to USD 2617.7 million by 2032, registering a CAGR of 6.3% over the forecast period. Growth reflects rising demand for silicone intermediates with strong thermal stability and flexible curing behavior. Adoption increases across elastomers, coatings, and adhesive production due to reliable crosslinking performance.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Vinyl Terminated Polydimethylsiloxane Market Size 2024 | USD 1605.66 Million |
| Vinyl Terminated Polydimethylsiloxane Market, CAGR | 6.3% |
| Vinyl Terminated Polydimethylsiloxane Market Size 2032 | USD 2617.7 Million |
Demand increases because industries rely on silicone materials that support long-lasting stability and efficient processing. Automotive and electronics manufacturers adopt vinyl-terminated PDMS for its heat resistance and compatibility with addition-cure systems. The chemical structure helps formulators achieve better elasticity in sealants, encapsulants, and molded components. Producers boost investments in advanced silicone formulations to meet stricter performance needs. Rising consumption of high-purity intermediates in medical and industrial applications strengthens market traction. Continuous product development from polymer suppliers also enhances acceptance across specialized end-use sectors.
Asia Pacific holds a leading position due to large-scale silicone production and high consumption across automotive, electronics, and construction industries. China, Japan, and South Korea drive steady adoption through expanding manufacturing ecosystems. North America follows with strong demand for specialty polymers and innovation in performance materials. Europe maintains stable growth supported by advanced chemical processing capabilities and strong regulatory standards. Emerging regions like Southeast Asia and Latin America gain momentum as industrial output rises and silicone-based adhesive and elastomer usage accelerates across local manufacturing units.
Market Insights:
- The Vinyl terminated polydimethylsiloxane market is valued at USD 1605.66 million in 2024 and is projected to reach USD 2617.7 million by 2032, growing at a CAGR of 6.3% through the forecast period.
- Asia Pacific (40%), North America (25%), and Europe (22%) hold the largest shares due to strong electronics, automotive, and specialty chemical industries that rely on high-performance silicone intermediates.
- Latin America (7%) emerges as the fastest-growing region, supported by expanding industrial production, rising construction activities, and increasing adoption of silicone-based adhesives and sealants.
- Silicone elastomers hold about 30% share, driven by heavy usage in flexible molded components and high-precision industrial parts.
- Adhesives and sealants account for nearly 25% share, supported by demand for durable bonding solutions across construction, electronics, and automotive applications.
Market Drivers:
Rising Adoption of High-Performance Silicone Intermediates
Demand rises due to strong interest in high-grade silicone systems. Buyers seek stable materials for harsh environments. The Vinyl terminated polydimethylsiloxane market benefits from this preference. Engineers value consistent curing across advanced elastomer lines. Formulators choose vinyl-terminated grades for reliable reinforcement. Production teams favor inputs that reduce failure rates. Manufacturers expand usage across sealants and molded parts. It supports tighter quality control in industrial processes. Broader acceptance drives steady growth across major sectors.
- For instance, Wacker Chemie AG started an expansion of its Zhangjiagang silicone facility in 2023 (specifically, construction began in September 2023), with mechanical completion in May 2025, strengthening the global supply of specialty silicone polymers.
Growing Use in Automotive and Electronic Component Manufacturing
Automotive lines adopt silicone intermediates for thermal resistance. Electronics makers need materials that handle constant heat stress. The Vinyl terminated polydimethylsiloxane market gains traction from this trend. Producers integrate vinyl-terminated grades into encapsulation tasks. Device makers use these polymers for stable insulation. Reliability needs push firms toward advanced silicone inputs. Supply chains expand procurement strategies across major hubs. It supports precision in sensitive component work. Demand increases with rising production volumes.
- For instance, Shin-Etsu Chemical continued to invest in and increase its silicone product production capacity in Japan in 2021 as part of ongoing expansion plans to support rising demand from automotive and electronics customers.
Expanding Application in Sealants, Adhesives, and Coatings
Industrial sites rely on silicone systems for flexible bonding. Sealant producers prefer materials with predictable cure profiles. The Vinyl terminated polydimethylsiloxane market benefits from this reliance. Adhesive developers add vinyl-terminated inputs for better elongation. Coating teams value steady mechanical strength. Producers target higher durability across varied surfaces. It helps teams meet demanding performance criteria. Adoption rises across commercial and industrial projects. Broader manufacturing growth supports market expansion.
Rising Investment in Advanced Silicone Processing Capabilities
Producers expand capacity for specialty elastomers. Facilities upgrade reactors for cleaner outputs. The Vinyl terminated polydimethylsiloxane market gains from these upgrades. Investments support faster scale-up across multiple lines. Buyers depend on uninterrupted supply streams. New plants reduce pressure on global distributors. It strengthens resilience across regional markets. Equipment upgrades boost production consistency. Innovation efforts improve product reliability.
Market Trends:
Shift Toward High-Purity Silicone Grades for Precision Applications
Industries seek cleaner polymer chains for sensitive tasks. High-purity grades reduce contamination risks. The Vinyl terminated polydimethylsiloxane market reflects this tilt. Medical firms require polymers with tight specifications. Electronics teams depend on low-defect inputs. Producers refine synthesis routes for improved purity. It supports strict compliance in regulated fields. Buyers gain stable performance across delicate workflows. Demand rises for premium formulations.
Rising Preference for Customizable Polymer Structures
End-use sectors request tailored molecular designs. Custom structures support unique mechanical outcomes. The Vinyl terminated polydimethylsiloxane market adapts to these needs. Producers offer varied molecular weights for flexibility. Customers choose grades that support specific curing profiles. Designers work with suppliers for optimized blends. It drives innovation across specialty lines. Customized inputs improve process efficiency. Adoption increases across niche domains.
- For instance, Elkem ASA expanded its R&D center in Shanghai in 2023 to develop customized silicone polymer structures for regional electronics and industrial clients. It drives innovation across specialty lines.
Wider Integration in Lightweight Material Engineering
Industries invest in lightweight component design. Silicone systems support this movement. The Vinyl terminated polydimethylsiloxane market aligns well with this shift. Polymer flexibility aids structural balance. Manufacturers reduce weight without losing strength. It improves efficiency across transportation assets. Design teams use silicone intermediates for stable frameworks. Adoption increases in compact hardware lines. Growth continues in weight-critical applications.
Growth of Regional Silicone Ecosystems Supporting Local Supply Chains
Regional clusters invest in silicone processing hubs. Localized production strengthens supply certainty. The Vinyl terminated polydimethylsiloxane market benefits from this structure. Firms reduce reliance on distant suppliers. Transportation delays decline across critical routes. It improves delivery predictability for buyers. Regions build stronger partnerships with producers. Supply networks gain better resilience. Market access widens across emerging zones.
Market Challenges Analysis:
High Dependence on Specialized Processing and Feedstock Stability
Specialized feedstocks limit production flexibility. Producers face pressure from volatile input availability. The Vinyl terminated polydimethylsiloxane market feels this instability. Facilities require strict controls for consistent outputs. Any fluctuation impacts quality assurance. It increases operational risk for manufacturers. Firms invest more to stabilize production lines. Supply chain issues raise procurement burdens. These factors create obstacles for wide expansion.
Regulatory Compliance and Complex Performance Validation Standards
Industries demand strict validation for silicone intermediates. Approval cycles stretch timelines across sectors. The Vinyl terminated polydimethylsiloxane market aligns with many regulated fields. Producers navigate long audit cycles for sensitive uses. Compliance rules increase testing steps. It raises costs across development stages. Buyers require documented proof of reliability. Firms adjust processes to meet certification needs. The burden limits entry for smaller manufacturers.
Market Opportunities:
Expanding Demand for Specialty Elastomers Across High-Growth Sectors
Elastomer demand rises across fast-growing industries. Buyers search for stronger and flexible materials. The Vinyl terminated polydimethylsiloxane market gains from this expansion. Producers supply higher-grade silicone intermediates for unique tasks. Engineers use these inputs for performance-driven projects. It supports product diversification across regions. Innovation improves polymer adaptability. Market participants tap new industrial clients. Broader interest opens new avenues.
Rising Commercial Use in Next-Generation Coating and Adhesive Systems
Advanced coatings need stable silicone inputs. Adhesive lines prefer materials with predictable outputs. The Vinyl terminated polydimethylsiloxane market benefits from this demand. Producers develop new blends for commercial projects. Teams use specialized grades for durable surfaces. It boosts application reach across construction and electronics. Buyers depend on improved cure profiles. New sectors adopt silicone systems. Growth opportunities expand across global hubs.
Market Segmentation Analysis:
By Type (Viscosity)
Low-viscosity grades hold strong demand due to easy handling and fast integration across large-volume production lines. Medium-viscosity materials gain traction where balanced flow and mechanical stability are required. High-viscosity variants support applications that need stronger structural reinforcement. The Vinyl terminated polydimethylsiloxane market benefits from diverse viscosity preferences that match formulation needs across industrial systems. It supports users seeking predictable curing within elastomers, coatings, and adhesive platforms. Each viscosity range meets different performance targets for thermal resistance, elasticity, and strength. Industries choose specific grades to align with process speed and quality requirements. Broader availability drives flexible usage across global manufacturing hubs.
- For instance, Dow Inc. globally expanded its capacity for silicone elastomers in 2021 to meet growing demand and improve supply consistency for industrial customers across various high-growth markets, including automotive applications. A related investment occurred at the company's Carrollton, Kentucky plant in 2018, where Dow announced plans for a new siloxane polymer plant to increase capacity in the Americas and improve operational efficiency.
By Application
Adhesives and sealants represent a key segment due to strong reliance on silicone intermediates for durable bonding. Coatings adopt vinyl-terminated PDMS for superior surface protection. Encapsulants and potting compounds gain importance in electronics that require stable insulation. Silicone elastomers use these inputs for improved elasticity and curing precision. Lubricant applications grow due to consistent performance under varied temperature conditions. Other industrial uses expand with rising demand for specialized silicone systems. The Vinyl terminated polydimethylsiloxane market supports wide application diversity through adaptable molecular structures. It strengthens material performance across automotive, electronics, construction, and industrial production chains.
- For instance, CHT Group increased its silicone elastomer capacity in Germany in 2022 to meet higher demand from coating and sealing applications.
Segmentation:
By Type (Viscosity)
- Low Viscosity
- Medium Viscosity
- High Viscosity
By Application
- Adhesives & Sealants
- Coatings
- Encapsulants & Potting Compounds
- Silicone Elastomers
- Lubricants
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Asia Pacific – Leading Production and Consumption Hub
Asia Pacific holds the largest share of the Vinyl terminated polydimethylsiloxane market. The region accounts for around 40% of global demand, led by China. Strong automotive, electronics, and construction bases sustain wide silicone usage. Japan, South Korea, and India strengthen regional consumption with advanced manufacturing clusters. Local producers expand capacity to support export and domestic needs. It benefits from integrated chemical parks, cost-effective labor, and strong downstream networks. Rising investments in specialty silicones further reinforce the region’s dominant position.
North America and Europe – Innovation-Centric, High-Value Demand Centers
North America represents roughly 25% of global demand, driven by high-value applications. The United States leads consumption through advanced electronics, aerospace, and industrial sectors. The Vinyl terminated polydimethylsiloxane market gains steady traction from strong R&D pipelines. Europe holds close to 22% share, supported by Germany, France, and the United Kingdom. Strict performance and safety standards promote use of reliable silicone intermediates. Regional players focus on specialty grades for coatings, sealants, and elastomers. It benefits from established chemical infrastructure and technology-focused customers.
Latin America and Middle East & Africa – Emerging Growth Frontiers
Latin America contributes around 7% share, with Brazil and Mexico driving demand. Growing industrialization and construction support higher silicone usage across adhesives and sealants. The Vinyl terminated polydimethylsiloxane market sees new opportunities with rising electronics assembly activities. Middle East and Africa hold nearly 6% share, led by the Gulf states and South Africa. Demand grows in infrastructure, energy, and industrial maintenance applications. Local distributors strengthen links with global silicone producers. It gains momentum as regional manufacturers upgrade material performance standards.
Key Player Analysis:
- Dow Inc.
- Wacker Chemie AG
- Elkem ASA
- Shin-Etsu Chemical Co., Ltd.
- Momentive Performance Materials Inc.
- Bluestar Silicones (Elkem)
- Jiangxi New Jiayi New Materials Co., Ltd.
- Guangzhou Tinci Materials Technology Co., Ltd.
- CHT Group
- Siltech Corporation
- GELEST
- PCC Group
- AB Specialty Silicones
- Finetech Industry Limited
- United Chemical & Material
- Shandong Dayi Chemical & Material
Competitive Analysis:
The Vinyl terminated polydimethylsiloxane market shows strong competition among established silicone producers. Global players expand technical capabilities to strengthen specialty polymer portfolios. Firms focus on viscosity-specific grades that support advanced adhesive, coating, and elastomer applications. The Vinyl terminated polydimethylsiloxane market benefits from investments in purity control and molecular customization. Competitors improve production efficiency to secure long-term contracts with industrial customers. It gains momentum from partnerships that enhance regional supply strength. Leading companies build application support teams to guide formulators. Rising demand for performance-driven silicone intermediates pushes firms to upgrade product lines.
Recent Developments:
- In September 2025, Dow Inc. launched DOWSIL™ 5-1050 Polymer Processing Aid (PPA), a fluoropolymer-free solution designed as an effective alternative for film packaging applications. This new product addresses industry demands for safer, high-quality polyethylene films by mitigating melt fractures and reducing die lip buildup, while complying with both European and US food contact regulations.
- In March 2025, Wacker Chemie AG announced expectations of a 10% sales increase in its silicones division for the year, driven by strong demand in specialty silicone products and semiconductor-grade polysilicon. The company highlighted its pivotal role in enabling advanced technology sectors, including AI applications, reflecting robust future growth prospects.
- In 2025, Shin-Etsu Chemical Co., Ltd. developed a recyclable thermoplastic silicone that combines high hardness with remarkable elongation, addressing recyclability challenges inherent in conventional silicone rubbers and advancing sustainability in silicone materials.
Report Coverage:
The research report offers an in-depth analysis based on By Type (Low Viscosity, Medium Viscosity, High Viscosity) and By Application (Adhesives & Sealants, Coatings, Encapsulants & Potting Compounds, Silicone Elastomers, Lubricants, Others). It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand grows in advanced elastomers requiring consistent curing performance.
- Adoption increases in electronics insulation and encapsulation applications.
- Producers expand regional capacity to reduce supply disruptions.
- High-purity grades gain traction across regulated industrial segments.
- Adhesive and sealant manufacturers integrate more silicone intermediates.
- Custom viscosity grades support specialized engineering needs.
- Users adopt silicone systems for lightweight component design.
- R&D efforts strengthen material stability and processing efficiency.
- Global players pursue partnerships to expand downstream reach.
- Sustainability goals influence new silicone synthesis improvements.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Vinyl terminated polydimethylsiloxane market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Vinyl terminated polydimethylsiloxane market projected to grow between 2024 and 2032?
Which Vinyl terminated polydimethylsiloxane market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Vinyl terminated polydimethylsiloxane market?
Who are the leading companies in the Vinyl terminated polydimethylsiloxane market?
Which region commanded the largest share of the Vinyl terminated polydimethylsiloxane market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Vinyl Terminated Polydimethylsiloxane Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Vinyl Terminated Polydimethylsiloxane Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1605.66 million → 2032: USD 2617.7 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Vinyl Terminated Polydimethylsiloxane Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Vinyl Terminated Polydimethylsiloxane Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Vinyl Terminated Polydimethylsiloxane Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Vinyl Terminated Polydimethylsiloxane Market Drivers
- 3.3 Vinyl Terminated Polydimethylsiloxane Market Restraints & Challenges
- 3.4 Vinyl Terminated Polydimethylsiloxane Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Vinyl Terminated Polydimethylsiloxane Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Vinyl Terminated Polydimethylsiloxane Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Vinyl Terminated Polydimethylsiloxane category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Vinyl Terminated Polydimethylsiloxane Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Vinyl Terminated Polydimethylsiloxane Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Vinyl Terminated Polydimethylsiloxane market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Vinyl Terminated Polydimethylsiloxane Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Vinyl Terminated Polydimethylsiloxane Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Vinyl Terminated Polydimethylsiloxane Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Vinyl Terminated Polydimethylsiloxane (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Vinyl Terminated Polydimethylsiloxane Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Vinyl Terminated Polydimethylsiloxane Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Vinyl Terminated Polydimethylsiloxane Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Vinyl Terminated Polydimethylsiloxane Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Vinyl Terminated Polydimethylsiloxane Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Vinyl Terminated Polydimethylsiloxane Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Vinyl Terminated Polydimethylsiloxane Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Vinyl Terminated Polydimethylsiloxane Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Vinyl Terminated Polydimethylsiloxane Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
