
Market Overview
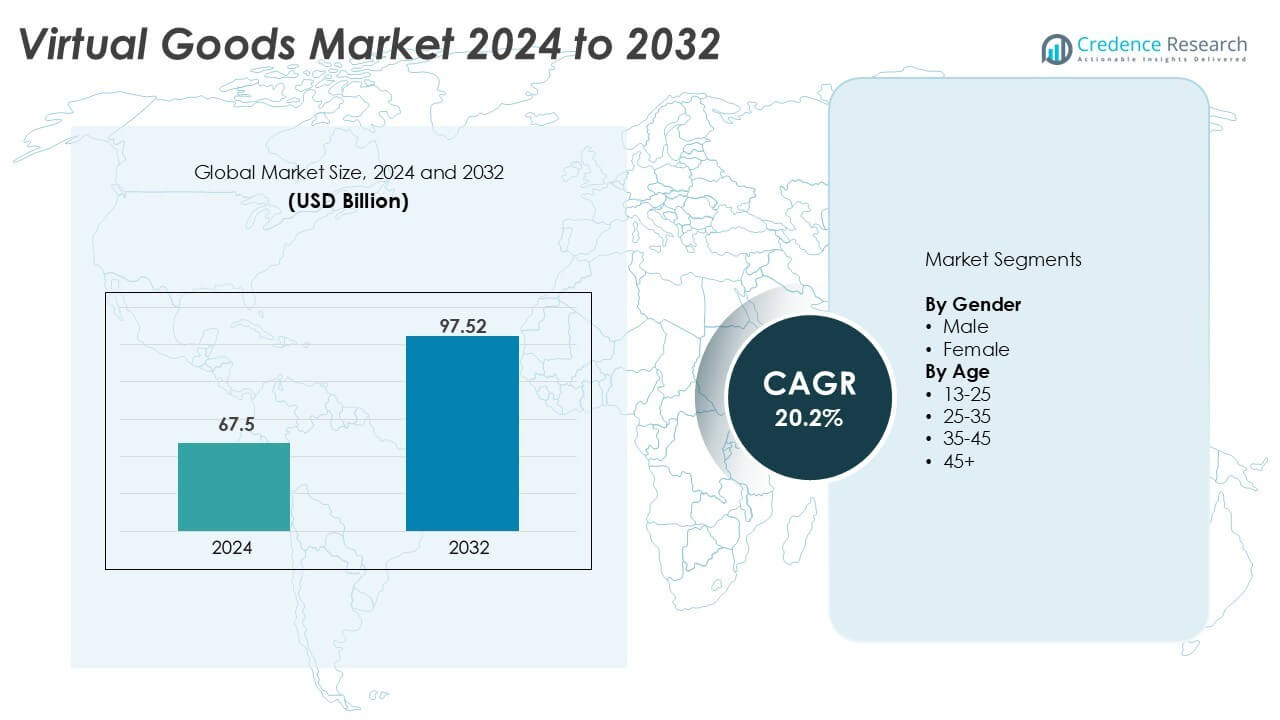
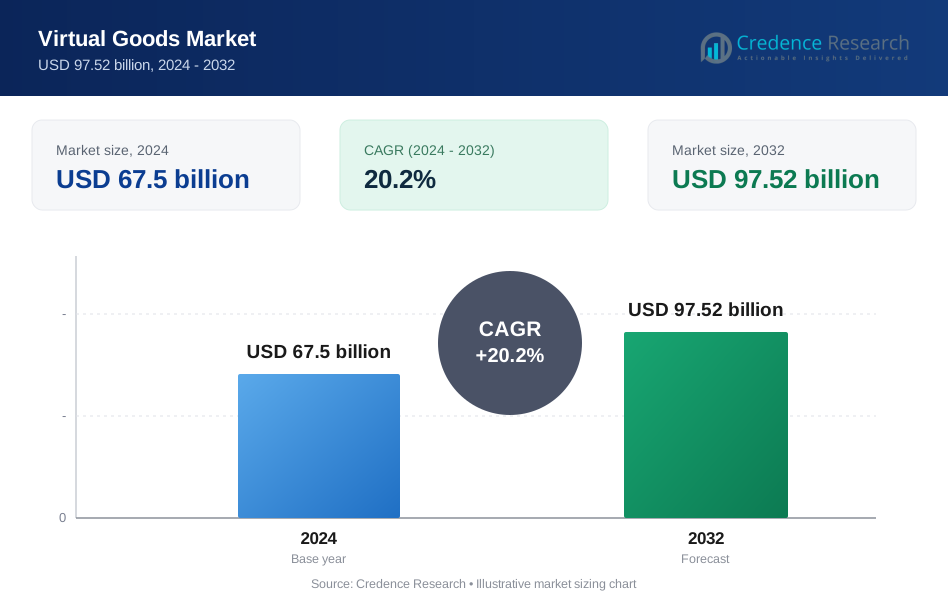
The Virtual Goods Market was valued at USD 67.5 billion in 2024 and is anticipated to reach USD 97.52 billion by 2032, growing at a CAGR of 20.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Virtual Goods Market Size 2024 | USD 67.5 billion |
| Virtual Goods Market, CAGR | 20.2% |
| Virtual Goods Market Size 2032 | USD 97.52 billion |
The virtual goods market is led by prominent players such as Facebook Inc., Tencent Holdings Ltd., Zynga Inc., Gree Inc., Mixi Inc., Kabam Inc., Tagged Inc., Myspace LLC, hi5 Networks Inc., and Bebo Inc. These companies dominate through vast user networks, innovative digital ecosystems, and diversified in-game economies. Tencent Holdings Ltd. leads with strong integration of gaming and social platforms, while Facebook (Meta) drives growth through metaverse and virtual commerce initiatives. North America remains the leading region, accounting for 34% of the global market share in 2024, supported by advanced digital infrastructure and high consumer spending. Asia Pacific follows closely, driven by expanding gaming penetration and rapid adoption of virtual economies.
Market Insights
- The Virtual Goods Market was valued at USD 67.5 billion in 2024 and is projected to reach USD 97.52 billion by 2032, growing at a CAGR of 20.2%.
- Growth is driven by the expansion of gaming platforms, social networks, and metaverse adoption, supported by rising digitalization and microtransaction convenience.
- Key trends include the rise of NFTs, virtual fashion, and cross-platform integration, enhancing personalization and user engagement.
- Major players such as Facebook Inc., Tencent Holdings Ltd., Zynga Inc., and Gree Inc. dominate, focusing on blockchain innovation and virtual commerce strategies.
- North America leads with 34% market share, followed by Asia Pacific at 30% and Europe at 28%; by segment, males hold 58% share, and the 13–25 age group leads with 46% share, reflecting strong engagement from younger consumers.
Market Segmentation Analysis:
By Gender
The male segment dominated the virtual goods market in 2024, accounting for over 58% of the total share. Higher participation in online gaming, esports, and digital collectibles drives this dominance. Men tend to spend more on in-game assets, weapon skins, and NFTs associated with competitive gaming environments. The rising popularity of multiplayer and fantasy-based platforms continues to attract male users. However, the female segment is expanding rapidly, fueled by growth in virtual fashion, avatar customization, and social simulation games that emphasize personalization and creative interaction.
- For instance, Roblox Corporation noted over 68 million daily active users, with male players contributing significantly to in-game purchases and collectible upgrades.
By Age
The 13–25 age group held the largest market share of around 46% in 2024, reflecting strong engagement with virtual worlds, mobile gaming, and social media-driven metaverse platforms. Younger consumers are early adopters of digital collectibles and virtual currencies, often influenced by online communities and creators. The 25–35 segment also shows robust growth, supported by higher disposable income and interest in branded digital merchandise. Meanwhile, users aged 35–45 and 45+ contribute moderately, with adoption growing through workplace virtual environments and lifestyle-based digital ecosystems.
- For instance, Meta's social VR platform, Horizon Worlds, has struggled with user retention, falling short of its initial goals and, in fact, declining to less than 200,000 monthly active users by late 2022.
Key Growth Drivers
Expansion of Gaming and Metaverse Ecosystems
The rapid expansion of online gaming and metaverse ecosystems is a major growth driver for the virtual goods market. Games such as Fortnite, Roblox, and PUBG have popularized the purchase of in-game items like skins, weapons, and accessories. The integration of blockchain in gaming further supports ownership authentication and resale opportunities for digital assets. Virtual environments like Meta Horizon Worlds and Decentraland promote immersive experiences where users invest in personalized avatars and digital real estate. This growing digital economy encourages user engagement and monetization, driving consistent demand for virtual goods across entertainment, fashion, and social interaction platforms.
- For instance, Epic Games reported that Fortnite has over 650 million registered players. In 2024 alone, players spent more than 5.23 billion hours in creative maps made by other users. In November 2024, the game saw a huge surge in popularity, logging 44.7 million players in a single day and 14.3 million concurrent players for a specific event.
Rising Digitalization and Virtual Commerce Adoption
The growing digital economy, powered by increasing internet penetration and smartphone use, is fueling virtual commerce. Social media platforms such as Instagram, TikTok, and Snapchat are integrating digital collectibles, filters, and augmented-reality shopping tools. These innovations enable users to purchase, trade, and showcase virtual goods, strengthening emotional and social value. Additionally, advancements in payment infrastructure and digital wallets streamline microtransactions, making small-value virtual purchases convenient. Businesses also leverage virtual goods to boost brand engagement through limited-edition releases and gamified marketing strategies, further driving global adoption.
- For instance, Snap Inc. has reported significant AR Lens engagement, including one report in early 2025 stating that users in India engage with AR lenses over 80 billion times a month.
Growing Integration of NFTs and Blockchain Technology
Blockchain technology has redefined ownership in the virtual space, creating new revenue streams through non-fungible tokens (NFTs). These tokens verify authenticity and scarcity of digital items such as art, avatars, and fashion assets. As consumers seek unique, tradable items, NFTs enhance user confidence and resale potential. Major brands and entertainment companies are entering NFT ecosystems to offer exclusive content and experiences, broadening virtual marketplaces. The ability to monetize virtual assets across platforms strengthens digital asset valuation, driving investment and long-term participation in virtual economies.
Key Trends & Opportunities
Virtual Fashion and Digital Identity Expansion
Virtual fashion is emerging as a key trend, driven by the growing importance of digital identity. Consumers increasingly purchase branded digital wearables for avatars across gaming and social platforms. Fashion houses such as Gucci and Nike are launching virtual collections, creating hybrid experiences that connect physical and digital worlds. These developments open new opportunities for luxury brands and independent designers to monetize creativity. As the metaverse expands, fashion-based virtual goods are expected to become a major monetization channel within the broader digital economy.
- For instance, in 2021, Nike's RTFKT Studio launched its CloneX NFT collection of 20,000 avatars on the Ethereum blockchain, generating significant initial revenue. However, mirroring a broader downturn in the NFT market, the collection's value dropped considerably by 2024, and Nike ultimately announced it would shut down RTFKT's web3 operations by January 2025.
Cross-Platform Integration and Brand Collaborations
The convergence of gaming, entertainment, and e-commerce platforms presents a major opportunity for cross-industry collaboration. Brands are partnering with gaming studios and metaverse platforms to create immersive marketing campaigns featuring branded virtual goods. Such collaborations enhance brand visibility and foster new engagement channels with younger audiences. Integration across multiple virtual environments also enables seamless transfer of purchased assets, improving consumer loyalty. These strategic alliances are expected to define the next phase of growth in the virtual goods ecosystem.
Key Challenges
Regulatory Uncertainty and Intellectual Property Risks
The virtual goods market faces growing regulatory challenges related to taxation, digital ownership, and consumer protection. Ambiguous policies across regions create compliance risks for both developers and consumers. Intellectual property violations, counterfeit digital assets, and NFT scams also undermine user confidence. As virtual transactions increase, authorities are implementing stricter oversight on monetization practices and cross-border payments. Companies must strengthen transparency and adopt robust verification mechanisms to ensure authenticity and legal security within digital economies.
Market Saturation and User Fatigue
Despite strong growth, the market faces the risk of oversaturation. The flood of repetitive digital assets and frequent in-game promotions can reduce consumer excitement. High competition among developers also pressures pricing and profitability. Furthermore, short product life cycles and changing user preferences may lead to declining engagement. To overcome fatigue, companies must prioritize innovation and personalization in digital goods, leveraging data analytics and AI-driven recommendations to sustain user interest and ensure long-term value creation.
Regional Analysis
North America
North America held the largest market share of 34% in 2024, driven by strong adoption of gaming platforms, NFTs, and metaverse-based applications. The U.S. leads the region with major players like Roblox, Meta, and Epic Games investing heavily in virtual economies. Growing interest in digital collectibles and branded collaborations strengthens market expansion. Canada follows with rising demand for virtual fashion and augmented-reality assets. The mature digital infrastructure, coupled with high disposable income and early adoption of blockchain technology, continues to make North America a key hub for virtual goods innovation and monetization.
Europe
Europe accounted for around 28% of the global market share in 2024, supported by rising consumer engagement in immersive digital experiences. The UK, Germany, and France lead the market with strong gaming communities and expanding digital art ecosystems. European fashion brands increasingly collaborate with virtual platforms to offer exclusive digital wearables and NFTs. Regulatory clarity around digital assets and growing investment in metaverse infrastructure also fuel adoption. Demand for personalized avatars, virtual concerts, and cultural collectibles further enhances Europe’s position as a rapidly evolving virtual goods market.
Asia Pacific
Asia Pacific captured a market share of 30% in 2024, making it one of the fastest-growing regions. China, Japan, and South Korea dominate due to strong gaming cultures and integration of virtual economies in popular platforms. India and Southeast Asia are emerging markets with rising smartphone penetration and youth-driven digital spending. Regional giants like Tencent and NetEase drive innovation through in-game economies and social metaverse experiences. The widespread acceptance of virtual gifting and live-stream commerce also supports revenue growth, positioning Asia Pacific as a dynamic hub for virtual goods expansion.
Latin America
Latin America represented around 5% of the virtual goods market in 2024, with increasing engagement from younger demographics in Brazil, Mexico, and Argentina. Growth is fueled by affordable internet access, expanding gaming communities, and the popularity of digital collectibles on regional social platforms. Brazil leads in metaverse participation and esports-related virtual spending. Limited payment infrastructure and low digital literacy in some areas restrain full potential. However, localized content, brand partnerships, and rising smartphone usage are expected to accelerate market development across Latin America over the coming years.
Middle East & Africa
Middle East & Africa accounted for approximately 3% of the global share in 2024, showing steady growth from expanding gaming and entertainment sectors. The UAE and Saudi Arabia lead with government-backed metaverse initiatives and digital innovation investments. Younger consumers increasingly adopt virtual avatars, digital art, and in-game purchases as part of social interaction trends. Africa’s growth remains in early stages, supported by improving connectivity and mobile gaming adoption. Continued investment in digital infrastructure and localized payment solutions is expected to drive virtual goods adoption across the region.
Market Segmentations:
By Gender
- Male
- Female
By Age
- 13-25
- 25-35
- 35-45
- 45+
By Geography
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Competitive Landscape
The competitive landscape of the virtual goods market is highly dynamic, characterized by the presence of major technology companies, gaming studios, and social networking platforms. Key players such as Facebook Inc., Tencent Holdings Ltd., Gree Inc., Mixi Inc., Zynga Inc., and Kabam Inc. lead through extensive virtual ecosystems that integrate gaming, social media, and digital commerce. These firms invest heavily in metaverse development, NFTs, and blockchain infrastructure to enhance user engagement and monetization. Emerging companies like Tagged Inc., Myspace LLC, hi5 Networks Inc., and Bebo Inc. focus on niche markets emphasizing social interaction and digital gifting. Strategic partnerships, mergers, and brand collaborations remain central to sustaining competitiveness. Companies are also diversifying revenue streams through virtual currencies, limited-edition assets, and cross-platform interoperability. The market’s competitive intensity continues to rise as players prioritize innovation, personalization, and immersive experiences to capture expanding user bases in both developed and emerging regions.
Key Player Analysis
- Facebook Inc.
- Gree Inc.
- Mixi Inc.
- Tencent Holdings Ltd.
- hi5 Networks Inc.
- Bebo Inc.
- Myspace LLC
- Tagged Inc.
- Zynga Inc.
- Kabam Inc.
Recent Developments
- In May 2025, Meta launched a USD 50 million Creator Fund to sponsor user-generated virtual goods across its portfolio.
- In March 2025, Tripledot agreed to acquire AppLovin’s games unit for USD 900 million, boosting cross-promotion reach.
- In March 2025, Tencent lifted its stake in Kadokawa Corporation, broadening Japanese IP access for future asset pipelines.
- In March 2025, Tilting Point opened a USD 150 million user-acquisition fund aimed at scaling mobile titles with heavy virtual goods monetization
Report Coverage
The research report offers an in-depth analysis based on Gender, Age and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The virtual goods market will continue expanding with increasing integration of gaming and metaverse platforms.
- Blockchain and NFTs will strengthen digital ownership and enhance asset value transparency.
- Virtual fashion and branded collaborations will create new monetization channels for global brands.
- AI-driven personalization will improve user engagement and purchasing behavior in digital ecosystems.
- Cross-platform interoperability will allow users to transfer assets across multiple virtual environments.
- Social media platforms will further integrate virtual commerce and digital collectibles.
- Younger demographics will remain the core drivers of virtual goods demand.
- Emerging markets in Asia and Latin America will experience faster adoption due to mobile gaming growth.
- Companies will invest more in cybersecurity and intellectual property protection for digital assets.
- Long-term growth will depend on regulatory clarity, payment innovation, and sustainable virtual economy models.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Gaming and Metaverse Ecosystems
The proliferation of online gaming platforms and immersive metaverse environments is fueling demand for virtual goods, as users increasingly purchase in-game items, skins, and digital real estate to personalize their experiences and participate in virtual economies.
Rising Digitalization and Virtual Commerce Adoption
Greater internet penetration, smartphone usage, and integration of digital payment systems are making it easier for consumers to buy, trade, and showcase virtual goods, driving market growth through microtransactions and social commerce.
Integration of NFTs and Blockchain Technology
Blockchain enables secure ownership and authenticity of digital assets, while NFTs create new revenue streams and enhance user confidence in trading unique virtual items, attracting both consumers and brands to the virtual goods market.
Growth of Virtual Fashion and Digital Identity
The increasing importance of digital self-expression is driving consumers to purchase branded virtual wearables and accessories for avatars, opening new monetization channels for fashion brands and designers within gaming and social platforms.
Cross-Platform Integration and Brand Collaborations
Collaborations between gaming, entertainment, and e-commerce platforms allow for seamless transfer and use of virtual goods across multiple environments, enhancing user engagement and loyalty while providing brands with innovative marketing opportunities.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Virtual Goods market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Virtual Goods market projected to grow between 2025 and 2032?
Which age segment is expected to post the highest CAGR during the forecast period?
Who are the major players in the global virtual goods market?
What are the major market drivers of the virtual goods industry?
What are the major market restraints of the virtual goods industry?
What are the major market opportunities of the virtual goods industry?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Age
- 1.2.1 13-25
- 1.2.2 25-35
- 1.2.3 35-45
- 1.2.4 45+
- 1.3 By Gender
- 1.3.1 Male
- 1.3.2 Female
- 1.4 By Product Type
- 1.4.1 In-game Items
- 1.4.2 Virtual Currency
- 1.4.3 NFTs & Digital Collectibles
- 1.4.4 Virtual Fashion & Wearables
- 1.4.5 Digital Real Estate
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 67.5 billion → 2032: USD 97.52 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Virtual Goods Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Virtual Goods Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Virtual Goods Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Virtual Goods Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Virtual Goods Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Virtual Goods Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Virtual Goods Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Virtual Goods Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 67.5 billion → 2032: USD 97.52 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Virtual Goods Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Age - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 13-25
- 12.3.7.2 25-35
- 12.3.7.3 35-45
- 12.3.7.4 45+
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Gender - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Male
- 12.4.7.2 Female
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 In-game Items
- 12.5.7.2 Virtual Currency
- 12.5.7.3 NFTs & Digital Collectibles
- 12.5.7.4 Virtual Fashion & Wearables
- 12.5.7.5 Digital Real Estate
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Virtual Goods Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Virtual Goods Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Virtual Goods Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Facebook Inc.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Tencent Holdings Ltd.
- 17.4 Zynga Inc.
- 17.5 Gree Inc.
- 17.6 Mixi Inc.
- 17.7 Kabam Inc.
- 17.8 Tagged Inc.
- 17.9 Myspace LLC
- 17.10 hi5 Networks Inc.
- 17.11 Bebo Inc.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

