
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
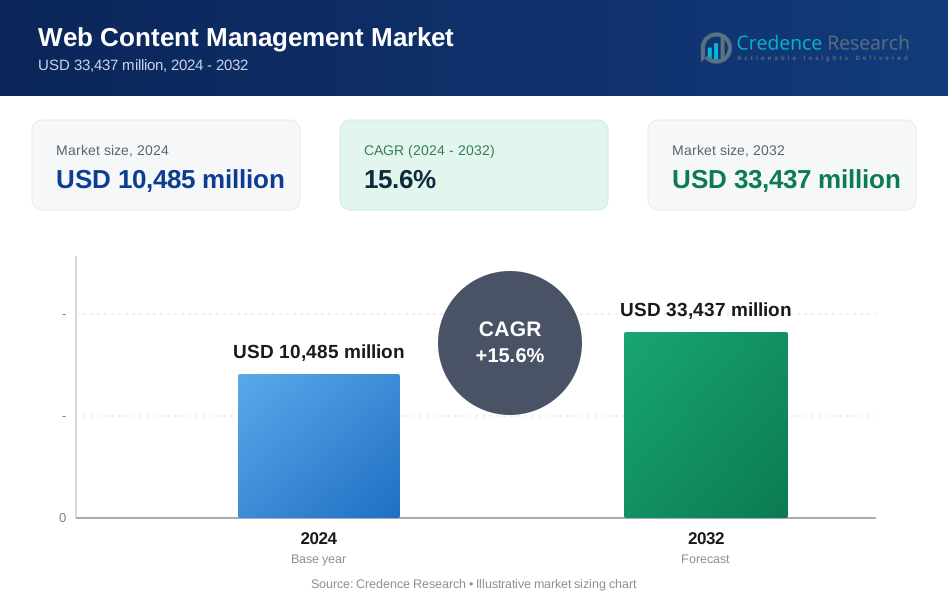
| Web Content Management (WCM) market Size 2024 | USD 10,485 million |
| Web Content Management (WCM) market, CAGR | 15.6% |
| Web Content Management (WCM) market Size 2032 | USD 33,437 million |
Market Overview:
The Web Content Management (WCM) market is projected to grow from USD 10,485 million in 2024 to an estimated USD 33,437 million by 2032, with a compound annual growth rate (CAGR) of 15.6% from 2024 to 2032.
Key drivers of the WCM market include the increasing demand for personalized digital experiences, the rise of e-commerce, and the need for businesses to efficiently manage and distribute content across multiple platforms. As organizations focus on improving customer engagement and brand experience, WCM systems have become essential tools to streamline content creation, editing, and publishing across websites, mobile applications, and social media platforms. Additionally, the growing importance of SEO (Search Engine Optimization) and content optimization to attract and retain customers is propelling the adoption of WCM solutions. Technological advancements in artificial intelligence (AI), machine learning (ML), and automation are enhancing WCM capabilities, enabling more sophisticated content recommendations, real-time analytics, and dynamic content delivery. The integration of AI and ML into WCM platforms is facilitating hyper-personalized content, allowing businesses to tailor experiences to individual users based on their behaviour and preferences. Furthermore, the shift toward headless CMS (Content Management Systems), which offers greater flexibility in delivering content across various channels, is accelerating the demand for advanced WCM solutions.
Regionally, North America and Europe are leading the WCM market due to the high concentration of technology-driven businesses and early adoption of digital transformation strategies. The United States, in particular, is seeing significant growth as businesses prioritize delivering seamless and personalized digital experiences to their customers. In Asia Pacific, countries like China, India, and Japan are experiencing rapid growth, driven by the digital transformation of industries, increasing internet penetration, and the rise of e-commerce. The Middle East & Africa and Latin America are also contributing to the market expansion as businesses in these regions recognize the importance of effective content management for improving customer engagement and driving business growth.
Market Drivers:
Rising Demand for Personalized Digital Experiences:
As businesses continue to recognize the importance of customer engagement, personalized digital experiences have become a primary focus. In response, companies are leveraging WCM systems to enhance the delivery of tailored content across digital channels. Consumers now expect unique, customized experiences based on their individual preferences and behaviour. This demand has intensified with the rise of AI-driven personalization technologies. For instance, a report from the World Economic Forum (WEF) indicates that over 70% of global consumers expect businesses to offer personalized experiences. To meet this demand, companies are increasingly adopting WCM platforms that integrate AI and machine learning technologies for content optimization. Companies such as IBM and Adobe have highlighted the importance of hyper-personalized content in improving user satisfaction, customer loyalty, and overall business performance. For example, Adobe Experience Manager reports that companies using personalized digital experiences see a 30% increase in conversion rates compared to those that do not. Additionally, McKinsey & Company states that 71% of consumers expect companies to deliver personalized interactions, which are pushing businesses to adopt advanced WCM solutions to remain competitive. WCM systems enable businesses to manage content dynamically and present it in a way that resonates with individual customer profiles, enhancing both engagement and sales.
Expansion of E-Commerce and Digital Channels:
The rapid growth of e-commerce and digital commerce has significantly influenced the demand for robust content management solutions. As e-commerce platforms become more complex and demand more diverse content, businesses are increasingly turning to WCM to manage and distribute content efficiently across multiple digital touchpoints, including websites, mobile apps, social media, and other emerging platforms. The World Bank reports that the global e-commerce market reached a value of over $4.9 trillion in 2021, with projections showing continued growth in the coming years. This expansion requires advanced content management tools that can support vast quantities of digital assets while ensuring consistent user experiences across platforms. As e-commerce continues to evolve, WCM solutions will play a central role in enabling businesses to manage large volumes of content seamlessly and at scale. For instance, A study by Forrester Research has also found that 62% of B2B and B2C businesses view omnichannel marketing as critical to their success. WCM platforms enable businesses to ensure content consistency and enhance cross-channel engagement, allowing companies to leverage multiple channels for marketing and sales. As more businesses go digital, the need for integrated WCM solutions will continue to rise, especially among large-scale retailers and e-commerce giants.
Technological Advancements in WCM Systems:
Advancements in AI, machine learning, and cloud-based technology are driving significant innovations within the WCM space. The integration of these technologies into WCM systems allows businesses to deliver more sophisticated content management solutions, from automated content creation and curation to real-time analytics and personalized recommendations. Gartner highlights that AI-enabled WCM systems improve content management by automating routine tasks and providing businesses with actionable insights based on user behavior. These advancements enable more accurate content delivery, ultimately improving customer experience and engagement. For example, SAP and Microsoft have incorporated AI-powered content tools into their WCM offerings, allowing businesses to personalize content at scale and reduce manual intervention. According to a report by IDC, global spending on AI systems is expected to reach $98 billion by 2023, with a substantial portion allocated to AI-driven content management solutions. The continuous evolution of AI and ML technologies in WCM solutions helps businesses stay ahead of the curve by providing real-time analytics, predictive content recommendations, and more dynamic content distribution across channels. Cloud computing has also significantly impacted the WCM market, with businesses increasingly adopting cloud-based WCM platforms to manage content remotely. For instance, Microsoft Azure and Amazon Web Services (AWS) report that more than 60% of enterprises have adopted cloud technology, providing businesses with the flexibility to manage content across multiple regions and devices. This trend is expected to continue as cloud-based WCM systems offer scalability, reduced IT costs, and enhanced collaboration among geographically dispersed teams.
Regulatory Pressures and Data Compliance:
As governments around the world enact more stringent data protection and privacy regulations, businesses are increasingly turning to WCM solutions to ensure compliance and protect consumer data. Regulations such as the General Data Protection Regulation (GDPR) in the European Union and the California Consumer Privacy Act (CCPA) in the United States are driving companies to adopt systems that can handle and secure user data more effectively. For instance, the European Commission reports that since the implementation of the GDPR in 2018, organizations have faced substantial fines for non-compliance, with some penalties reaching up to €20 million or 4% of annual turnover. As businesses strive to meet these regulatory requirements, WCM platforms are being upgraded to include features that allow for better data management, consent tracking, and security. The IMF also highlights that businesses with operations in multiple jurisdictions must comply with various national data protection laws. For companies operating across borders, WCM systems that offer robust compliance features, such as encryption and data access controls, are essential to mitigate the risk of regulatory fines and protect sensitive customer information. As data privacy concerns become more prevalent, regulatory authorities are expected to introduce even stricter rules regarding content management and data use, further driving the need for secure and compliant WCM platforms. This regulatory push is particularly strong in industries such as healthcare, finance, and government, where sensitive data management is critical.
Market Trends:
Integration of AI and Automation in Content Management:
AI and automation are becoming central to WCM systems as businesses look for more efficient ways to manage content at scale and personalize digital experiences. AI-powered features such as content recommendation engines, automated tagging, and predictive analytics are revolutionizing how content is created, delivered, and optimized. By automating routine tasks and leveraging data-driven insights, businesses can improve their content strategies, enhance customer engagement, and streamline content workflows. For example, McKinsey & Company highlights that AI and automation are transforming industries by enabling faster decision-making and improving operational efficiencies. In the WCM context, AI-driven tools are helping businesses generate content faster and more accurately, reducing manual input and improving user experience. Companies are using AI to automatically personalize content based on user behavior, such as tailoring website experiences based on location, browsing history, and past interactions. This is helping businesses achieve higher conversion rates and more efficient content delivery. In addition, Gartner notes that businesses adopting AI in content management are seeing substantial improvements in customer engagement metrics. By incorporating natural language processing (NLP) and machine learning into their WCM solutions, companies are better able to understand and predict customer preferences, creating more personalized and relevant content at scale.
Shift Toward Headless and API-First CMS Models:
Another key trend is the growing preference for headless and API-first Content Management Systems (CMS). Traditional CMS solutions are monolithic, meaning they combine both the content and its presentation in one system. However, businesses are increasingly adopting headless CMS, which separates the content management backend from the frontend presentation layer, allowing for greater flexibility in delivering content across a wide variety of platforms and devices. This trend is particularly important as organizations embrace an omnichannel approach, where content must be delivered consistently across websites, mobile apps, IoT devices, and even emerging technologies like voice assistants. According to a report by Forrester Research, over 50% of enterprises have already begun adopting headless CMS architectures or are in the process of doing so. This shift is driven by the need for businesses to manage content more dynamically across multiple platforms while offering unique and tailored user experiences. Headless CMS solutions allow businesses to push content to multiple touchpoints without being restricted by a single frontend system, thus enabling more agile content delivery. Furthermore, the World Bank reports that industries such as retail, media, and finance are increasingly leveraging API-first architectures to ensure their WCM systems can scale with the evolving demands of omnichannel marketing. By using APIs, companies can integrate their CMS with other business-critical systems, such as CRM and ERP platforms, improving operational efficiency and delivering a unified customer experience.
Market Challenge Analysis:
Complex Integration and Legacy Systems:
One of the primary challenges in the Web Content Management (WCM) market is the difficulty of integrating WCM solutions with legacy systems and other enterprise software. Many businesses, especially larger organizations, still rely on older IT infrastructures and software solutions that were not designed to work with modern, flexible WCM platforms. These legacy systems may include customer relationship management (CRM), enterprise resource planning (ERP), and other back-end tools that are critical to business operations. Integrating a new WCM system into such complex environments can be resource-intensive, time-consuming, and costly. For instance, according to a report by McKinsey & Company, 70% of digital transformation projects fail due to poor integration between new technologies and existing systems. The challenge lies in ensuring that content is seamlessly distributed across multiple digital touchpoints, such as websites, mobile applications, and social media platforms, while maintaining operational continuity. Companies may also struggle with data synchronization issues, content migration, and adapting to new workflows that come with a modern WCM solution. This often results in slower implementation times, increased costs, and reduced ROI on WCM investments. As organizations look to integrate WCM systems with other enterprise applications, they must address technical and organizational challenges, such as system compatibility, employee training, and change management.
Data Privacy and Regulatory Compliance:
Another significant challenge facing the WCM market is the increasing complexity of data privacy regulations and compliance requirements. As governments around the world impose stricter data protection laws, businesses must ensure that their WCM systems comply with these regulations. In particular, laws such as the General Data Protection Regulation (GDPR) in Europe and the California Consumer Privacy Act (CCPA) in the United States place heavy burdens on businesses regarding the collection, processing, and storage of customer data. For instance, the European Commission reports that GDPR compliance has become a critical issue for businesses operating in Europe. The regulation requires companies to obtain explicit consent from users before collecting their personal data and gives users the right to request data deletion. WCM systems must, therefore, be capable of managing user consent, tracking data usage, and ensuring that content is stored securely and in compliance with the law. Similarly, businesses that operate in multiple regions face the challenge of navigating the complexities of varying regional regulations. Non-compliance can result in severe fines, legal consequences, and damage to a company’s reputation. According to PwC, nearly 60% of organizations experienced challenges in aligning their digital systems with data privacy requirements, making compliance a significant obstacle for many businesses. As a result, WCM solutions are increasingly being required to integrate advanced data protection features, such as encryption, consent management tools, and data access controls, to ensure compliance with these evolving regulations. These two challenges—complex system integration and regulatory compliance—are major roadblocks to the seamless adoption of WCM solutions. To overcome these obstacles, businesses need to invest in modern, flexible systems that can integrate well with legacy software and stay ahead of regulatory changes.
Market Segmentation Analysis:
By Type
The WCM market is primarily divided into two types: traditional and headless CMS. Traditional CMS solutions offer a monolithic, integrated structure for managing both content and its presentation. These systems are well-suited for businesses seeking an all-in-one solution for website management. On the other hand, headless CMS is gaining traction due to its flexibility, allowing content to be delivered across multiple channels and devices without being tied to a specific frontend. This type supports more agile content delivery, which is especially beneficial for organizations with a diverse digital ecosystem.
By Technology
The technology segment includes various tools and features integrated into WCM systems. Key technological advancements driving the market include artificial intelligence (AI), machine learning (ML), and automation. AI and ML enable businesses to offer personalized content recommendations and optimize content strategies. Additionally, cloud-based WCM solutions are gaining popularity due to their scalability and ease of integration, allowing businesses to manage content efficiently across multiple platforms. The increasing adoption of mobile-optimized and omnichannel delivery models also contributes to the market’s technological evolution.
By End-User
The end-user segment of the WCM market includes various industries such as retail, media and entertainment, BFSI (banking, financial services, and insurance), healthcare, and government. Retailers and e-commerce companies are major adopters of WCM solutions, seeking to provide personalized experiences and streamline online transactions. The media and entertainment sectors rely on WCM to manage vast amounts of content, including articles, videos, and other digital assets. Healthcare organizations and government entities use WCM to maintain public-facing websites, deliver content efficiently, and meet regulatory requirements. Each industry has specific needs that drive the adoption of tailored WCM systems, often incorporating AI, automation, and advanced analytics.
Segmentation:
Based on Product Type:
- Traditional CMS
- Headless CMS
Based on Technology:
- Artificial Intelligence (AI) Integrated Solutions
- Machine Learning (ML) Powered Solutions
- Cloud-Based Solutions
- On-Premise Solutions
- Mobile Optimized Solutions
- Omnichannel Delivery Solutions
Based on End-User:
- Retail
- E-commerce
- Media and Entertainment
- BFSI (Banking, Financial Services, and Insurance)
- Healthcare
- Government
- Education
- Manufacturing
Based on Region:
- North America: United States, Canada
- Europe: Germany, France, United Kingdom, Spain, Italy
- Asia Pacific: China, India, Japan, South Korea, Australia
- Latin America: Brazil, Mexico, Argentina
- Middle East & Africa: Saudi Arabia, United Arab Emirates, South Africa, Egypt
Regional Analysis:
North America
North America is the largest and most mature market for Web Content Management (WCM) solutions, commanding a significant share of the global market. The region benefits from a robust digital ecosystem, with a high concentration of technology-driven businesses, advanced infrastructure, and widespread adoption of digital transformation strategies. As of the latest data, North America holds approximately 40% of the global WCM market share. This dominance is driven by large enterprises across various industries such as retail, media, and finance, where personalized digital experiences and seamless content delivery are critical to maintaining competitive advantage. The United States, in particular, is a key market in North America due to its large number of technology companies, digital agencies, and multinational corporations. The country is home to many early adopters of WCM technologies, particularly those involving artificial intelligence (AI), machine learning (ML), and cloud-based platforms. Gartner reports that over 60% of North American businesses are investing heavily in AI-driven content management to enhance personalization and improve customer experience. Additionally, businesses in this region are adopting headless CMS and API-first solutions to better manage and distribute content across multiple digital channels. As companies seek to optimize customer engagement through omnichannel strategies, the demand for flexible, scalable WCM platforms continues to rise. Regulatory factors, such as the California Consumer Privacy Act (CCPA), also contribute to the region's WCM market growth. With increasing concerns over data privacy and user consent, businesses in North America are prioritizing compliance through WCM solutions that provide robust data protection features, including encryption, consent management, and secure content storage.
Europe
Europe is another key region for WCM growth, holding an estimated 30% of the global market share. This region is experiencing steady growth driven by digital transformation initiatives, with a focus on customer-centric content delivery and regulatory compliance. European businesses are particularly focused on personalization, as consumers demand more relevant and engaging content across digital platforms. The adoption of AI and automation in WCM systems is also gaining momentum in Europe, as companies seek to streamline content workflows and enhance user experience. The European Union's General Data Protection Regulation (GDPR) has significantly impacted the adoption of WCM solutions in the region. Companies are increasingly seeking WCM platforms that can ensure compliance with GDPR’s strict data privacy and security requirements. According to The European Commission, businesses are under constant pressure to secure user data, implement transparent data collection practices, and offer users the right to opt-out of data collection processes. Consequently, WCM platforms that integrate robust consent management and data protection features are in high demand. Countries like the United Kingdom, Germany, and France lead the charge in digital content management adoption, driven by both large enterprises and small-to-medium-sized businesses (SMBs) undergoing digital transformation.
Asia Pacific
Asia Pacific (APAC) is one of the fastest-growing regions for WCM, accounting for approximately 20% of the global market share, with significant growth expected in the coming years. The region's rapid digital transformation, expanding internet penetration, and increasing adoption of mobile and e-commerce platforms are driving demand for advanced WCM solutions. Countries like China, India, Japan, and Australia are at the forefront of this growth, with digital-native businesses and large enterprises investing heavily in WCM technologies to enhance customer engagement and support omnichannel marketing strategies. China and India are experiencing rapid growth in internet users and mobile penetration, contributing to the increased demand for dynamic and scalable WCM solutions. E-commerce and online retail are particularly important sectors, as businesses in these countries seek to deliver personalized digital content to a growing base of online consumers. According to the World Bank, the e-commerce market in Asia is expected to grow at an accelerated pace, further driving the need for efficient content management systems that can support large-scale content creation, distribution, and optimization. In Japan, the adoption of AI-driven WCM technologies is growing, as companies seek to enhance user experiences with personalized content and improve operational efficiency. Japanese companies are increasingly utilizing cloud-based and headless CMS platforms to ensure faster content delivery across multiple digital touchpoints, including websites, mobile apps, and smart devices. While Australia has a well-established digital landscape, emerging markets in Southeast Asia, such as Vietnam and Indonesia, are also seeing rapid adoption of WCM solutions, particularly in retail and e-commerce sectors. The APAC region’s digital growth is expected to continue to outpace other regions, driven by increased investment in e-commerce, mobile applications, and AI-powered content strategies. As businesses across Asia Pacific continue their digital transformation journeys, the demand for advanced WCM platforms that can manage vast volumes of content and ensure personalized, multichannel experiences will continue to rise.
Key Player Analysis:
- Adobe (US)
- OpenText (Canada)
- Microsoft (US)
- Oracle (US)
- Automattic (US)
- OpenAI (US)
- Canva (US)
- RWS (UK)
- Progress (US)
- HubSpot (US)
Competitive Analysis:
The Web Content Management (WCM) market is highly competitive, with several key players offering a variety of solutions tailored to meet the diverse needs of businesses across industries. Major companies like Adobe, SAP, Oracle, and Sitecore dominate the market by providing robust, integrated WCM platforms that combine content creation, management, and delivery capabilities with advanced features such as personalization, analytics, and artificial intelligence. These industry leaders focus on offering scalable solutions for large enterprises and multinational organizations, helping them manage complex, multichannel digital experiences. Smaller, emerging players are gaining traction by offering more flexible, cloud-based, and cost-effective alternatives, such as Contentful and Kentico, which cater to the needs of medium-sized businesses and those looking for headless CMS options. The shift toward headless and API-first architectures is increasingly becoming a point of differentiation, as businesses seek more flexibility in delivering content across various platforms. Companies are also investing in AI and machine learning technologies to enhance content recommendations, personalization, and automated content workflows, which has become a major competitive edge. Furthermore, regional players in Asia Pacific and Europe are also making their mark by focusing on specific local needs, offering customized solutions that comply with regional data privacy regulations. The competitive landscape remains dynamic, with companies continuously innovating and adapting to the evolving demands for omnichannel content management, personalization, and integration with other enterprise technologies, creating a highly fragmented and rapidly evolving market.
Recent Developments:
- In September 2024, Progress announced its agreement to acquire ShareFile, a SaaS-native, AI-powered collaboration platform from Cloud Software Group. ShareFile specializes in document-centric collaboration for businesses in sectors such as business services, financial services, healthcare, and construction.
- In July 2024, Lumen Technologies and Microsoft formed a partnership to accelerate Lumen’s digital transformation through the Microsoft Cloud. Microsoft also selected Lumen to expand its network capacity to meet the growing demand for data center services, driven by advancements in AI.
- In June 2024, RWS launched HAI, a new digital self-service platform that combines AI-powered technology with linguistic expertise to deliver quick, easy, and secure content translation. This platform offers high-quality professional translations online, simplifying market entry and removing barriers to global expansion.
- In March 2024, Adobe and Microsoft collaborated to integrate the workflows and insights of Adobe Experience Cloud with Microsoft Copilot for Microsoft 365. This partnership connects applications and data silos, enabling timely marketing insights and streamlining workflows in products such as Outlook, Microsoft Teams, and Word, enhancing tasks from content creation to approval and delivery.
Market Concentration & Characteristics:
The Web Content Management (WCM) market exhibits moderate to high concentration, with a few large players commanding a significant share, while numerous smaller vendors cater to niche needs and specialized markets. Major industry leaders like Adobe, SAP, Oracle, and Sitecore dominate the market, offering comprehensive, enterprise-grade WCM platforms that provide end-to-end solutions for content creation, management, and distribution across multiple channels. These companies typically target large enterprises and multinational organizations that require robust, scalable systems capable of managing complex digital ecosystems. Their platforms often integrate advanced features such as AI-powered personalization, real-time analytics, and cloud-based deployment options, providing significant differentiation through technological innovation. However, the market also sees strong competition from mid-tier and emerging vendors, such as Contentful, Kentico, and Acquia, which offer more flexible, cost-effective solutions aimed at small and medium-sized businesses (SMBs) or those seeking headless CMS options. These solutions often focus on ease of use, affordability, and integration with other digital tools, making them attractive to businesses looking for agile, customizable WCM systems. The shift towards headless CMS and API-first models is reshaping the market, with new entrants capitalizing on this trend to offer lightweight, adaptable solutions for delivering content across digital platforms. Regionally, companies are increasingly focusing on localized solutions that comply with regional regulations, such as GDPR in Europe or data privacy laws in Asia. As the market continues to mature, there is a growing emphasis on personalization, AI, and automation, making technological innovation a key characteristic of both leading and emerging WCM vendors.
Report Coverage:
This report provides a comprehensive analysis of the global Web Content Management (WCM) market, offering insights into key market dynamics, trends, and competitive factors shaping the industry. It covers the market's segmentation by product type, technology, and end-user, exploring the demand for WCM solutions across different industries, including retail, healthcare, finance, and media. The report also examines the regional landscape, analyzing market share and growth potential in North America, Europe, Asia Pacific, and other key regions. Key drivers such as the increasing demand for personalized digital experiences, the rise of e-commerce, and advancements in artificial intelligence and automation are explored in detail, along with the challenges posed by system integration complexities and data privacy regulations. Additionally, the report highlights emerging trends like the shift towards headless CMS and API-first architectures, as well as the growing focus on omnichannel content delivery. The competitive landscape is thoroughly analyzed, including detailed profiles of major players like Adobe, SAP, Oracle, and Sitecore, as well as smaller, innovative vendors offering flexible and cost-effective solutions. Market share data and strategic insights are provided to help stakeholders understand the current market scenario and anticipate future developments. By offering a data-driven analysis of both established and emerging markets, this report serves as an essential resource for businesses, investors, and decision-makers looking to navigate the rapidly evolving WCM landscape.
Future Outlook:
- The Web Content Management (WCM) market is driven by the increasing demand for personalized digital experiences across industries.
- E-commerce growth is a key factor, as businesses seek efficient content management solutions to enhance customer engagement.
- WCM systems help organizations streamline content creation, editing, and publishing across websites, mobile applications, and social media platforms.
- The need to improve SEO and optimize content for search engines is pushing businesses to adopt advanced WCM solutions.
- Integration of artificial intelligence (AI) and machine learning (ML) into WCM platforms is enabling more sophisticated content recommendations and dynamic content delivery.
- AI-powered WCM systems allow for real-time analytics, providing valuable insights into customer behavior and content performance.
- Hyper-personalized content is becoming increasingly important, allowing businesses to tailor digital experiences based on individual preferences.
- The shift toward headless CMS platforms is empowering businesses to deliver content seamlessly across multiple channels and devices.
- Digital transformation initiatives are accelerating the adoption of WCM solutions, particularly in North America, Europe, and Asia Pacific.
- As businesses in emerging markets recognize the value of effective content management, regions like Latin America, the Middle East, and Africa are contributing to the overall market growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Web Content Management (WCM) market?
What are the key factors driving the growth of the WCM market?
How is artificial intelligence (AI) influencing the WCM market?
What role does headless CMS play in the growth of the WCM market?
Which regions are seeing the fastest growth in the WCM market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Web Content Management Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Web Content Management Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 10,485 million → 2032: USD 33,437 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Web Content Management Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Web Content Management Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Web Content Management Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Web Content Management Market Drivers
- 3.3 Web Content Management Market Restraints & Challenges
- 3.4 Web Content Management Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Web Content Management Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Web Content Management Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Web Content Management category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Web Content Management Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Web Content Management Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Web Content Management market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Web Content Management Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Web Content Management Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Web Content Management Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Web Content Management (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Web Content Management Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Web Content Management Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Web Content Management Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Web Content Management Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Web Content Management Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Web Content Management Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Web Content Management Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Web Content Management Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Web Content Management Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
