
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Zinc Oxide Market Size 2024 | USD 4,444.27 Million |
| Zinc Oxide Market, CAGR | 5.47% |
| Zinc Oxide Market Size 2032 | USD 7,196.53 Million |
Market Overview
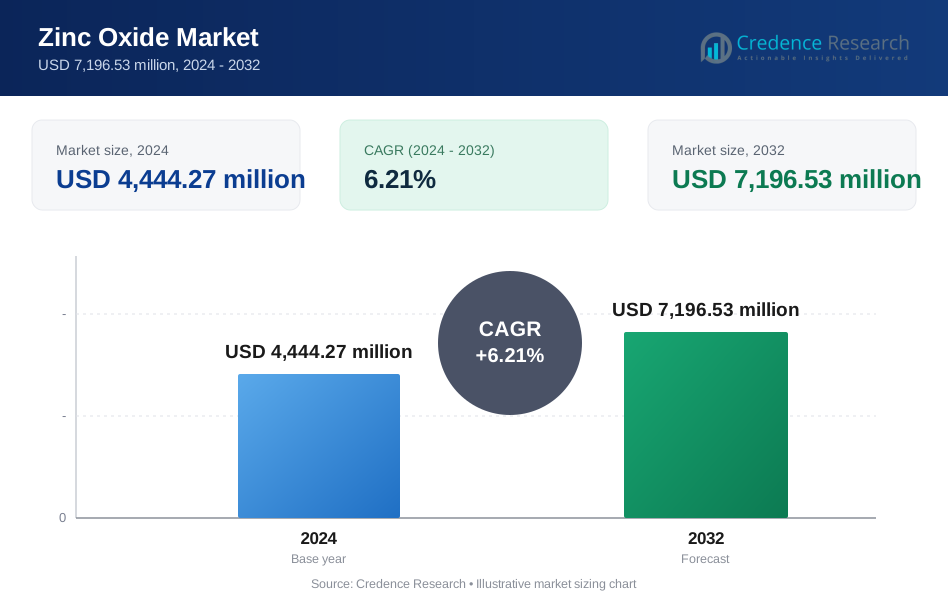
The Zinc Oxide Market is projected to grow from USD 4,444.27 million in 2024 to USD 7,196.53 million by 2032, reflecting a compound annual growth rate (CAGR) of 6.21%.
The Zinc Oxide Market is driven by increasing demand across various industries, including rubber, ceramics, and cosmetics, where it is used for its protective and reinforcing properties. The growing awareness of skin protection and the rise in demand for sunscreens and cosmetics with UV protection are boosting the market. Additionally, advancements in nanotechnology are expanding the applications of zinc oxide in electronics and healthcare. The market is also benefiting from the rising focus on sustainable and eco-friendly materials, as zinc oxide plays a key role in green chemistry and renewable energy applications.
The Zinc Oxide market exhibits significant geographical diversity, with major regions including North America, Europe, Asia-Pacific, and Latin America. Asia-Pacific dominates the market, driven by robust industrial activities in China and India. North America and Europe also hold substantial shares due to the demand from the automotive and cosmetics sectors. Key players in the Zinc Oxide market include companies like Zinc Oxide LLC, Grupo Promax, Rubamin, and J.G. Chemicals, which are known for their strong market presence and extensive product portfolios. These companies are focused on innovation and expanding their production capacities to meet global demand.
Market Drivers
Construction and Building Industry Boom
The Zinc Oxide Market is experiencing significant growth due to the booming construction and building industry. For instance, the market size of the U.S. construction sector was valued at nearly two trillion U.S. dollars in 2023, and it is expected to keep rising in the next couple of years. Governments around the world are heavily investing in infrastructure development, which is driving demand for zinc oxide in various applications such as cement, paints, and other construction materials. The rapid pace of urbanization, particularly in emerging economies, is leading to an increase in construction activities, further boosting the demand for zinc oxide-based products. This trend is expected to continue as urban populations grow and the need for residential and commercial infrastructure expands, making zinc oxide a critical component in the construction sector.
Rubber Industry Expansion
The expansion of the rubber industry, particularly in tire manufacturing, is another major driver of the Zinc Oxide Market. Zinc oxide plays a crucial role in the vulcanization process of rubber, which is essential for producing durable and high-performance tires. Global tire production reached 2.4 billion units in 2021. In the US alone, tire manufacturing shipments were valued at $17.3 billion in 2022. The automotive industry's growth directly impacts zinc oxide usage, with global vehicle production expected to reach 97 million units by 2025. The increasing production of vehicles, driven by consumer demand and economic growth, directly impacts the need for zinc oxide, making it a vital material in the rubber industry.
Personal Care and Cosmetics Industry Growth
The personal care and cosmetics industry is also contributing significantly to the growth of the Zinc Oxide Market. Zinc oxide is widely used in sunscreens due to its excellent UV-blocking properties, which are essential for protecting the skin from harmful rays. Additionally, its anti-inflammatory and soothing properties make it a popular ingredient in various skincare products. As consumers become more aware of the importance of sun protection and skin health, the demand for zinc oxide in these products is expected to increase, driving market growth.
Pharmaceutical Industry Advancements
Advancements in the pharmaceutical industry are further enhancing the demand for zinc oxide. Known for its antiseptic and wound healing properties, zinc oxide is used in a variety of pharmaceutical formulations, including creams, ointments, and powders. Its biocompatibility also makes it an important component in drug delivery systems, where it helps in the effective delivery of medications. As the pharmaceutical industry continues to innovate and develop new treatments, the use of zinc oxide is expected to grow, supporting its market expansion across multiple healthcare applications.
Market Trends
Sustainability and Environmental Focus
The Zinc Oxide Market is witnessing a significant shift towards sustainability and environmental responsibility. For instance, a survey by the International Zinc Association found that 78% of zinc oxide producers have implemented sustainability initiatives in their manufacturing processes. As global awareness of environmental issues grows, the industry is increasingly adopting eco-friendly production methods to minimize its carbon footprint and reduce environmental impact. This trend is particularly evident in the development of zinc oxide-based products with green attributes, such as those made from sustainable raw materials or through processes that consume less energy and generate fewer emissions. Companies are also focusing on reducing waste and improving the recyclability of zinc oxide products, aligning with the broader movement towards sustainability. The demand for these eco-friendly zinc oxide products is gaining traction, especially among environmentally conscious consumers and industries that are under pressure to meet stringent environmental regulations. This focus on sustainability is not only enhancing the market’s appeal but also driving innovation as companies seek to develop new, environmentally friendly applications for zinc oxide.
Nano Zinc Oxide and Product Innovation
Nano zinc oxide is emerging as a transformative trend in the Zinc Oxide Market, offering enhanced properties that surpass those of conventional zinc oxide. With its smaller particle size, nano zinc oxide provides superior UV protection, increased transparency in cosmetics, and enhanced antimicrobial effects, making it highly desirable in industries such as personal care, electronics, and healthcare. The unique characteristics of nano zinc oxide are opening up new opportunities across various sectors, as manufacturers explore its potential in applications ranging from sunscreens to advanced electronic devices. Simultaneously, product innovation continues to drive market growth, with companies developing value-added zinc oxide products that offer specialized functionalities tailored to specific customer needs. This includes customized solutions for niche markets, such as zinc oxide with enhanced thermal stability for high-performance rubber or coatings with improved weather resistance. These innovations not only differentiate products in a competitive market but also enable companies to cater to the evolving demands of consumers and industries.
Market Challenges Analysis
Supply Chain Disruptions and Competition
Global supply chain disruptions and intense competition are additional challenges impacting the Zinc Oxide Market. For instance, in Q2 2024, the North American Zinc Oxide market experienced a notable increase in prices, driven primarily by supply chain disruptions and augmented demand dynamics. Supply chain issues, such as delays in raw material sourcing, logistical bottlenecks, and transportation inefficiencies, can significantly hinder production schedules and lead to increased costs. These disruptions are often exacerbated by geopolitical factors, including trade tensions, tariffs, and regional conflicts, which can further destabilize supply chains and create uncertainty in the market. In addition to supply chain challenges, the market is characterized by fierce competition from both domestic and international players. This intense competition makes it increasingly difficult for companies to differentiate their zinc oxide products, especially in a market where many offerings are commoditized. As a result, companies are under constant pressure to innovate, reduce costs, and enhance product quality to maintain or grow their market share.
Health and Safety Concerns and Technological Advancements
Health and safety concerns also present significant challenges for the Zinc Oxide Market. The production of zinc oxide involves handling materials that can pose occupational hazards, particularly in the form of zinc oxide dust, which can cause respiratory issues if not properly managed. Ensuring a safe working environment requires strict adherence to safety protocols, investment in protective equipment, and ongoing training for workers. Additionally, product safety is paramount, as any issues with the safety of zinc oxide-based products can damage consumer trust and lead to costly recalls or legal actions. On the technological front, the rapid pace of advancements poses a dual challenge. While innovation is essential for staying competitive, it also carries the risk of product obsolescence, where existing products may quickly become outdated in the face of newer, more advanced alternatives. To remain at the forefront of the market, companies must continuously invest in research and development, which can be a significant financial burden, particularly for smaller firms with limited resources.
Market Segmentation Analysis:
By Grade:
The Zinc Oxide Market is segmented into Industrial, Pharma, and Food grades, each catering to specific industry needs. The Industrial grade dominates the market due to its extensive use in rubber manufacturing, particularly in tire production, as well as in ceramics, paints, and coatings. The Pharma grade, though smaller in volume, is essential for its application in pharmaceutical products, such as ointments and creams, due to its antiseptic and healing properties. The Food grade is used in fortifying foods and supplements, contributing to human health by providing essential zinc nutrients. The diverse applications across these grades ensure steady demand across various sectors, driving overall market growth.
By Process:
The market is further segmented by process type into Wet Chemical, Indirect, and Direct processes. The Wet Chemical process is widely adopted due to its ability to produce high-purity zinc oxide, which is crucial for applications in pharmaceuticals, cosmetics, and food products. The Indirect process, also known as the French process, is primarily used in the production of zinc oxide for rubber and ceramics, offering high-quality and fine-particle zinc oxide. The Direct process, or American process, is used for producing zinc oxide with lower purity, suitable for industrial applications where high precision is not critical. The choice of process depends on the specific application requirements, influencing the quality and cost-effectiveness of the final product.
Segments:
Based on Grade:
- Industrial
- Pharma
- Food
Based on Process:
- Wet Chemical
- Indirect
- Direct
Based on Application:
- Rubber
- Ceramics
- Chemicals
- Cosmetics and Personal Care
- Paints & Coatings
- Pharmaceuticals
- Agricultural
Based on the Geography:
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis
Asia-Pacific
Asia-Pacific currently dominates the market, commanding approximately 45% of the global share. This leadership position is attributed to the region's robust manufacturing sector, particularly in countries like China, India, and Japan. The region's market is characterized by high demand from various industries, including rubber production, ceramics, electronics, and personal care products. China, in particular, stands out as both the largest producer and consumer of zinc oxide globally, significantly influencing market dynamics. The rapid industrialization, increasing urbanization, and growing consumer markets in Asia-Pacific continue to fuel the demand for zinc oxide across multiple sectors.
Europe
Europe follows, holding about 25% of the market share. The European market is distinguished by its stringent quality standards and focus on high-purity zinc oxide for specialized applications in pharmaceuticals, cosmetics, and advanced materials. For instance, zinc oxide nanoparticles are excessively used in the pharmaceutical industry, and some medicines contain irreplaceable zinc oxide nanoparticles. Countries like Germany, France, and Italy are key players in the region, with a strong emphasis on research and development to create innovative zinc oxide products.
Key Player Analysis
- Yongchang Zinc Industry Co. Ltd.
- ZM Silesia
- Akrochem
- Zinc Oxide LLC
- Pan Continental Chemical
- Rubamin
- Grupo Promax
- USA Zinc
- G. Chemicals
- Weifang Longda Zinc Industry Co. Ltd.
- Brüggemann
Competitive Analysis
The Zinc Oxide market is highly competitive, with leading players like Zinc Oxide LLC, Rubamin, Grupo Promax, and Pan Continental Chemical playing pivotal roles. Zinc Oxide LLC is a prominent player in North America, known for its extensive product offerings and strong distribution network. Rubamin, based in India, leverages its advanced manufacturing processes and wide geographical reach to maintain a competitive edge. Grupo Promax, with a strong presence in Latin America, focuses on innovation and sustainable production practices to differentiate itself. Pan Continental Chemical, a key player in the Asia-Pacific region, benefits from the growing industrial demand in countries like China and India. These companies continuously invest in R&D, capacity expansion, and strategic partnerships to enhance their market positions and cater to diverse end-use industries. The competitive landscape is marked by the pursuit of technological advancements and sustainability, with companies striving to meet evolving customer demands and regulatory requirements.
Recent Developments
- In March 2024, G. Chemicals raised ₹ 75.35 crore from anchor investors ahead of its initial public offerings (IPO).
- In December 2023, Brüggemann announced the successful establishment of a new chemical manufacturing plant at the Heil¬bronn site. The plant operates on 15,000 metric tons of biomass per year for the heating purpose of the equipment. Brüggemann’s strategy is expected to strengthen its presence in the growing carbon natural manufacturing society, contributing to increased annual performance.
Market Concentration & Characteristics
The Zinc Oxide market is characterized by moderate to high market concentration, with a few key players dominating a significant share of the global market. Companies such as Zinc Oxide LLC, Rubamin, and Grupo Promax have established strong footholds due to their extensive production capacities, advanced technological processes, and broad distribution networks. The market exhibits characteristics of both consolidation and competition, where leading players benefit from economies of scale and established customer bases, while smaller players strive to differentiate through niche applications and regional focuses. The market is also influenced by regulatory standards, particularly regarding environmental sustainability and product quality, which drive innovation and strategic investments. Despite the dominance of major companies, the market remains dynamic, with opportunities for new entrants and regional players to capture market share through technological advancements and by addressing specific industry needs. The competitive nature and concentration of the market underscore its complexity and the strategic importance of innovation and compliance.
Report Coverage
The research report offers an in-depth analysis based on Grade, Process, Application, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for zinc oxide is expected to grow due to its increasing use in the rubber and tire industries.
- Rising applications in the cosmetics and personal care sectors will drive market expansion.
- The market will see growth in the electronics sector, particularly in the production of varistors and surge arresters.
- Environmental regulations will push for the adoption of more sustainable production methods.
- Technological advancements will lead to more efficient and high-purity zinc oxide production processes.
- Asia-Pacific will continue to dominate the market, driven by industrial growth in China and India.
- Increased research and development activities will lead to innovative applications of zinc oxide in new industries.
- The pharmaceutical industry will contribute to market growth due to zinc oxide’s use in ointments and creams.
- Strategic partnerships and acquisitions among key players will shape the competitive landscape.
- The market will experience price fluctuations due to the volatility of raw material costs and supply chain disruptions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Zinc Oxide Market?
What factors are driving the growth of the Zinc Oxide Market?
What are the key segments within the Zinc Oxide Market?
What are some challenges faced by the Zinc Oxide Market?
Who are the major players in the Zinc Oxide Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Zinc Oxide Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Zinc Oxide Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 4,444.27 million → 2032: USD 7,196.53 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Zinc Oxide Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Zinc Oxide Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Zinc Oxide Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Zinc Oxide Market Drivers
- 3.3 Zinc Oxide Market Restraints & Challenges
- 3.4 Zinc Oxide Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Zinc Oxide Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Zinc Oxide Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Zinc Oxide category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Zinc Oxide Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Zinc Oxide Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Zinc Oxide market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Zinc Oxide Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Zinc Oxide Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Zinc Oxide Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Zinc Oxide (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Zinc Oxide Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Zinc Oxide Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Zinc Oxide Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Zinc Oxide Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Zinc Oxide Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Zinc Oxide Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Zinc Oxide Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Zinc Oxide Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Zinc Oxide Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
