
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Drilling Fluids Market Size 2023 | USD 8152.2 Million |
| Drilling Fluids Market, CAGR | 4.60% |
| Drilling Fluids Market Size 2032 | USD 12219.68 Million |
Market Insights
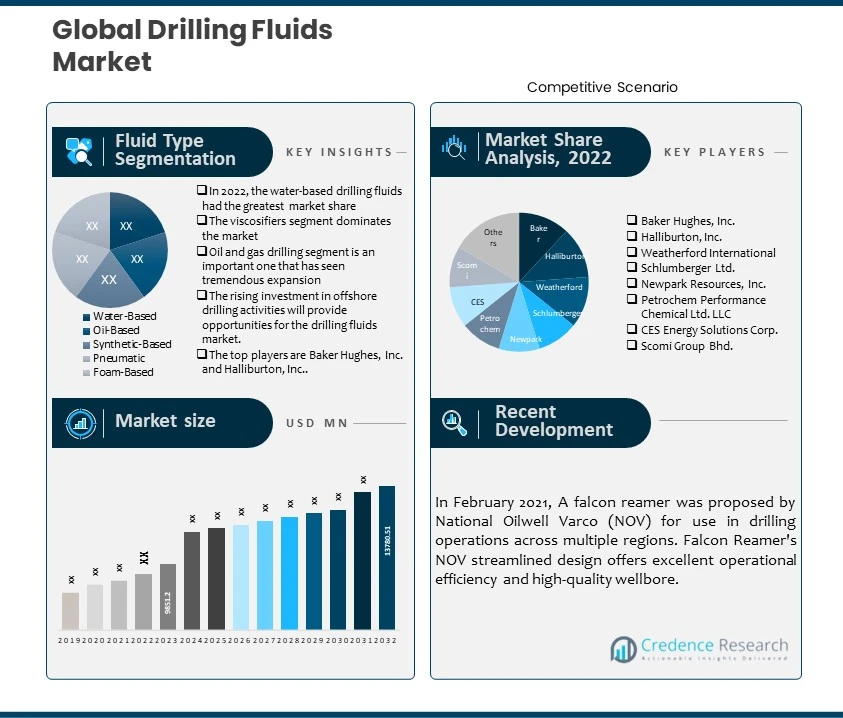
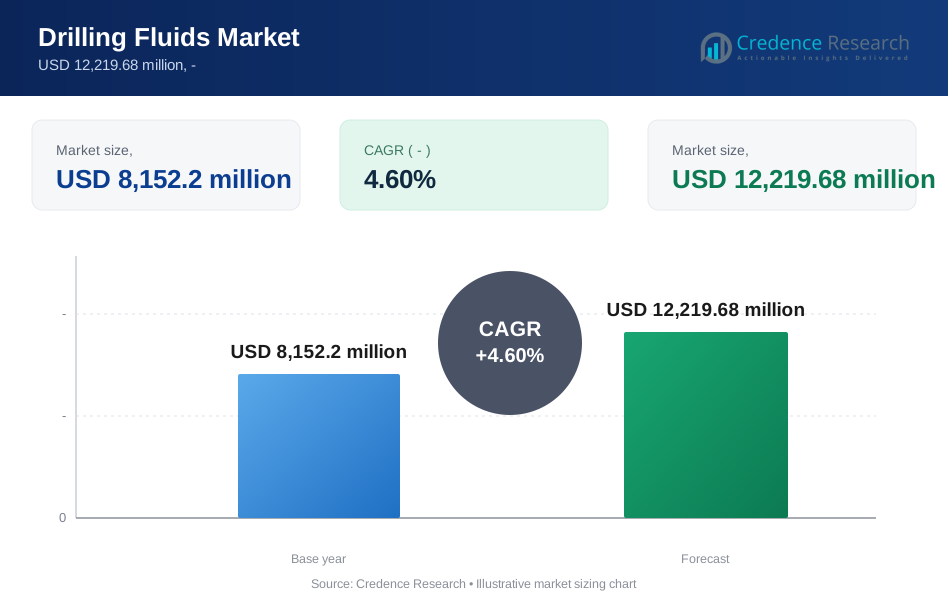
- Between 2024 and 2032, the global drilling fluids market is expected to develop at a compound annual growth rate (CAGR) of 4.60%, from its estimated USD 8152.2 million in 2023 to USD 12219.68 million in 2032.
- The significant fluid type category is water-based drilling fluids. On the other hand, oil-based drilling fluids are expected to grow at a strong CAGR.
- During the forecast period, the viscosifiers are anticipated to have the highest compound annual growth rate.
- The CAGR for oil and gas drilling is expected to be the highest during the projection period.
- North America dominated the drilling fluids market.
- Regarding the market share of drilling fluids, Europe is expected to come second.
- In the drilling fluids market, Asia Pacific is anticipated to grow fastest.
- The primary drivers of the market are the expansion of deepwater and ultra-deepwater drilling projects, the rise in drilling activities within the oil and gas sector, and technological developments in drilling fluid formulations.
- Growing investment in offshore drilling operations, improvements in drilling fluid formulations for challenging environments, and integration of digital technologies for real-time monitoring and optimization are all driving the market's growth.
Executive Summary
Market Definition
The drilling fluids market is related to the industry segment that produces, distributes, and uses fluids for oil and gas extraction drilling as well as other drilling activities like mining and geothermal drilling. Drilling fluids-also referred to as drilling muds-perform a number of crucial tasks during drilling operations, such as cooling, lubricating, transporting cuttings to the surface, preserving wellbore stability, and guarding against formation damage. The market includes a variety of products, such as synthetic-based muds, oil-based muds, water-based muds, and specialty fluids made to meet particular drilling specifications.
Market Overview
The drilling fluids sector is estimated to develop at a 4.60% compound annual growth rate (CAGR) between 2024 and 2032, maintaining its current upward trend. The market will continue to develop, rising from its estimated value of USD 8152.2 million in 2023 to USD 12219.68 million in 2032.
The growing need in the energy sector significantly drives the market for drilling fluids. For oil and gas exploration and production, drilling fluids also referred to as drilling mud, are essential to the drilling process. Exploration and production efforts to find and extract oil and gas reserves are becoming more and more necessary as the world's energy needs continue to rise. Drilling fluids are necessary for these operations because they facilitate the drilling of boreholes, the stability of the wellbore, and the transportation of drill cuttings to the surface. Drilling technology developments have made it possible to access reserves that were previously unreachable, like shale and deepwater formations. This is just one example of how the energy sector is constantly changing. The market for drilling fluids is expanding and experiencing innovation as a result of these sophisticated drilling techniques, which frequently call for customized drilling fluids made for particular geological conditions.
Furthermore, the global growth in offshore and deepwater exploration operations is being driven by the depletion of onshore reserves and developments in offshore drilling technology. These procedures require advanced drilling fluid systems that can survive the high pressures and temperatures seen at depths due to the demanding climatic conditions and complex geological formations involved.
Segmentation by Fluid Type
- Water-based drilling fluids are the market leader by fluid type. The main ingredient is water. As an alternative to oil-based fluids, water is easily accessible, reasonably priced, and ecologically benign. Water is mixed with additives to modify its properties because it might not have all the necessary qualities for drilling to be successful on its own.
- The oil-based drilling fluids category will exhibit a sizable CAGR during the projected period. Drilling fluids used in the oil and gas drilling process are called oil-based drilling fluids or oil-based muds (OBMs). These fluids are made up of different additives, a base oil (usually mineral oil or diesel), and occasionally a tiny bit of water.
- Other fluid types, such as synthetic-based drilling fluids, pneumatic drilling fluids, and foam-based drilling fluids, also contribute to the demand for drilling fluids.
Segmentation by Additive
- The Viscosifiers are more popular in the drilling fluids market. Drilling fluid viscosity can be adjusted with the use of viscosifier additives. The fluid's resistance to flow is known as viscosity, and it is an essential characteristic of drilling operations since it influences a number of different aspects of the process, including hole cleaning, cuttings transport, and hydraulic efficiency.
- The weighting agents category will likely register a significant CAGR during forecasting. Drilling fluids can be made denser by adding materials called weighting agents. This density is required to counteract the pressure from the surrounding formations and the pressure that the fluids in the wellbore exert.
- Fluid loss control agents, emulsifiers and wetting agents, corrosion inhibitors, biocides, surfactants, and fluid pH buffers also contribute to the demand for drilling fluids.
Segmentation by Application
- The oil and gas drilling category is projected to grow at the fastest rate over the projection period. Oil and gas drilling enables the penetration of diverse strata of rock formations, reaching hydrocarbon reservoirs. Drilling fluids facilitate this procedure by supplying hydraulic pressure to drive the drill bit deeper into the earth's crust.
- Other applications, including geothermal drilling, mining and mineral exploration, and civil engineering and construction, also influence the need for drilling fluids.
Segmentation by Region
- North America leads the drilling fluids industry. This is due to the growth in the exploration of shale gas and in the amount of oil and gas drilling activity in North America.
- Europe is estimated to rank second in market size for drilling fluids.
- The drilling fluids industry is predicted to flourish rapidly in Asia Pacific.
- Regions such as Africa, the Middle East, and Latin America cover the remaining requirement for drilling fluids.
Drilling fluids are utilized during the well-drilling process. Because of their density and any additional pressure that may be applied to the fluid column, they offer primary well control of subsurface pressures. Drill cuttings are usually evacuated from the wellbore by rotating them down the drill string, out the bit, and back up the annulus to the surface. Oil and gas exploration requires these fluids as essential components. Water, oil, clay, and other chemicals are mixed to create them. Commonly called drilling muds, they serve multiple purposes during drilling operations, such as lubricating and cooling the drill bit's teeth, transferring drill cuttings to the surface, and decreasing drill pipe jams.
Based on projections, the market for drilling fluids is dominated by North America. North America has led the way in creating and implementing cutting-edge drilling technologies. In order to maximize performance and efficiency, these technologies frequently call for specialized drilling fluids, which has raised demand for such products in the area. Considerable funding has been allocated to the region's drilling fluids research and development. This has made North America even more dominant in the field by encouraging the creation of innovative products that are tailored to the particular needs of the oil and gas operations in the area. When it comes to the exploration and production of oil and gas, North America generally enjoys a more favorable regulatory environment than certain other regions. This promotes growth and investment in the sector, which includes the application of drilling fluids.
The drilling fluids market in Asia Pacific will expand fastest throughout the forecast. The discovery of new reserves and rising energy consumption have led to a boom in oil and gas exploration activities in the Asia Pacific region. This increases the need for these products since it forces the use of drilling fluids to facilitate the drilling process. Infrastructure projects, including building, transportation, and utilities, have increased as a result of the fast industrialization and urbanization of nations like China, India, and Southeast Asia. Drilling fluids are in high demand because many of these projects involve drilling for tunnels, foundations, and other reasons.
Key Highlights of the Report
The global drilling fluids market is segmented by fluid type, additive, application, and region. Regarding the fluid type, water-based drilling fluids are the market spearhead. Viscosifiers represent a noteworthy category. The oil and gas drilling category is anticipated to increase at the highest CAGR throughout the projection period. The drilling fluids market is expanding mostly in North America.
Drilling fluid demand will be driven by the significant global opportunities for well drilling brought about by the robust growth in oil and gas demand. Crude oil production from offshore resources is highest in North America, followed by Saudi Arabia and Russia. In addition, a lot of nations are spending money looking for new resources for the oil and gas industry. Two new crude oil production projects that have produced 200,000 barrels per day, or 12% of the Gulf of Mexico's total oil production, were announced by GOM on April 14, 2021. The growth in crude oil production in the United States Federal Gulf of Mexico (GOM) has been projected by this extensive project.
The North American region is expected to account for the largest drilling fluids market globally. Drilling fluid distribution and transportation to different drilling sites is made easier by North America's well-developed infrastructure and logistical networks, which support the industry's expansion and domination in the area. The Asia Pacific is also assumed to have the market's sharpest growth. An increased focus on using ecologically friendly drilling fluids that minimize ecological impact is a result of growing environmental awareness. In the Asia Pacific region, the use of these fluids is expanding, particularly in environmentally delicate areas.
Which Key Factors Are Driving The Global Drilling Fluids Market?
The primary drivers of the drilling fluids market are the growth of offshore drilling operations, the increase in demand for horizontal drilling techniques, and the preference for using water-based drilling fluids over oil-based ones.
What Are The Main Challenges Confronting The Drilling Fluids Market Globally?
The primary barriers impeding the global drilling fluids industry's growth are the high upfront costs, scarcity of skilled labor, disruptions in the supply chain, and declining investment in offshore drilling projects.
What Market Opportunities Exist For Drilling Fluids Globally?
The potential for the drilling fluids market is being driven by an increased emphasis on shale gas production and exploration, an expansion of drilling operations into emerging markets, and an emphasis on improving wellbore stability and integrity.
Market Drivers
Multiple factors propel the drilling fluids industry across the globe. The primary factors propelling the global drilling fluids market are as follows:
Growing Investment in Shale Gas
The increasing focus on lowering carbon emissions and the growing need for gas-fired power generation technology are two of the factors propelling the growth of the global shale gas sector. Canada, India, and Germany are just a few of the nations concentrating on utilizing their resources for shale gas exploration. The International Energy Agency (IEA) projects that by 2035, gas will have risen from its current percentage of 23% to 25% of the world's energy mix, surpassing coal's 24% to become the second-largest primary energy source after oil (27%). Because of its many advantages, shale gas-fired power generation is growing in the United States. 2020 saw a 3% rise in gas-fired generation in the US. Shale gas accounted for 45% of the nation's electricity generation in July 2020. This element is likely to propel the shale gas industry, which is anticipated to propel the drilling fluid market worldwide.
Market Restraints
There are several obstacles that the global drilling fluids market must overcome to continue growing. Among them are the following:
Drilling Fluids' Effects on the Environment
During the downhole injection and onshore disposal procedures, these fluids produce hazardous substances. When these substances combine with groundwater, the quality of the groundwater is lowered. When this wastewater and waste enter the environment again, it severely pollutes the soil, disrupts marine ecosystems, and negatively impacts aquatic life in the ocean. The global market would suffer from this aspect during the forecast. Stricter drilling chemical regulations are being implemented by numerous government agencies in an effort to stop the hazardous effects of fluid on the environment, public health, and safety. For example, the U.S. Environmental Protection Agency (EPA) released guidelines for the oil and gas extraction industry on June 4, 2001. The effluent guidelines set forth new source performance standards (NSPS) and technologically-based best available technology economically achievable limitations for the discharge of pollutants into water from oil and gas drilling operations related to the use of synthetic-based fluids and other non-aqueous fluids. These factors restrain the growth of the global drilling fluids market.
Opportunities
There are plenty of potential prospects in the global drilling fluids industry. Among these are the following:
Greater Focus on Drilling Operations in Deepwater and Ultra-Deepwater
Energy companies are increasingly focusing their exploration efforts on deepwater and ultra-deepwater locations as conventional oil and gas reserves become harder to reach. These regions present enormous unexplored resource potential but also substantial technical difficulties due to their complex geological formations, high temperatures, and extreme pressures. In order to overcome these difficulties, drilling fluids are essential because they keep the wellbore stable, regulate pressure, and transport drill cuttings to the surface. The advancement of sophisticated drilling techniques, such as hydraulic fracturing and horizontal drilling, has made it possible to extract oil and gas from deepwater and ultra-deepwater reservoirs more effectively. These technologies demand specific drilling fluid formulations made to account for the particular circumstances found at deeper depths. Because of this, there is an increasing need for high-performance drilling fluids that can maximize drilling efficiency while withstanding harsh downhole conditions.
Competitive Landscape
Key Players
Several major competitors exist in the fiercely competitive global drilling fluids market. The following are a few of the leading market participants and their market shares:
- Baker Hughes, Inc.
- Halliburton, Inc.
- Weatherford International
- Schlumberger Ltd.
- Newpark Resources, Inc.
- Petrochem Performance Chemical Ltd. LLC
- CES Energy Solutions Corp.
- Scomi Group Bhd
- Others
These companies prioritize product innovation, distribution channel expansion, mergers, and acquisitions to remain competitive.
The largest suppliers in the global drilling fluids market continuously work to keep one step ahead of the competition by developing innovative concepts and products.
In May 2021, The Baker Hughes Company and Akastor ASA reached a joint venture agreement for a business that would combine Baker Hughes' Subsea Drilling System (SDS) division with MHWirth AS, an entirely owned subsidiary of Akastor. In order to provide customers with a large selection of goods and services, the new joint venture company will provide a full range of offshore drilling equipment services.
In November 2021, The Danish offshore drilling contractor Maersk Drilling and the American Noble Corporation announced that they had signed a definitive agreement to merge in an all-stock transaction that would result in a combined company with a fleet of 20 floaters and 19 jack-up rigs.
Summary of Key Findings
- The market for drilling fluids continues to be influenced by an investment in research and development.
- The market is segmented by fluid type, additive, application, and region.
- The most popular fluid type in the market is water-based drilling fluids.
- Viscosifiers are the foremost category.
- Oil and gas drilling is expected to grow fastest in terms of CAGR during the forecast period.
- North America is leading market development; the market is highly competitive with key players including Baker Hughes, Inc., Halliburton, Inc., Weatherford International, Schlumberger Ltd., Newpark Resources, Inc., Petrochem Performance Chemical Ltd. LLC, CES Energy Solutions Corp., Scomi Group Bhd, and Others.
Future Outlook
- The drilling fluids industry is expected to increase significantly in North America, and there is a positive outlook worldwide.
- The growing emphasis on reservoir drilling optimization is supporting the expansion of the global market.
- High upfront costs associated with advanced drilling fluid technologies will hinder the market's growth for drilling fluids during the anticipated period.
- To stay ahead of the competition, key enterprises must develop new products, expand their market reach, and keep their prices competitive.
How CXOs Can Benefit from the Credence Research Drilling Fluids Market Report
CXOs may get a detailed picture of the market in the Credence Research Drilling Fluids Market Report, which includes:
- Market size and growth forecast: The report provides detailed estimates of the global drilling fluids market size, segmented by fluid type, additive, application, and region. It also includes forecasts for the market through 2032 based on key trends and drivers.
- Market segmentation: The research report breaks down the market for drilling fluids into segments based on the fluid type, additive, application, and region. This segmentation provides CXOs with a granular understanding of the market and the opportunities in each segment.
- Competitive landscape: The research report offers a detailed analysis of the major companies in the drilling fluids industry, including information on their business plans, product lines, and earnings. CXOs can use this information to evaluate and identify their competitors.
- Key trends and drivers: The research report identifies and evaluates the main trends and factors influencing the drilling fluids market. CXOs can use this information to make well-informed choices regarding their plans and investments.
CXOs can use the insights from the Credence Research Drilling Fluids Market Report to:
- Identify growth opportunities: This analysis may help CXOs identify new growth opportunities in the drilling fluids sector. For example, the report identifies the growing demand for drilling fluids from mining and mineral exploration as a key opportunity.
- Make informed investment decisions: The report helps CXOs choose drilling fluids wisely. For example, the research study provides information on the critical factors to consider while selecting drilling fluid solutions and evaluating drilling fluid suppliers.
- Develop competitive strategies: The research report can be used by CXOs to develop competitive strategies for their drilling fluids businesses. For example, the research paper outlines the main strategies that drilling fluid suppliers utilize to differentiate themselves from competitors.
- Track market developments: This research report may help CXOs stay ahead of the curve by tracking market developments. For instance, it offers insights into the most recent developments and trends in the drilling fluids market.
In general, CXOs seeking to expand their industry knowledge and spot growth prospects will find the Credence Research Drilling Fluids Market Report a useful tool.
Segmentation
- By Fluid Type
- Water-Based Drilling Fluids
- Oil-Based Drilling Fluids
- Synthetic-Based Drilling Fluids
- Pneumatic Drilling Fluids
- Foam-Based Drilling Fluids
- By Additive
- Viscosifiers
- Weighting Agents
- Fluid Loss Control Agents
- Emulsifiers and Wetting Agents
- Corrosion Inhibitors
- Biocides
- Surfactants
- Fluid pH Buffers
- By Application
- Oil and Gas Drilling
- Geothermal Drilling
- Mining and Mineral Exploration
- Civil Engineering and Construction
- By Region
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
- North America
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Deepwater and Ultra-Deepwater Drilling
As conventional onshore reserves decline, energy companies are increasingly investing in deepwater and ultra-deepwater drilling projects, which require advanced drilling fluids to withstand high pressures and temperatures, driving demand for specialized formulations.
Growth in Oil and Gas Exploration Activities
Rising global energy demand is prompting increased exploration and production activities, particularly in shale gas and unconventional resources, necessitating the use of drilling fluids for efficient and safe drilling operations.
Technological Advancements in Drilling Fluid Formulations
Continuous innovation in drilling fluid chemistry, including the development of environmentally friendly and high-performance fluids, enables operators to address complex geological challenges and regulatory requirements, boosting market growth.
Increased Investment in Offshore Drilling Operations
Offshore drilling, especially in regions like North America and Asia Pacific, is seeing significant capital inflows, which in turn increases the consumption of drilling fluids tailored for harsh marine environments.
Integration of Digital Technologies for Real-Time Monitoring
The adoption of digital monitoring and optimization technologies in drilling operations allows for real-time adjustment of drilling fluid properties, improving efficiency and reducing operational risks, thereby supporting market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
How much does the global market currently hold for drilling fluids?
What is the drilling fluids market's projected growth rate between 2024 and 2032?
In terms of fluid type, which market category is leading?
Regarding the additive, which market category is in the lead?
Who are the main players in the global drilling fluids industry?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Additive
- 1.2.1 Viscosifiers
- 1.2.2 Weighting Agents
- 1.2.3 Fluid Loss Control Agents
- 1.2.4 Emulsifiers and Wetting Agents
- 1.2.5 Corrosion Inhibitors
- 1.2.6 Biocides
- 1.2.7 Surfactants
- 1.2.8 Fluid pH Buffers
- 1.3 By Fluid Type
- 1.3.1 Water-Based Drilling Fluids
- 1.3.2 Oil-Based Drilling Fluids
- 1.3.3 Synthetic-Based Drilling Fluids
- 1.3.4 Pneumatic Drilling Fluids
- 1.3.5 Foam-Based Drilling Fluids
- 1.4 By Application
- 1.4.1 Oil and Gas Drilling
- 1.4.2 Geothermal Drilling
- 1.4.3 Mining and Mineral Exploration
- 1.4.4 Civil Engineering and Construction
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 8,152.2 million → 2032: USD 12,219.68 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Drilling Fluids Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Drilling Fluids Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Drilling Fluids Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Drilling Fluids Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Drilling Fluids Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Drilling Fluids Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Drilling Fluids Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Drilling Fluids Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 8,152.2 million → 2032: USD 12,219.68 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Drilling Fluids Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Additive - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Viscosifiers
- 12.3.7.2 Weighting Agents
- 12.3.7.3 Fluid Loss Control Agents
- 12.3.7.4 Emulsifiers and Wetting Agents
- 12.3.7.5 Corrosion Inhibitors
- 12.3.7.6 Biocides
- 12.3.7.7 Surfactants
- 12.3.7.8 Fluid pH Buffers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Fluid Type - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Water-Based Drilling Fluids
- 12.4.7.2 Oil-Based Drilling Fluids
- 12.4.7.3 Synthetic-Based Drilling Fluids
- 12.4.7.4 Pneumatic Drilling Fluids
- 12.4.7.5 Foam-Based Drilling Fluids
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Oil and Gas Drilling
- 12.5.7.2 Geothermal Drilling
- 12.5.7.3 Mining and Mineral Exploration
- 12.5.7.4 Civil Engineering and Construction
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Drilling Fluids End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Drilling Fluids Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Drilling Fluids Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Drilling Fluids Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Baker Hughes, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Halliburton, Inc.
- 18.4 Weatherford International
- 18.5 Schlumberger Ltd.
- 18.6 Newpark Resources, Inc.
- 18.7 Petrochem Performance Chemical Ltd. LLC
- 18.8 CES Energy Solutions Corp.
- 18.9 Scomi Group Bhd
- 18.10 AkzoNobel N.V.
- 18.11 National Oilwell Varco, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

