
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Medical Imaging Reagents Market Size 2023 | USD 16251.2 Million |
| Medical Imaging Reagents Market , CAGR | 5.2% |
| Medical Imaging Reagents Market Size 2032 | USD 25646.4 Million |
Market Insights
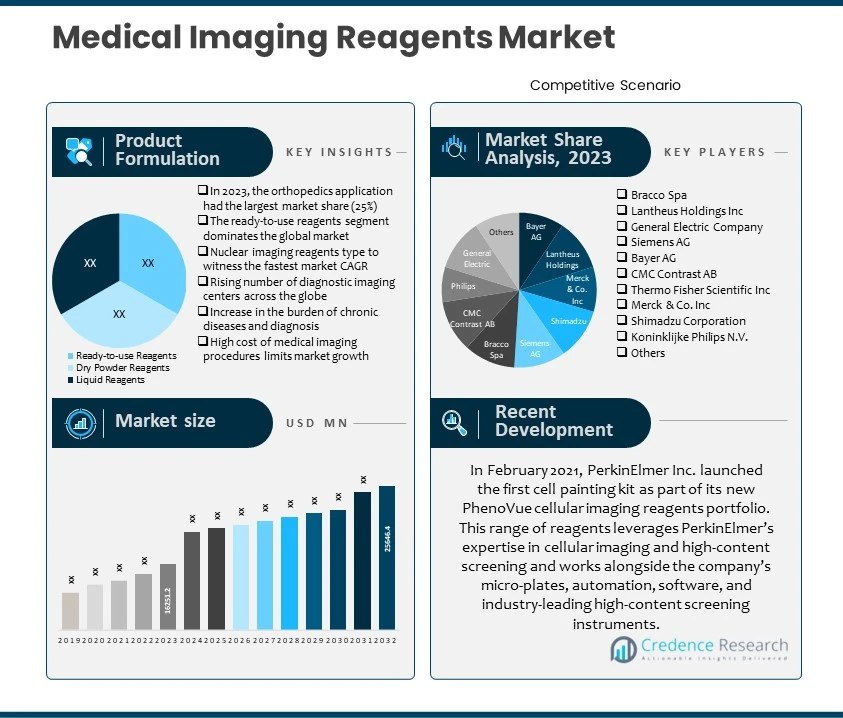
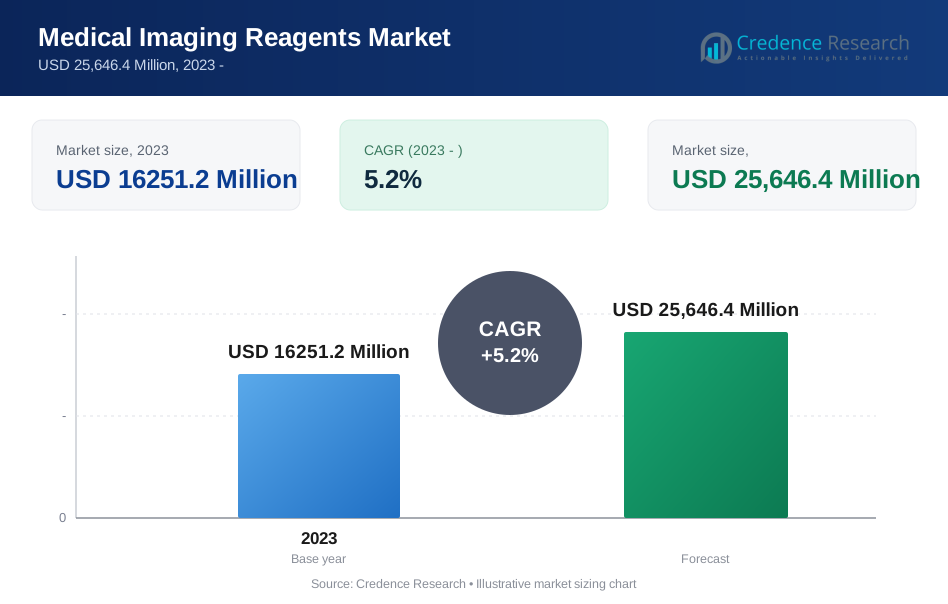
- The global demand for medical imaging reagents was valued at USD 16251.2 Million in 2023 and is expected to reach USD 25646.4 Million in 2032, growing at a CAGR of 5.2% between 2024 and 2032.
- Computed tomography (CT) is the market leader in imaging modality, accounting for more than 20% of the total value in 2023, while the magnetic resonance imaging (MRI) category is predicted to increase substantially over the forecast time frame.
- The contrast agents type dominates the global need for medical imaging reagents, accounting for more than 18% in 2023, and is anticipated to grow at an elevated CAGR.
- Over the projection period, the cardiology application segment is expected to expand at the highest rate, while the orthopedics category dominated the market in 2023 with a 25% share.
- The ready-to-use reagents category dominated the market with 40% of the total revenue share by product formulation segment. In contrast, the liquid reagents will expand fastest in the projected period.
- With an impressive market share of more than 58% by 2023 and estimates for considerable CAGR growth, the radioactive isotopes category will likely continue to dominate the global market needs.
- The market has seen a trend towards developing point-of-care imaging reagents, enabling rapid and efficient diagnostics in various healthcare settings.
- The rising incidence of cardiovascular diseases globally has propelled the market demand for cardiac imaging reagents, supporting the diagnosis and monitoring of conditions such as myocardial infarction and heart failure.
Executive Summary
Market Definition
Medical imaging reagents refer to chemical substances or compounds used in conjunction with various imaging modalities to enhance the visibility and diagnostic accuracy of medical images. These reagents play a crucial role in diagnostic imaging techniques, enabling healthcare professionals to obtain detailed and clear images of the human body's internal structures and physiological processes.
Medical imaging reagents are specifically formulated to interact with target tissues or substances, producing contrast that highlights specific anatomical features or pathological conditions. They are integral to various imaging techniques, including MRI, CT, PET, single-photon emission computed tomography (SPECT), ultrasound, and X-ray imaging. The continuous innovation in medical imaging reagents aims to improve imaging sensitivity, reduce side effects, and provide clinicians with valuable diagnostic information for enhanced patient care.
Market Overview
The global medical imaging reagents market has witnessed consistent growth over recent years and is set to grow at a CAGR of 5.2% between 2024 and 2032. The market was valued at USD 16251.2 million in 2023 and is expected to reach USD 25646.4 million in 2032.
The rise in incidences of long-term illnesses such as cancer and cardiovascular disease, technical developments, medical imaging reagent progress, and higher unmet medical and diagnostic imaging procedure demands are the main factors propelling the global medical imaging reagents market forward.
Moreover, older people are more likely to suffer from chronic diseases; thus, the rapid expansion in the geriatric population is estimated to drive up the need for medical imaging reagents. For example, aging can induce changes in the heart and blood arteries, raising the chance of developing coronary artery disease. People over the age of 65 are more prone to develop cardiovascular disease (CVD) than younger people. According to UN DESA's Population Division, by 2050, one in every six persons will be over the age of 65, up from one in every eleven in 2019. Globally, life expectancy beyond 65 will rise by 19 years by 2050, while in certain regions, the population over 65 will have doubled.
Segmentation by Type of Reagents
- Contrast agents are the leading type of reagents category and held over 18% share in value in 2023. These agents are commonly employed in medical imaging to improve the visibility of organs, specific tissues, or blood arteries. They can be divided into three types: gadolinium-based contrast agents, iodinated contrast agents, and ultrasonic contrast agents. These agents improve image contrast and clarity, allowing for more accurate visualization and diagnosis.
- The nuclear imaging reagents segment will likely exhibit a significant market CAGR. Nuclear imaging reagents, such as radiopharmaceuticals, are utilized in nuclear medicine imaging techniques such as PET and single-photon emission computed tomography. These reagents contain radioactive tracers that radiate gamma rays, making it possible to visualize physiological processes and diagnose disorders at the molecular level.
Segmentation by Imaging Modality
- The computed tomography (CT) segment asserts dominance in global demand, capturing an extensive market share exceeding 20% in 2023, attributed to its widespread application in diverse medical imaging scenarios.
- The MRI, PET, and ultrasound segments collectively contribute to the remaining demand for medical imaging reagents, owing to the diverse landscape of imaging modalities.
Segmentation by End-User
- The diagnostic imaging centers category is expected to post the highest CAGR. Diagnostic imaging centers are dedicated to performing medical imaging examinations. They are important in providing patients with imaging services and partnering with healthcare experts to ensure proper diagnosis and patient care.
- The hospitals and clinics are leading the market share with over 30% share in 2023. They are the principal end users of medical imaging reagents. These facilities actively utilize imaging procedures to diagnose, arrange treatment, and monitor various diseases.
Segmentation by Application
- The cardiology application segment is set to register the largest CAGR. Cardiologists widely use medical imaging reagents to diagnose and evaluate cardiovascular disorders. These chemicals allow for the visualization of heart chambers, blood vessels, and cardiac activity, which helps to detect problems like coronary artery disease and heart failure.
- Currently, in the lead with a substantial market share of nearly 25% in 2023, the orthopedics category highlights the critical role of imaging reagents in musculoskeletal diagnostics. Orthopedic applications, including bone scans and joint imaging, contribute majorly to the overall market revenue.
Segmentation by Product Formulation
- Ready-to-use reagents take the lead, commanding over 40% of the global demand in 2023, owing to an increased preference for convenience and efficiency in medical imaging procedures.
- Dry powder and liquid reagents collectively contribute to the remaining market demand, offering varied formulations for diverse imaging requirements.
Segmentation by Region
- North America emerges as the growth catalyst, contributing over one-third of the market share in 2023, propelled by robust healthcare infrastructure and high adoption rates of advanced imaging technologies.
- Europe and Asia Pacific collectively account for just under 55% of the market share in 2023, with Europe holding over 21%. These regions demonstrate a noticeable presence in the global medical imaging reagents market, characterized by increasing healthcare investments and expanding diagnostic capabilities.
- The rest of the world, encompassing Latin America, the Middle East, and Africa, presents a vital medical imaging reagent demand source, contributing to the global market landscape. Factors such as increasing healthcare awareness, improving healthcare infrastructure, and rising investments in diagnostic technologies contribute to the global demand dynamics.
Based on geography, the region of North America has developed as the largest global market for medical imaging reagents due to the huge number of hospitals and diagnostic centers in this part of the world. The existence of key market players in the region has also served as a key reason for expanding the medical imaging reagents market. Many people residing in the North American region belong to the senior population, a potential market for the growth of medical imaging reagents. The advanced healthcare facilities provided to the people by the government also proved to be a huge opportunity, favoring the medical imaging reagents market. Most individuals in this region have a Mediclaim, which presents a huge opportunity for the industry as patients there frequently choose advanced diagnostic treatments, including CT scans, ultrasounds, MRIs, and X-rays.
The European region has also emerged as an expanding marketplace for medical imaging reagents due to the government's upgraded healthcare options for citizens. The COVID-19 pandemic drastically impacted European market revenue growth, further allowing the medical sector to improve its services.
Asia Pacific is set to be the region with the most rapid expansion over the estimated time frame. The region is witnessing a substantial increase in healthcare expenditure owing to rapid economic growth and an expanding middle-class population. Also, ongoing advancements in healthcare infrastructure, particularly in countries like China and India, facilitate improved accessibility to cutting-edge medical imaging technologies, thereby contributing to the accelerated growth of the medical imaging reagents market in the region. For example, with the rise in the burden of cancer, the demand for imaging reagents is also growing to improve cancer diagnosis. According to the ICMR (Indian Council of Medical Research), cancer incidences in India will grow by 12% in the next five years, with 1.5 million people expected to suffer from the noncommunicable disease by 2025, up from 1.39 million in 2020.
Key Highlights of the Report
The global medical imaging reagents market is segmented by type of reagents, imaging modality, application, end-user, product formulation, isotope, and region. Contrast agents take center stage in the type of reagents, owing to their indispensable role in enhancing imaging precision across various medical procedures. The computed tomography (CT) segment emerges as a core within imaging modalities due to its widespread application and technological significance. Diagnostic imaging centers experience dynamic growth in the end-users category, pointing to an evolving healthcare landscape favoring specialized facilities with advanced imaging technologies.
The growing elderly population, increased healthcare spending, and higher requirements for effective procedures and safe substances are all projected to promote the growth of the medical imaging reagents industry. Increasing public awareness of early disease diagnosis is also a significant aspect supporting the market's growth. For example, early detection of chronic disorders improves the likelihood of successful treatment. As a result, healthcare practitioners place a high priority on the early identification of clinical diseases, which includes the use of medical imaging procedures, which in turn require the usage of medical imaging reagents. Conversely, untapped new markets in developing nations are likely to provide remunerative opportunities for medical imaging reagents market players. For instance, healthcare facilities in emerging countries such as India, Brazil, and China have experienced substantial increases in investments in healthcare and infrastructure, which has led to an upsurge in demand for genetic testing in the regions. However, the lack of imaging reagent suppliers and strict government regulations are expected to hinder market growth.
North America accounted for the highest share of the medical imaging reagents market in 2023 and is likely to maintain its global dominance across the forecast period. This is due to an increase in the prevalence of cardiovascular and neurological disorders, as well as cancer, and a rise in awareness of medical imaging reagents. According to the CDC (Centers for Disease Control & Prevention), chronic conditions like cancers, heart diseases, and diabetes are the major causes of mortality and disability in the United States. In addition, the increasing geriatric population, a big target demographic with increased health awareness, and the availability of qualified healthcare professionals in the region are all factors supporting market expansion. On the other hand, Asia-Pacific is likely to have the fastest growth rate over the assessment period, owing to an increase in the number of medical imaging operations and a spike in the utilization of medical imaging reagents in proficient diagnostic imaging techniques.
What Are The Main Drivers Of The Global Medical Imaging Reagents Market?
The global medical imaging reagents market is primarily driven by the extending prevalence of chronic disorders, fueling the demand for advanced diagnostic imaging technologies. The rise in geriatric populations globally, coupled with a growing emphasis on early and accurate disease diagnosis, further propels the market share. Ongoing technological advancements, such as developing targeted and multifunctional imaging reagents, contribute to the market's expansion, offering improved diagnostic capabilities and fostering innovation in medical imaging. Moreover, the expanding applications of medical imaging reagents in diverse fields, including oncology, cardiology, and neurology, contribute to the market's sustained growth.
What Are The Major Challenges Faced By The Global Medical Imaging Reagents Market?
The global medical imaging reagents market faces major challenges, including stringent regulatory requirements and the complex approval process for new imaging agents. Concerns related to the safety and potential side effects of certain reagents pose hurdles, negatively influencing both development and market acceptance. Besides, the higher cost associated with advanced imaging technologies, reagents, and budget constraints in healthcare systems limit their widespread adoption. The ongoing need for environmentally sustainable practices in producing and disposing of imaging reagents presents an additional challenge, prompting the industry to explore eco-friendly alternatives.
What Are The Growth Opportunities In The Global Medical Imaging Reagents Market?
The global medical imaging reagents market presents promising growth opportunities attributed to the increasing adoption of personalized medicine and the rising demand for molecular imaging techniques. Emerging innovations in nanotechnology, particularly the development of nanoparticle-based imaging agents, offer market avenues for enhanced diagnostic capabilities. The expanding applications of medical imaging reagents in veterinary diagnostics and the integration of AI into imaging processes further contribute to the market's growth potential. Moreover, the continued focus on research and development, collaborations, and strategic partnerships is expected to pave the way for novel and advanced imaging reagents, fostering sustained market expansion.
Market Drivers
Several factors drive the global medical imaging reagents market. The following are the key drivers of the global medical imaging reagents market:
A growing proportion of patients suffer from chronic illnesses
The increased global prevalence of chronic health conditions, including tumors, cardiovascular diseases, and neurological disorders, is a major driver of the medical imaging reagents market size. Diagnostic imaging serves a main role in the early detection, staging, and monitoring of these diseases, creating a sustained demand for imaging reagents. As per the WHO, CVDs (cardiovascular diseases) are the most prevalent cause of mortality worldwide, claiming an estimated 17.9 million lives per year. As the global burden of chronic diseases grows, the need for efficient and accurate diagnostic tools supported by medical imaging reagents becomes increasingly important.
Chronic diseases often require ongoing monitoring and precise diagnosis, which can be facilitated through various imaging modalities. Medical imaging reagents, such as contrast agents used in MRI or CT scans, enable healthcare professionals to obtain clearer and more detailed images, assisting in the early discovery and effective management of chronic conditions. The expanding medical imaging applications in disease management contribute to the consistent demand for imaging reagents.
Market Restraints
The global medical imaging reagents market faces challenges that may limit its growth. These include the following:
Lack of Accessibility and High Cost of Advanced Imaging Reagents
One of the primary factors likely to impede expansion in the medical imaging reagents market is the absence or limited availability of imaging reagents. The restricted global availability of imaging reagents makes them unavailable for application in diagnosis. The need for imaging reagents, such as molybdenum-99 and technetium-99m, has increased the cost of these reagents, making it harder for end users to employ imaging equipment for many purposes. Thus, the shortage of imaging reagents limits market development, particularly in emerging countries.
Opportunities
The global medical imaging reagents market offers significant growth opportunities. These include the following:
Rise in Point-of-Care Imaging
The emerging demand for point-of-care (POC) imaging solutions provides a notable market opportunity for medical imaging reagents. POC imaging involves performing diagnostic imaging tests at or near the patient's location, offering rapid results and facilitating quicker decision-making in healthcare settings. With the rising number of diagnostic imaging centers globally, the demand or usage for medical imaging reagents is also growing rapidly. For example, RadNet Inc. has around 351 diagnostic imaging centers across the U.S. and conducts more than 9 million outpatient diagnostic imaging procedures annually. The company's primary objective is to deliver high-quality, conveniently accessible care in the most cost-effective manner possible.
The development of imaging reagents suitable for POC applications, such as portable ultrasound or handheld imaging devices, opens new market avenues for accessibility and convenience in diagnostics. This market trend aligns with the broader shift towards decentralized healthcare delivery and improved patient outcomes through rapid diagnostics.
Competitive Landscape
Key Players
The medical imaging reagents industry is extremely competitive, with several major competitors competing on a global basis. The following are a few of the most prominent market players and their market shares:
- Bracco Spa
- Lantheus Holdings Inc
- General Electric Company
- Siemens AG
- Bayer AG
- CMC Contrast AB
- Thermo Fisher Scientific Inc
- Merck & Co. Inc
- Shimadzu Corporation
- Koninklijke Philips N.V.
- Others
These leading companies focus on developing advanced and targeted imaging reagents to strengthen their market presence and cater to diverse diagnostic needs. They also focus on R&D activities, mergers and acquisitions, strategic collaborations, and product innovations to preserve a competitive advantage.
In March 2022, Mylab Discovery Solutions announced plans to deliver routine diagnostic kits and devices in traditional and POCT formats. With this product line expansion, labs may now employ Mylab devices and reagents to perform all regular tests, including heart profiles, liver and kidney function tests, hormone, urine, and fever panels, cancer indicators, and more.
In February 2021, PerkinElmer Inc., a US-based company specializing in diagnostics, biological sciences, and applied services, introduced the first cell painting kit. The carefully selected and calibrated ingredients in the kit are meant to make painting cells easier for research scientists. The PhenoVue cellular imaging reagent collection includes fluorescent organelle staining probes and dye-labeled secondary antibodies to help clients construct high-content screening assays faster.
In April 2019, PerkinElmer Corporation Limited, a world leader in medical imaging reagents, acquired Cisbio Bioassays, one of the biggest players in the field of life science.
Summary of Key Findings
- The medical imaging reagents market has experienced significant growth owing to the escalating global prevalence of chronic diseases and the increased demand for diagnostic imaging procedures.
- The market is segmented by type of reagents, imaging modality, application, end-user, product formulation, isotope, and region.
- Hybrid imaging modalities, such as PET-CT and PET-MRI, have gained global popularity, driving the market need for versatile imaging reagents that can be used across multiple imaging platforms for more comprehensive diagnostics.
- Oncology remains a key application area for medical imaging reagents, with continuous advancements in cancer imaging and the development of targeted agents for tumor characterization.
- In neurology, medical imaging reagents are widely utilized for brain imaging, helping diagnose and monitor neurological disorders.
- The use of medical imaging reagents in preclinical research has expanded, allowing for advanced imaging studies in animal models. This market trend supports drug development and research in various therapeutic areas.
- Emerging markets, particularly in Asia-Pacific and Latin America, are showing increased adoption of medical imaging reagents due to improving healthcare infrastructure and a growing focus on early disease detection.
- Accessibility challenges, particularly in resource-limited regions, hinder the widespread market adoption of medical imaging reagents, prompting efforts to address affordability and availability issues.
Future Outlook
- Companies in the medical imaging reagents market are engaging in strategic collaborations and partnerships to leverage complementary expertise, accelerate product development, and expand market reach.
- The concept of theragnostic, combining diagnostic and therapeutic capabilities in a single agent, is gaining market traction. This approach is particularly prominent in oncology for targeted therapy.
- The utilization of nanoparticle-based imaging agents is on the rise, offering advantages such as enhanced imaging resolution and multifunctionality, leading to increased penetration in the medical imaging reagents market.
How CXOs Can Benefit from the Credence Research Medical Imaging Reagents Market Report
The Credence Research Medical Imaging Reagents Market Report provides CXOs with a comprehensive overview of the market, including:
- Market size and growth forecast: The report provides detailed estimates of the global medical imaging reagents market size, segmented by type of reagents, imaging modality, application, end-user, product formulation, isotope, and region. It also includes forecasts for the market through 2032 based on key trends and drivers.
- Market segmentation: The report segments the medical imaging reagents market by type of reagents, imaging modality, application, end-user, product formulation, isotope, and region. This segmentation provides CXOs with a granular understanding of the market and the opportunities in each segment.
- Competitive Landscape: The report profiles the key players in the medical imaging reagents market and provides insights into their strategies, product offerings, and financial performance. This information can help CXOs to identify and assess their competition.
- Key trends and drivers: The report identifies and analyses the key trends and drivers shaping the medical imaging reagents market. This information can help CXOs to make informed decisions about their investments and strategies.
CXOs can use the insights from the Credence Research Medical Imaging Reagents Market Report to:
- Identify growth opportunities: The report can help CXOs identify new growth opportunities in the medical imaging reagents market. For example, the report identifies the growing demand for medical imaging reagents from diagnostic imaging centers and research institutes as a key opportunity.
- Make informed investment decisions: The report can help CXOs make informed investment decisions about medical imaging reagents. For example, the report provides insights into the key factors to consider when evaluating medical imaging reagents providers and selecting solutions.
- Develop competitive strategies: The report can help CXOs develop competitive strategies for their medical imaging reagents businesses. For example, the report identifies the key strategies medical imaging reagents providers use to differentiate themselves from competitors.
- Track market developments: The report can help CXOs to track market developments and stay ahead of the curve. For example, the report provides insights into the latest trends and innovations in the medical imaging reagents market.
Overall, the Credence Research Medical Imaging Reagents Market Report is a valuable resource for CXOs looking to understand the market better and identify growth opportunities.
Segmentation
By Type of Reagents- Contrast Agents
- Iodinated Contrast Agents
- Gadolinium-Based Contrast Agents
- Barium-Based Contrast Agents
- Microbubble Contrast Agents (used in ultrasound)
- Nuclear Imaging Reagents
- Technetium
- Fluorine
- Gallium
- Thallium
- Fluorescent Dyes
- Bioluminescent Substrates
- Others
- Computed Tomography (CT)
- Magnetic Resonance Imaging (MRI)
- Positron Emission Tomography (PET)
- Ultrasound
- X-ray
- Nuclear Medicine
- Cardiology
- Oncology
- Neurology
- Orthopedics
- Gastroenterology
- Nephrology
- Others
- Hospitals and Clinics
- Diagnostic Imaging Centers
- Research Institutes
- Pharmaceutical and Biotechnology Companies
- Ready-to-use Reagents
- Dry Powder Reagents
- Liquid Reagents
- Radioactive Isotopes
- Non-radioactive Isotopes
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Chronic Diseases
The increasing incidence of chronic illnesses such as cancer and cardiovascular diseases is driving demand for advanced diagnostic imaging, which in turn boosts the need for medical imaging reagents to enable accurate and early detection.
Aging Global Population
The rapid growth of the geriatric population, who are more susceptible to chronic and degenerative diseases, is leading to higher utilization of diagnostic imaging procedures and thus greater consumption of imaging reagents.
Technological Advancements in Imaging Modalities
Continuous innovation in imaging technologies, such as hybrid PET-CT and PET-MRI systems, is expanding the applications and effectiveness of imaging reagents, supporting market growth by enabling more precise and multifunctional diagnostics.
Expansion of Diagnostic Imaging Centers
The proliferation of specialized diagnostic imaging centers, particularly in developed regions, is increasing the accessibility and frequency of imaging procedures, directly contributing to higher reagent usage.
Shift Toward Point-of-Care and Personalized Medicine
The development of point-of-care imaging reagents and the growing adoption of personalized medicine approaches are creating new opportunities for targeted and rapid diagnostics, further fueling market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the global medical imaging reagents market?
What is the expected growth rate of the medical imaging reagents market between 2024 and 2032?
Which category is leading the global market share in terms of imaging modality?
Which end-user segment governs the demand for medical imaging reagents globally?
Who are the major players in the global medical imaging reagents market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Cardiology
- 1.2.2 Oncology
- 1.2.3 Neurology
- 1.2.4 Orthopedics
- 1.2.5 Gastroenterology
- 1.2.6 Nephrology
- 1.3 By Imaging Modality
- 1.3.1 Computed Tomography (CT)
- 1.3.2 Magnetic Resonance Imaging (MRI)
- 1.3.3 Positron Emission Tomography (PET)
- 1.3.4 Ultrasound
- 1.3.5 X-ray
- 1.3.6 Nuclear Medicine
- 1.4 By Type of Reagents
- 1.4.1 Contrast Agents
- 1.4.2 Nuclear Imaging Reagents
- 1.4.3 Fluorescent Dyes
- 1.4.4 Bioluminescent Substrates
- 1.4.5 Others
- 1.5 By Product Formulation
- 1.5.1 Ready-to-use Reagents
- 1.5.2 Dry Powder Reagents
- 1.5.3 Liquid Reagents
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 16251.2 Million → 2032: USD 25,646.4 Million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Medical Imaging Reagents Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Medical Imaging Reagents Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Medical Imaging Reagents Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Medical Imaging Reagents Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Medical Imaging Reagents Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Medical Imaging Reagents Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Medical Imaging Reagents Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Medical Imaging Reagents Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 16251.2 Million → 2032: USD 25,646.4 Million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Medical Imaging Reagents Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Cardiology
- 12.3.7.2 Oncology
- 12.3.7.3 Neurology
- 12.3.7.4 Orthopedics
- 12.3.7.5 Gastroenterology
- 12.3.7.6 Nephrology
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Imaging Modality - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Computed Tomography (CT)
- 12.4.7.2 Magnetic Resonance Imaging (MRI)
- 12.4.7.3 Positron Emission Tomography (PET)
- 12.4.7.4 Ultrasound
- 12.4.7.5 X-ray
- 12.4.7.6 Nuclear Medicine
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Type of Reagents - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Contrast Agents
- 12.5.7.2 Nuclear Imaging Reagents
- 12.5.7.3 Fluorescent Dyes
- 12.5.7.4 Bioluminescent Substrates
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Product Formulation - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Ready-to-use Reagents
- 12.6.7.2 Dry Powder Reagents
- 12.6.7.3 Liquid Reagents
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Medical Imaging Reagents End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Medical Imaging Reagents Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Medical Imaging Reagents Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Medical Imaging Reagents Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Bracco Spa
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Lantheus Holdings Inc
- 18.4 General Electric Company
- 18.5 Siemens AG
- 18.6 Bayer AG
- 18.7 CMC Contrast AB
- 18.8 Thermo Fisher Scientific Inc
- 18.9 Merck & Co. Inc
- 18.10 Shimadzu Corporation
- 18.11 Koninklijke Philips N.V.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

