
Market Overview
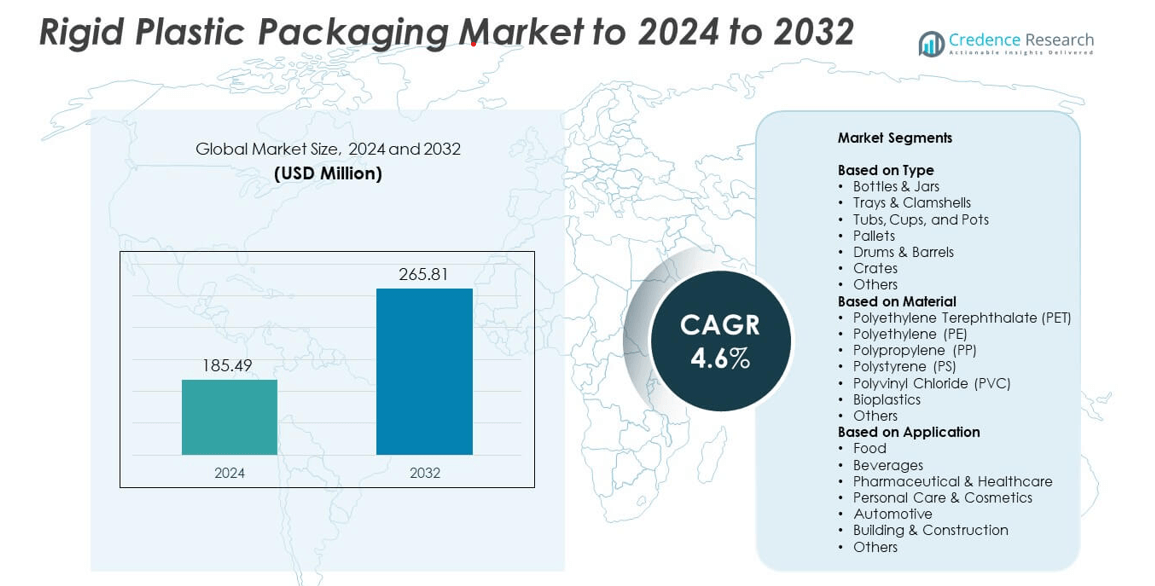
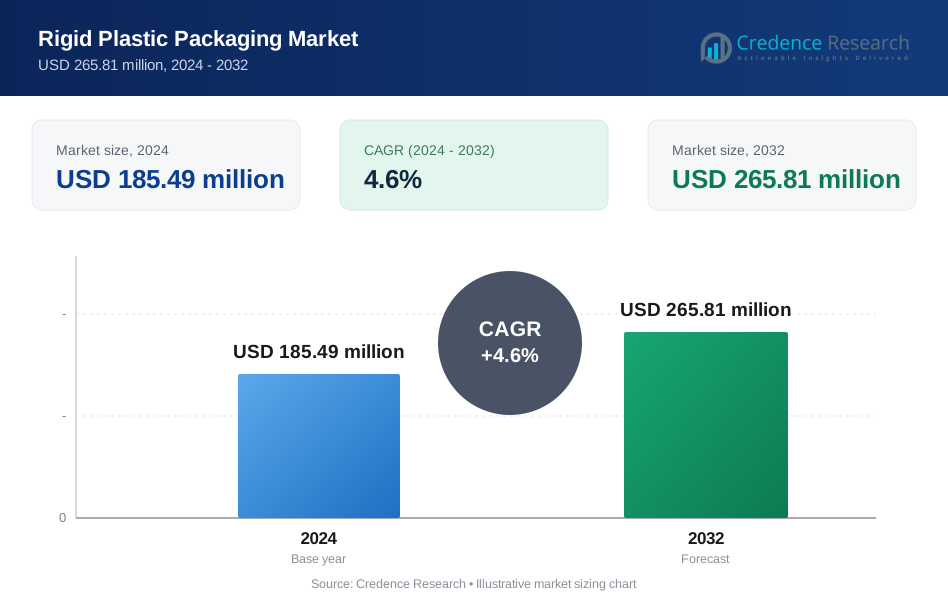
Rigid Plastic Packaging Market size was valued USD 185.49 million in 2024 and is anticipated to reach USD 265.81 million by 2032, at a CAGR of 4.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Rigid Plastic Packaging Market Size 2024 | USD 185.49 million |
| Rigid Plastic Packaging Market CAGR | 4.6% |
| Rigid Plastic Packaging Market Size 2032 | USD 265.81 million |
The rigid plastic packaging market is dominated by major players such as Amcor plc, Berry Global Inc., Sonoco Products Company, Sealed Air Corporation, DS Smith, ALPLA, Klöckner Pentaplast, Pactiv Evergreen Inc., WINPAK LTD, Nuplas Industries, and Genpak. These companies maintain strong positions through product diversification, innovation in sustainable materials, and advanced molding technologies. They focus on expanding recyclable and lightweight packaging to meet environmental standards and consumer preferences. North America led the market with a 38% share in 2024, supported by robust industrial output and high adoption in food, beverage, and healthcare packaging applications.
Market Insights
- The rigid plastic packaging market was valued at USD 185.49 million in 2024 and is expected to reach USD 265.81 million by 2032, growing at a CAGR of 4.6%.
- Increasing demand for durable, lightweight, and recyclable packaging materials across food and beverage, personal care, and pharmaceutical industries drives market expansion.
- The market is witnessing a shift toward rPET, rPP, and bioplastic materials as manufacturers focus on eco-friendly and circular packaging solutions.
- Competition remains high, with leading players emphasizing technological advancements, sustainable product innovation, and regional manufacturing expansion to strengthen market presence.
- North America led with a 38% share in 2024, followed by Europe at 27% and Asia Pacific at 24%, while the bottles and jars segment held the largest share of 41%, reflecting high adoption in beverages and consumer goods packaging.
Market Segmentation Analysis:
By Type
The bottles and jars segment dominated the rigid plastic packaging market with a 41% share in 2024. This dominance stems from their extensive use in the food, beverage, and personal care industries due to superior durability, leak resistance, and product visibility. Bottles and jars are preferred for packaging sauces, dairy products, carbonated drinks, and cosmetics. Manufacturers focus on lightweight and recyclable PET bottles to reduce material costs and environmental impact. Rising demand for convenient, resealable packaging and increased adoption in the pharmaceutical sector continue to drive this segment’s growth globally.
- For instance, multiple reports from March and April 2024 confirm that The Coca-Cola Company undertook a lightweighting project for its 12-, 16.9-, and 20-ounce PET bottles, reducing their weight from 21 grams to 18.5 grams.
By Material
Polyethylene terephthalate (PET) accounted for the largest market share of 37% in 2024, driven by its high strength-to-weight ratio, transparency, and recyclability. PET is widely used in beverage bottles, food containers, and pharmaceutical packaging owing to its excellent barrier properties against moisture and gas. Manufacturers are increasingly shifting toward rPET (recycled PET) to meet sustainability targets. Regulatory emphasis on eco-friendly materials and advancements in lightweight resin technology continue to strengthen the PET segment’s position in the global rigid plastic packaging market.
- For instance, a news release from Toyo Seikan Group Holdings dated October 24, 2024, describes a collaboration with Coca-Cola to create a 500 ml 100% r-PET Lightweight Bottle
By Application
The food segment led the rigid plastic packaging market with a 43% share in 2024. Growth is fueled by high demand for packaged and ready-to-eat foods requiring secure, lightweight, and tamper-resistant containers. Rigid plastic packaging provides extended shelf life, better protection, and ease of handling for frozen, dairy, and bakery products. Increasing urbanization, changing consumption patterns, and the expansion of retail distribution channels are major growth drivers. The growing focus on recyclable and BPA-free packaging further supports market expansion within the global food sector.
Key Growth Drivers
Sustainability and Recycling Initiatives
Growing global emphasis on sustainability and recycling is a major driver of the rigid plastic packaging market. Governments and corporations are implementing circular economy policies that encourage the use of recyclable materials such as PET and HDPE. Brands are shifting toward lightweight and reusable packaging solutions to minimize plastic waste. Consumers are also favoring eco-friendly packaging, prompting manufacturers to invest in advanced recycling technologies and bio-based plastics. These initiatives enhance brand reputation, comply with regulations, and drive steady demand for sustainable rigid packaging solutions worldwide.
- For instance, ALPLA’s Ballito plant produces up to 35,000 tonnes of rPET per year starting 2025.
Rising Demand from Food and Beverage Sector
Expanding demand for packaged food and beverages significantly supports market growth. Rigid plastic packaging offers durability, hygiene, and extended shelf life, making it ideal for dairy, beverages, and ready-to-eat products. The increasing urban population, growth in online food delivery, and retail expansion have amplified consumption. Lightweight and tamper-proof designs attract producers looking for cost-effective and secure packaging options. As convenience-oriented lifestyles rise, the adoption of rigid plastic containers across both developed and emerging markets continues to accelerate.
- For instance, Sidel has more than 7,000 SBO blowers in operation, and a water line reaching 90,000 bottles per hour.
Advancements in Material and Manufacturing Technologies
Technological progress in resin formulation and molding processes drives product innovation. Advanced materials like rPET, rPP, and bioplastics enhance recyclability and reduce environmental impact. Injection molding and thermoforming technologies now allow precise design customization and high production efficiency. Smart packaging integration with features such as tracking and freshness indicators is gaining traction. These innovations help manufacturers meet evolving consumer expectations and comply with strict sustainability regulations, strengthening competitiveness and efficiency across global supply chains.
Key Trends & Opportunities
Shift Toward Bioplastics and Recycled Materials
The transition toward bioplastics and post-consumer recycled materials represents a major opportunity. Companies are investing in bio-based polymers derived from sugarcane, corn, and cellulose to reduce carbon emissions. Governments supporting compostable packaging standards further accelerate this trend. The rise in rPET and rPP usage reflects a shift toward closed-loop manufacturing systems. This move not only aligns with environmental goals but also reduces dependency on virgin materials, offering long-term cost advantages and helping brands meet sustainability commitments.
- For instance, Indorama Ventures has recycled 150 billion PET bottles, avoiding 3.8 million tons of CO₂ and diverting 2.8 million tons of waste.
Growth in Smart and Functional Packaging Solutions
The adoption of smart packaging technologies provides new opportunities for market players. Rigid plastic packaging is increasingly being integrated with digital features such as QR codes, RFID tags, and freshness indicators to enhance product traceability and customer engagement. This trend is especially prominent in the food, pharmaceutical, and personal care sectors. Companies leveraging smart solutions gain a competitive edge by improving safety, supply chain transparency, and consumer trust. The rise of connected packaging systems is expected to create strong growth avenues in the coming years.
- For instance, Avery Dennison launched its RFID-enabled IML portfolio in July 2025, which includes several product types, such as the AD Anchor U9 IML. The datasheet for the AD Anchor U9 IML specifies an antenna size of 41 x 12 mm.
Key Challenges
Environmental Concerns and Stringent Regulations
Environmental concerns regarding plastic waste and pollution pose major challenges to market expansion. Governments are enforcing strict regulations on single-use plastics and non-recyclable materials, pressuring manufacturers to invest in sustainable alternatives. Compliance with regional recycling targets and waste management policies increases production costs. Public perception of plastics as environmentally harmful also affects demand in certain sectors. These factors compel companies to redesign packaging systems and adopt costly sustainable materials to maintain compliance and market presence.
Fluctuating Raw Material Prices
Volatility in crude oil prices directly impacts the cost of key polymers such as PET, PP, and PE. Sudden price shifts disrupt supply chains and profit margins for manufacturers. Dependence on petrochemical feedstocks also exposes the market to geopolitical risks and trade fluctuations. Many producers face difficulties in passing cost increases to end-users due to competitive pricing pressures. This volatility encourages companies to diversify raw material sources and increase investment in recycled and bio-based polymers to stabilize operations.
Regional Analysis
North America
North America held the largest share of 38% in the rigid plastic packaging market in 2024. The region’s growth is driven by strong demand from the food, beverage, and healthcare industries. The U.S. leads adoption of recyclable and lightweight packaging solutions, supported by strict environmental regulations and corporate sustainability goals. Manufacturers are investing in advanced molding and recycling technologies to reduce production costs and waste. The growing e-commerce sector and preference for convenient, durable packaging continue to strengthen market expansion across the region, particularly in the United States and Canada.
Europe
Europe accounted for a 27% share of the rigid plastic packaging market in 2024, supported by stringent sustainability policies and a strong recycling framework. Countries such as Germany, France, and the United Kingdom emphasize the use of recycled PET and bioplastics in food and beverage applications. The European Green Deal and packaging waste directives are accelerating the shift toward circular packaging solutions. Major players are investing in closed-loop production and lightweight materials. Increasing demand for sustainable and premium packaging among consumers continues to fuel growth in the European market.
Asia Pacific
Asia Pacific captured a 24% share of the rigid plastic packaging market in 2024 and is the fastest-growing region. Expanding urbanization, rising disposable incomes, and the booming food delivery industry drive significant demand. China, India, and Japan lead the region’s production due to strong manufacturing bases and growing consumer packaging needs. Government initiatives promoting eco-friendly materials and rising investments in rPET and bioplastics manufacturing are reshaping the industry. Rapid retail and e-commerce expansion across emerging economies further boosts adoption of rigid packaging solutions across diverse end-use sectors.
Latin America
Latin America accounted for an 8% share of the rigid plastic packaging market in 2024. Brazil and Mexico dominate regional demand, driven by growth in the beverage, personal care, and food processing sectors. Increasing focus on sustainable production and expansion of local recycling infrastructure are shaping market trends. Economic recovery and growing middle-class consumption patterns support packaging innovation. Manufacturers are introducing lightweight and refillable containers to meet evolving consumer preferences. Rising foreign investments in the packaging sector continue to enhance regional capacity and product diversification.
Middle East & Africa
The Middle East and Africa region held a 3% share of the rigid plastic packaging market in 2024. Market growth is supported by expanding food and beverage manufacturing and increasing investments in healthcare packaging. The UAE, Saudi Arabia, and South Africa are major contributors due to strong retail and industrial growth. Government policies promoting local manufacturing and recycling initiatives are gradually improving sustainability standards. Rising demand for durable and cost-efficient packaging across consumer goods and pharmaceutical sectors continues to drive steady market adoption in this region.
Market Segmentations:
By Type
- Bottles & Jars
- Trays & Clamshells
- Tubs, Cups, and Pots
- Pallets
- Drums & Barrels
- Crates
- Others
By Material
- Polyethylene Terephthalate (PET)
- Polyethylene (PE)
- Polypropylene (PP)
- Polystyrene (PS)
- Polyvinyl Chloride (PVC)
- Bioplastics
- Others
By Application
- Food
- Beverages
- Pharmaceutical & Healthcare
- Personal Care & Cosmetics
- Automotive
- Building & Construction
- Others
By Geography
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- Italy
- U.K.
- Russia
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Rest of Asia-Pacific
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Middle East and Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Competitive Landscape
The rigid plastic packaging market is characterized by the presence of key players such as Amcor plc, Berry Global Inc., Sonoco Products Company, Sealed Air Corporation, DS Smith, ALPLA, Klöckner Pentaplast, Pactiv Evergreen Inc., WINPAK LTD, Nuplas Industries, and Genpak. These companies focus on developing lightweight, recyclable, and sustainable packaging solutions to meet rising consumer and regulatory demands. Industry leaders are investing in advanced molding technologies, such as injection and thermoforming, to enhance product strength and reduce material usage. Strategic mergers, capacity expansions, and regional manufacturing facilities are strengthening their global footprint. Increasing adoption of rPET, rPP, and bioplastics reflects a shift toward eco-friendly production practices. Companies also emphasize customized packaging designs to serve diverse sectors including food, beverages, pharmaceuticals, and personal care. Strong competition and growing sustainability requirements continue to drive innovation, operational efficiency, and product differentiation across the rigid plastic packaging market.
Key Player Analysis
- Amcor plc
- Berry Global Inc.
- Sonoco Products Company
- Sealed Air Corporation
- DS Smith
- ALPLA
- Klöckner Pentaplast
- Pactiv Evergreen Inc.
- WINPAK LTD
- Nuplas Industries
- Genpak
Recent Developments
- In 2024, Klöckner Pentaplast introduced new recyclable barrier flow-wrap films containing 95% single-material content.
- In 2023, Berry Global continued to expand its portfolio of sustainable packaging solutions, including products made from post-consumer recycled (PCR) resin.
- In 2023, Sealed Air Corporation, now operating under the brand SEE, introduced new barrier technologies under its CRYOVAC brand for recyclable shrink bags and rollstock
Report Coverage
The research report offers an in-depth analysis based on Type, Material, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for recyclable and lightweight rigid plastic packaging will continue to rise globally.
- Bioplastic adoption will increase as brands seek to reduce carbon emissions.
- Advanced molding technologies will improve design precision and material efficiency.
- Integration of smart and connected packaging will enhance supply chain transparency.
- Circular economy policies will push manufacturers toward closed-loop production systems.
- Growth in e-commerce and food delivery will expand packaging consumption.
- Partnerships between resin producers and recyclers will strengthen material recovery networks.
- Regional manufacturing hubs will shift toward energy-efficient and low-emission facilities.
- Consumer preference for eco-friendly and refillable packaging will shape product innovation.
- Emerging economies in Asia and Latin America will offer significant expansion opportunities.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Rigid Plastic Packaging Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Rigid Plastic Packaging Market projected to grow between 2025 and 2032?
Which Rigid Plastic Packaging Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Rigid Plastic Packaging Market?
Who are the leading companies in the Rigid Plastic Packaging Market?
Which region commanded the largest share of the Rigid Plastic Packaging Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 185.49 million → 2032: USD 265.81 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Rigid Plastic Packaging Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Rigid Plastic Packaging Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Rigid Plastic Packaging Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Rigid Plastic Packaging Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Rigid Plastic Packaging Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Rigid Plastic Packaging Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Rigid Plastic Packaging Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Rigid Plastic Packaging Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 185.49 million → 2032: USD 265.81 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Rigid Plastic Packaging Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Rigid Plastic Packaging Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Rigid Plastic Packaging Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Rigid Plastic Packaging Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

