
Market Overview
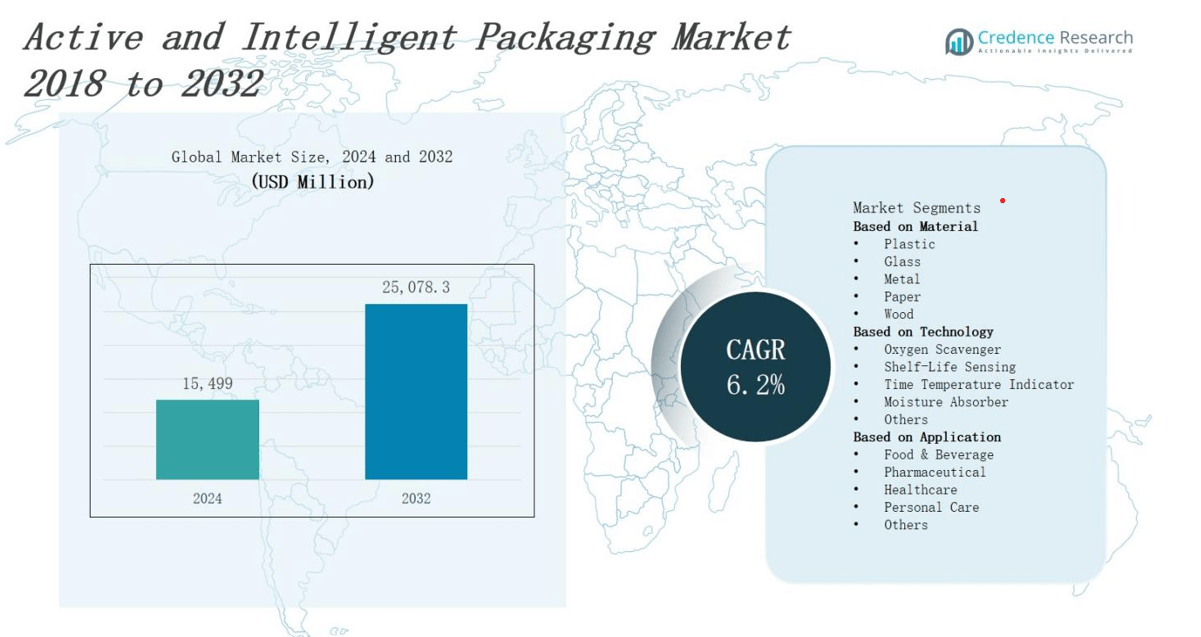
The active and intelligent packaging market is projected to grow from USD 15,499 million in 2024 to USD 25,078.3 million by 2032, expanding at a CAGR of 6.2%.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Active and Intelligent Packaging Market Size 2024 | USD 15,499 million |
| Active and Intelligent Packaging Market, CAGR | 6.2% |
| Active and Intelligent Packaging Market Size 2032 | USD 25,078.3 million |
The active and intelligent packaging market grows driven by increasing demand for enhanced product safety, extended shelf life, and improved consumer convenience across food, pharmaceutical, and cosmetic sectors. Rising regulatory requirements for product traceability and anti-counterfeiting solutions propel adoption. Innovations in smart sensors, indicators, and nanotechnology enhance real-time monitoring of product conditions. Growing e-commerce and global supply chains increase the need for packaging that ensures authenticity and quality. Sustainability trends push manufacturers toward eco-friendly materials and recyclable smart packaging. These factors collectively stimulate continuous product development and widespread market expansion worldwide.
The active and intelligent packaging market spans key regions including North America, Europe, Asia Pacific, and the Rest of the World. North America leads with 35% market share, driven by advanced industries and strict regulations. Europe follows with 28%, emphasizing sustainability and innovation. Asia Pacific holds 22%, fueled by rapid urbanization and growing consumer demand. The Rest of the World accounts for 15%, showing emerging growth potential. Key players in this market include Amcor PLC, Crown Holdings Inc, Mitsubishi Gas Chemical Co, Constar International Inc, Ball Corporation, 3M Company, Coveris Holdings SA, Sealed Air Corporation, LCR Hall Crest LLC, and Varcode Ltd.
Market Insights
- The active and intelligent packaging market is projected to grow from USD 15,499 million in 2024 to USD 25,078.3 million by 2032, at a CAGR of 6.2%.
- Increasing demand for enhanced product safety, extended shelf life, and improved consumer convenience drives growth across food, pharmaceutical, and cosmetic sectors.
- Strict regulatory requirements for product traceability and anti-counterfeiting boost adoption of smart packaging technologies like RFID tags, QR codes, and sensors.
- Innovations in nanotechnology, smart sensors, and indicators improve real-time monitoring of product conditions, enhancing freshness and authenticity verification.
- Growth in e-commerce and global supply chains increases the need for packaging that protects product quality during shipping and storage.
- Sustainability trends encourage the use of recyclable, biodegradable, and eco-friendly smart packaging materials, aligning with environmental goals.
- North America leads the market with 35% share, followed by Europe at 28%, Asia Pacific at 22%, and the Rest of the World at 15%, driven by industrial advancement, regulatory compliance, and emerging consumer demand.
Market Drivers
Rising Demand for Enhanced Product Safety and Shelf Life
The active and intelligent packaging market benefits from growing consumer focus on product safety and freshness. It addresses the need to extend shelf life by controlling factors such as oxygen, moisture, and microbial growth. Manufacturers adopt packaging solutions that actively interact with the product to maintain quality during storage and transportation. This demand increases especially in the food and pharmaceutical sectors, where product integrity is critical. The ability to reduce food waste through longer freshness also supports market growth. It encourages companies to innovate packaging technologies that ensure product safety from production to consumption.
- For instance, Tetra Pak’s Direct UHT technology allows beverages like coconut water to be sterilized quickly at high temperatures, extending shelf life to up to 12 months without refrigeration.
Stringent Regulatory Requirements and Traceability
Regulatory bodies worldwide enforce strict guidelines to ensure product safety, authenticity, and traceability. The active and intelligent packaging market supports compliance with these standards through smart packaging technologies like RFID tags, QR codes, and sensors. These features enable real-time monitoring and anti-counterfeiting measures, enhancing supply chain transparency. It helps manufacturers and retailers track product conditions and prevent fraud. Compliance pressures in sectors like pharmaceuticals and food drive the adoption of intelligent packaging solutions, making regulatory requirements a significant growth factor for the market.
Technological Innovations in Smart Packaging Solutions
Technological advances in nanotechnology, biosensors, and wireless communication accelerate growth in the active and intelligent packaging market. These innovations enable packaging to detect spoilage, temperature changes, and contamination effectively. The integration of sensors and indicators provides consumers and supply chain stakeholders with real-time product information. It enhances user experience and trust by delivering freshness status and authenticity verification. Continuous improvements in cost efficiency and functionality expand applications across various industries, driving broader acceptance and commercial success for intelligent packaging.
- For instance, Multisorb Technologies provides active packaging materials such as oxygen absorbers and desiccant labels that extend shelf life and maintain product integrity for pharmaceuticals, food, and dietary supplements.
Growing E-commerce and Sustainability Concerns
The rise of e-commerce intensifies demand for packaging that protects products during extended shipping and storage periods. The active and intelligent packaging market addresses this by offering solutions that maintain product quality throughout complex distribution networks. Sustainability concerns also influence market growth, with manufacturers seeking recyclable, biodegradable, and eco-friendly materials integrated with smart features. It aligns with global efforts to reduce packaging waste and environmental impact. These factors motivate companies to develop innovative packaging that balances performance with sustainability, fueling further market expansion.
Market Trends
Integration of IoT and Advanced Sensor Technologies
The active and intelligent packaging market increasingly incorporates Internet of Things (IoT) and advanced sensor technologies to enhance real-time monitoring. It enables continuous tracking of temperature, humidity, and product freshness throughout the supply chain. These smart features improve transparency and allow timely decision-making to reduce spoilage and waste. Companies focus on developing low-cost, reliable sensors that communicate product status to manufacturers, retailers, and consumers. This trend drives innovation and adoption across food, pharmaceutical, and cosmetics sectors, meeting rising demands for quality assurance.
- For instance, Amcor integrates digital printing with NFC technology in its packaging to provide real-time tracking and authentication of products, enhancing transparency for manufacturers and consumers.
Expansion of Sustainable and Eco-Friendly Packaging Solutions
Sustainability drives innovation in the active and intelligent packaging market, pushing companies toward eco-friendly materials and designs. It integrates biodegradable substrates, recyclable components, and non-toxic additives with intelligent features. Manufacturers develop packaging solutions that reduce environmental impact without compromising functionality. Growing consumer awareness and regulatory pressure encourage adoption of green packaging alternatives. This trend fosters collaboration between material scientists and technology providers to deliver smart packaging that supports circular economy principles and minimizes waste throughout the product lifecycle.
- For instance, Nestlé has partnered with IBM and The Rainforest Alliance to develop blockchain-enabled smart packaging that enhances transparency by allowing consumers to trace the entire product journey, integrating sustainability with intelligent features.
Adoption of Anti-Counterfeiting and Brand Protection Technologies
The active and intelligent packaging market experiences increased adoption of anti-counterfeiting and brand protection technologies due to rising concerns about product fraud. It uses features like holograms, RFID tags, and QR codes to ensure authenticity and protect brand reputation. These technologies help track products and authenticate them at various points in the supply chain. Companies invest in secure packaging solutions to prevent counterfeiting, especially in pharmaceuticals and luxury goods. This trend enhances consumer confidence and supports regulatory compliance globally.
Growth in Personalized and Consumer-Interactive Packaging
Personalization and consumer engagement emerge as key trends in the active and intelligent packaging market. It incorporates interactive elements like NFC tags and augmented reality to deliver customized content and enhance user experience. Brands leverage these technologies to build loyalty and provide product information directly to consumers. The trend aligns with increasing demand for transparency and meaningful interactions in purchasing decisions. Companies prioritize packaging that combines functionality with marketing to differentiate products in competitive markets, driving innovation and market growth.
Market Challenges Analysis
High Costs and Complex Implementation Processes
The active and intelligent packaging market faces challenges due to high production and material costs. Integrating advanced technologies such as sensors, indicators, and communication modules increases overall packaging expenses. It limits adoption, especially among small and medium-sized enterprises with constrained budgets. Complex manufacturing processes and the need for specialized equipment further slow implementation. Companies must invest in research and development to improve cost-efficiency and scalability. Overcoming these financial and operational barriers remains critical for broader market penetration and commercialization.
Regulatory and Standardization Barriers Across Regions
Regulatory complexities and the lack of unified standards create obstacles for the active and intelligent packaging market. It must comply with varying guidelines across countries regarding safety, data privacy, and environmental impact. This fragmented regulatory landscape complicates global distribution and increases time-to-market. Differences in certification requirements and testing protocols also hinder rapid innovation. Industry stakeholders need coordinated efforts to establish harmonized standards. Addressing these regulatory challenges will facilitate smoother adoption and foster international growth opportunities.
Market Opportunities
Expansion into Emerging Markets and Diverse Industries
The active and intelligent packaging market holds significant opportunities in emerging economies with growing consumer awareness and rising disposable incomes. It can capitalize on expanding food, pharmaceutical, and cosmetic industries seeking advanced packaging solutions. Increasing urbanization and modernization of supply chains in these regions drive demand for product safety and traceability. Companies that tailor products to local requirements and invest in market education will gain competitive advantages. Penetrating diverse sectors such as healthcare, agriculture, and electronics further broadens growth potential and creates new revenue streams.
Advancements in Smart Materials and Digital Technologies
Technological progress in smart materials and digital integration offers vast opportunities for the active and intelligent packaging market. It can leverage innovations like biodegradable sensors, printed electronics, and blockchain for enhanced functionality and sustainability. These developments enable improved real-time monitoring, anti-counterfeiting, and consumer interaction. Collaborations between material scientists, technology firms, and packaging manufacturers accelerate product innovation. Expanding the use of data analytics and connectivity will create smarter, more responsive packaging systems. Exploiting these advancements will strengthen market position and drive future expansion.
Market Segmentation Analysis:
By Material
The active and intelligent packaging market segments by material into plastic, glass, metal, paper, and wood. Plastic dominates due to its versatility, lightweight nature, and cost-effectiveness. It supports integration of sensors and indicators while maintaining durability. Glass and metal provide superior barrier properties, making them suitable for premium and pharmaceutical products. Paper and wood appeal to sustainability-driven markets, offering eco-friendly alternatives that combine with intelligent features. Material choice influences packaging functionality, cost, and environmental impact, guiding manufacturers’ product development strategies.
- For instance, plastic containers in the US use thermochromic ink dots that indicate syrup temperature after microwave heating, enhancing consumer convenience and safety.
By Technology
The active and intelligent packaging market divides by technology into oxygen scavengers, shelf-life sensing, time temperature indicators, moisture absorbers, and others. Oxygen scavengers lead demand by preventing oxidation and preserving product freshness, especially in food and pharmaceuticals. Shelf-life sensing and time temperature indicators provide real-time product condition information, supporting quality assurance and regulatory compliance. Moisture absorbers protect against humidity-related spoilage. Emerging technologies enhance packaging intelligence, enabling precise monitoring and extending application scope across industries.
- For instance, Senoptica’s FDA-approved optical oxygen sensors integrated into modified atmosphere packaging help detect oxygen levels inside food packs, ensuring freshness of bagged salads, sliced meats, cheese, and dairy products by identifying leaks early.
By Application
The active and intelligent packaging market segments into food & beverage, pharmaceutical, healthcare, personal care, and other applications. Food & beverage represents the largest segment due to high demand for freshness, safety, and waste reduction. Pharmaceutical packaging requires strict compliance, driving adoption of traceability and anti-counterfeiting features. Healthcare and personal care sectors seek innovative packaging that enhances user convenience and product integrity. Growing application diversity fuels market expansion, with customized solutions addressing specific industry requirements and consumer expectations.
Segments:
Based on Material
- Plastic
- Glass
- Metal
- Paper
- Wood
Based on Technology
- Oxygen Scavenger
- Shelf-Life Sensing
- Time Temperature Indicator
- Moisture Absorber
- Others
Based on Application
- Food & Beverage
- Pharmaceutical
- Healthcare
- Personal Care
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds the largest share of the active and intelligent packaging market with 35%. It benefits from a strong pharmaceutical industry, advanced food processing sector, and high consumer awareness of product safety and sustainability. Stringent regulatory frameworks drive adoption of smart packaging technologies for traceability and anti-counterfeiting. Well-established supply chains and investments in R&D support continuous innovation. Major companies headquartered in this region accelerate market growth by introducing advanced packaging solutions. Demand from e-commerce and retail sectors further fuels expansion. North America remains a critical region for market development and technology leadership.
Europe
Europe commands 28% of the active and intelligent packaging market. It emphasizes sustainability and regulatory compliance, encouraging widespread use of eco-friendly smart packaging. The region leads in implementing advanced packaging standards for pharmaceuticals and food safety. Growing consumer preference for transparency and interactive packaging drives innovation. Well-developed manufacturing infrastructure supports quick adoption of new technologies. Investments in green materials combined with intelligent features position Europe as a key market for sustainable packaging solutions. Collaborative efforts between governments and industry stakeholders accelerate market progress.
Asia Pacific
Asia Pacific accounts for 22% of the active and intelligent packaging market. Rapid urbanization, increasing disposable income, and expanding food and pharmaceutical sectors fuel demand. The region experiences rising awareness about product safety and quality, encouraging adoption of intelligent packaging. Emerging economies invest in modernizing supply chains and regulatory frameworks. Companies focus on cost-effective packaging solutions tailored for local markets. Asia Pacific offers significant growth opportunities due to its large consumer base and expanding industrial capabilities. Market players actively target this region to capture emerging demand.
Rest of the World
The Rest of the World holds 15% of the active and intelligent packaging market. Growth stems from increasing industrialization and rising consumer awareness in Latin America, the Middle East, and Africa. These regions show growing interest in packaging solutions that enhance product safety and reduce waste. Investments in healthcare and food industries further support demand. Challenges in infrastructure and regulatory harmonization limit rapid adoption but create opportunities for innovative, adaptable technologies. Market participants focus on strategic partnerships and local collaborations to strengthen their presence in these emerging markets.
Key Player Analysis
- Varcode Ltd
- Crown Holdings Inc
- Sealed Air Corporation
- Ball Corporation
- Amcor PLC
- LCR Hall Crest LLC
- Mitsubishi Gas Chemical Co
- 3M Company
- Constar International Inc
- Coveris Holdings SA
Competitive Analysis
The active and intelligent packaging market features intense competition among global and regional players focusing on innovation, product differentiation, and strategic partnerships. Leading companies invest heavily in research and development to introduce advanced packaging technologies, such as sensors, indicators, and RFID tags, that enhance product safety and consumer engagement. It experiences consolidation through mergers and acquisitions to expand product portfolios and geographic reach. Companies emphasize sustainable and eco-friendly packaging solutions to meet growing regulatory and consumer demands. Strong distribution networks and collaborations with food, pharmaceutical, and personal care industries enable market leaders to maintain competitive advantages. Continuous innovation, cost optimization, and responsiveness to changing market needs remain critical for sustaining growth and capturing new opportunities in the evolving active and intelligent packaging market.
Recent Developments
- In June 2025, Amcor launched a sustainable shrink bag for Butterball's turkey breast packaging, enhancing product freshness and reducing environmental impact.
- In June 2024, Varcode announced a strategic partnership with National Packaging Group (NPG) to develop and distribute smart packaging solutions for temperature-sensitive products.
- In June 2025, Ball Corporation partnered with Açaí Motion to introduce ASI-certified aluminum cans, aligning with sustainability goals and enhancing product traceability.
- In June 2023, Sealed Air launched a new line of smart packaging solutions integrating IoT-enabled sensors for real-time monitoring and data analytics, enhancing product traceability and consumer engagement.
Market Concentration & Characteristics
The active and intelligent packaging market exhibits a moderately concentrated structure, dominated by a few global players who drive innovation and set industry standards. Leading companies focus on technological advancements, product differentiation, and strategic collaborations to maintain competitive advantages. It experiences ongoing consolidation through mergers and acquisitions to expand market reach and enhance product portfolios. The market favors companies that invest heavily in research and development to introduce advanced packaging solutions integrating sensors, indicators, and communication technologies. Customer demand for sustainable and smart packaging further shapes competitive dynamics. Strong distribution networks and partnerships with key end-use sectors, including food, pharmaceutical, and personal care, strengthen market positions. Emerging players face challenges due to high entry barriers, including cost and regulatory compliance. The active and intelligent packaging market rewards innovation, agility, and scalability, encouraging continuous improvement to meet evolving consumer and regulatory expectations.
Report Coverage
The research report offers an in-depth analysis based on Material, Application, Technolgoy and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The active and intelligent packaging market will expand due to rising demand for product safety and freshness.
- Technological innovations in sensors and nanomaterials will enhance packaging functionality.
- Regulatory pressure will increase adoption of traceability and anti-counterfeiting solutions.
- Sustainability initiatives will drive development of eco-friendly and recyclable packaging materials.
- E-commerce growth will boost the need for packaging that protects products during transit.
- Integration of IoT and real-time monitoring technologies will become more widespread.
- Manufacturers will focus on cost-effective smart packaging to reach small and medium enterprises.
- Emerging markets will offer significant growth opportunities due to increasing urbanization and disposable incomes.
- Collaboration between packaging companies and technology providers will accelerate innovation.
- Personalized and interactive packaging will gain traction to improve consumer engagement and brand loyalty.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Enhanced Product Safety and Shelf Life
Active and intelligent packaging technologies such as oxygen scavengers and antimicrobial agents help extend shelf life and maintain product quality, which is especially critical in food and pharmaceutical sectors where safety and freshness are paramount.
Stringent Regulatory Requirements and Traceability
Increasing global regulations around product safety, traceability, and anti-counterfeiting are driving adoption of smart packaging solutions like RFID tags, QR codes, and sensors, enabling real-time monitoring and compliance across supply chains.
Technological Innovations in Smart Packaging
Advancements in nanotechnology, biosensors, and IoT integration are enabling packaging to provide real-time data on product conditions, spoilage, and authenticity, which enhances consumer trust and supports quality assurance.
Growth of E-commerce and Global Supply Chains
The expansion of e-commerce and complex global distribution networks increases the need for packaging that can monitor and protect product quality during transit, driving demand for intelligent packaging solutions.
Sustainability and Eco-Friendly Packaging Trends
Rising consumer and regulatory focus on sustainability is pushing manufacturers to develop recyclable, biodegradable, and eco-friendly smart packaging materials, aligning with environmental goals while maintaining advanced functionality.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for active and intelligent packaging, and what is its projected size in 2032?
What are the primary factors fueling the growth of the active and intelligent packaging market?
Who are the leading companies in the active and intelligent packaging market?
Which region commanded the largest share of the active and intelligent packaging market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Material
- 1.2.1 Plastic
- 1.2.2 Glass
- 1.2.3 Metal
- 1.2.4 Paper
- 1.2.5 Wood
- 1.3 By Technology
- 1.3.1 Oxygen Scavenger
- 1.3.2 Shelf-Life Sensing
- 1.3.3 Time Temperature Indicator
- 1.3.4 Moisture Absorber
- 1.3.5 Others
- 1.4 By Application
- 1.4.1 Food & Beverage
- 1.4.2 Pharmaceutical
- 1.4.3 Healthcare
- 1.4.4 Personal Care
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 15,499 million → 2032: USD 25,078.3 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Active and Intelligent Packaging Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Active and Intelligent Packaging Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Active and Intelligent Packaging Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Active and Intelligent Packaging Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Active and Intelligent Packaging Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Active and Intelligent Packaging Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Active and Intelligent Packaging Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Active and Intelligent Packaging Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 15,499 million → 2032: USD 25,078.3 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Active and Intelligent Packaging Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Material - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Plastic
- 12.3.7.2 Glass
- 12.3.7.3 Metal
- 12.3.7.4 Paper
- 12.3.7.5 Wood
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Oxygen Scavenger
- 12.4.7.2 Shelf-Life Sensing
- 12.4.7.3 Time Temperature Indicator
- 12.4.7.4 Moisture Absorber
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Food & Beverage
- 12.5.7.2 Pharmaceutical
- 12.5.7.3 Healthcare
- 12.5.7.4 Personal Care
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Active and Intelligent Packaging End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Active and Intelligent Packaging Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Active and Intelligent Packaging Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Active and Intelligent Packaging Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Amcor PLC
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Crown Holdings Inc
- 18.4 Mitsubishi Gas Chemical Co
- 18.5 Constar International Inc
- 18.6 Ball Corporation
- 18.7 3M Company
- 18.8 Coveris Holdings SA
- 18.9 Sealed Air Corporation
- 18.10 LCR Hall Crest LLC
- 18.11 Varcode Ltd
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

