
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Active Battery Cell Balancing Market Size 2024 | USD 2,100 million |
| Active Battery Cell Balancing Market, CAGR | 13.7% |
| Active Battery Cell Balancing Market Size 2032 | USD 5865 million |
Market Overview:
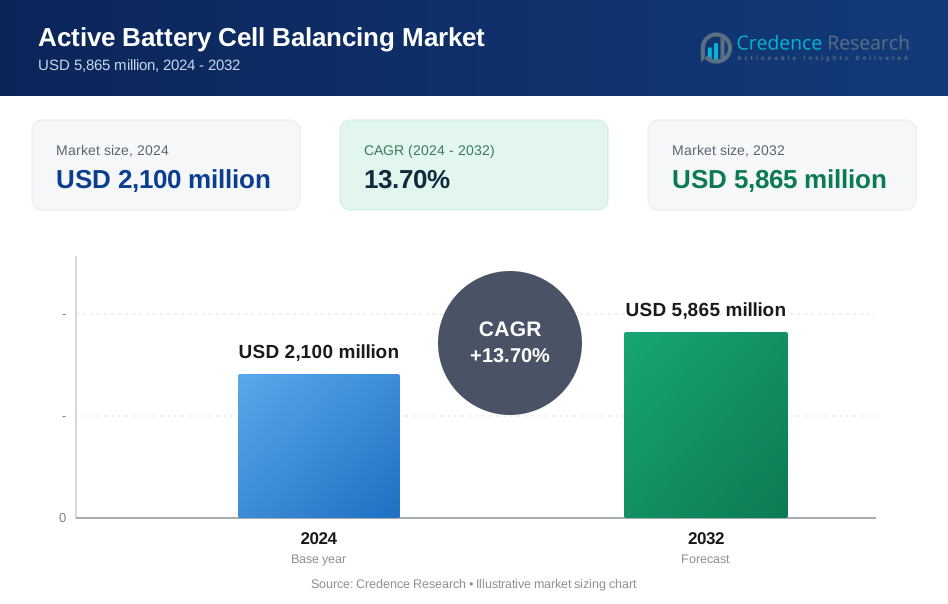
Active Battery Cell Balancing Market size was valued at USD 2,100 million in 2024 and is anticipated to reach USD 5865 million by 2032, at a CAGR of 13.7% during the forecast period (2024-2032).
The market is driven by the rising demand for electric vehicles, which rely heavily on lithium-ion batteries for optimal performance and range. As battery pack complexity increases, manufacturers are turning to active balancing technologies to enhance charge uniformity and overall energy efficiency. Additionally, the growing deployment of renewable energy storage systems is increasing the need for advanced battery management solutions that can maintain system stability and reliability over long cycles. Regulatory mandates aimed at improving energy efficiency and reducing emissions further support market expansion. Continued innovations in battery chemistries, such as solid-state batteries, are also pushing the adoption of advanced battery management systems that require precise balancing mechanisms. The need to reduce total cost of ownership and improve battery safety standards is also encouraging industries to adopt active balancing technologies. Increased R&D investment by major players is accelerating commercialization and technological upgrades in this domain.
Regionally, Asia-Pacific holds the largest share of the Active Battery Cell Balancing Market, driven by the dominance of battery production hubs in China, South Korea, and Japan. The region's strong EV manufacturing base and aggressive government policies supporting clean energy transitions are key contributors to this growth. North America follows closely, supported by federal EV incentives and increasing investments in battery storage infrastructure. Europe is also witnessing notable growth, propelled by stringent environmental regulations, a growing EV ecosystem, and strategic collaborations between automotive OEMs and battery technology providers. Rising local production capabilities and cross-border technology partnerships are helping boost regional competitiveness. Governments across all key markets are also funding pilot projects and subsidies to accelerate battery technology innovation and adoption.
Market Insights:
- The Active Battery Cell Balancing Market was valued at USD 2,100 million in 2024 and is expected to reach USD 5,865 million by 2032, driven by the growing use of electric vehicles and energy storage systems.
- Rising EV adoption is pushing demand for active balancing to extend battery life, improve charge uniformity, and support longer driving ranges.
- Deployment of renewable energy storage systems, such as solar and wind, is creating the need for efficient battery management to ensure grid stability.
- Technological advancements, including AI integration and compact circuit designs, are enhancing the performance, responsiveness, and scalability of balancing systems.
- Governments across key regions are enforcing regulations to cut emissions and boost energy efficiency, making active battery balancing essential in EV and energy infrastructure.
- High implementation costs and technical complexity remain challenges, especially for low-cost applications, although companies are introducing new cost-efficient solutions.
- Asia-Pacific leads the market with 49% share, followed by North America at 26% and Europe at 19%, driven by strong production bases, innovation, and policy incentives in these regions.
Market Drivers:
Rising Adoption of Electric Vehicles Fueling Demand for Advanced Battery Management:
The rapid adoption of electric vehicles (EVs) is a primary driver of the Active Battery Cell Balancing Market. EVs rely on high-capacity lithium-ion batteries, where uniform cell performance is essential to ensure vehicle range and battery life. Active balancing systems offer greater energy efficiency by redistributing excess charge rather than dissipating it, thus maximizing battery utilization. With automakers expanding EV portfolios and governments promoting zero-emission transportation, the need for robust and efficient battery management solutions is accelerating. It supports energy conservation within battery systems, making it a critical technology for next-generation mobility. Growing demand for longer driving ranges and shorter charging times is increasing the relevance of active cell balancing in the EV segment.
Expansion of Renewable Energy Storage Infrastructure Requiring Efficient Battery Balancing:
The growing scale of renewable energy deployments is driving the need for advanced battery management across solar and wind storage systems. Energy storage systems are becoming essential for grid stability and energy distribution, and they demand highly reliable battery performance. The Active Battery Cell Balancing Market benefits from this trend, as it provides a solution to optimize charge cycles, prevent cell degradation, and extend battery service life. It ensures efficient energy use and reduces the likelihood of system failures in large-scale installations. Integration of battery storage in smart grids and microgrids further highlights the importance of maintaining consistent cell performance. Energy infrastructure developers are prioritizing active balancing solutions to ensure long-term operational efficiency.
- For instance, the U.S. Department of Energy has supported the installation of advanced battery energy storage systems at the Hornsdale Power Reserve in South Australia, where active cell balancing is used to stabilize the grid and support renewable energy integration.
Technological Advancements Enhancing Performance and Cost Efficiency:
Rapid developments in battery chemistry and power electronics are reinforcing the adoption of active balancing technologies. Improvements in balancing circuits, microcontrollers, and communication protocols have made systems more compact, cost-effective, and responsive. The Active Battery Cell Balancing Market is responding to industry demands for scalable, adaptable solutions across various battery types. It is helping manufacturers meet evolving design requirements in EVs, industrial equipment, and energy storage applications. These technological strides are reducing production costs and increasing the feasibility of integration at scale. Companies are also leveraging AI and machine learning to improve predictive analytics and real-time control in battery management.
- For instance, General Motors has integrated advanced active battery cell balancing and AI-driven monitoring in its Ultium battery platform, enabling efficient energy distribution and improved battery health across its electric vehicle lineup.
Regulatory Push for Emissions Reduction and Energy Efficiency:
Stringent global regulations aimed at reducing carbon emissions and enhancing energy efficiency are promoting the use of high-performance battery management systems. Government policies across major economies are mandating better energy utilization and stricter safety standards in automotive and energy sectors. The Active Battery Cell Balancing Market aligns well with these objectives by enabling better battery health monitoring and lifespan extension. It helps meet compliance requirements while delivering economic and environmental benefits. Public and private sector initiatives are supporting the deployment of cleaner energy technologies, increasing the appeal of active balancing systems. Regulatory pressure continues to accelerate the shift toward advanced battery infrastructure and smarter energy ecosystems.
Market Trends:
Integration of AI and Real-Time Monitoring Enhancing System Intelligence:
The integration of artificial intelligence (AI) and real-time data monitoring is becoming a defining trend in the Active Battery Cell Balancing Market. Advanced algorithms are being deployed to track individual cell performance, enabling predictive maintenance and dynamic load balancing across battery systems. AI enhances decision-making capabilities within battery management systems, allowing them to respond more efficiently to fluctuations in charge and discharge cycles. It is helping manufacturers reduce failure rates, improve safety standards, and extend battery longevity. The market is seeing increased adoption of cloud-based platforms that offer remote diagnostics and software updates, supporting greater system adaptability. This digital transformation is elevating the role of battery balancing from basic energy redistribution to a critical component of intelligent energy storage ecosystems.
- For instance, NXP Semiconductors has developed an AI-powered cloud-connected battery management system using its S32G GoldBox and Electra Vehicles, Inc.’s EVE-Ai™ 360 Adaptive Controls, which leverages digital twin models for real-time battery health prediction and optimization in electric vehicles.
Miniaturization and Modular Design Broadening Application Scope:
The trend toward miniaturization and modular battery pack designs is creating new growth avenues for the Active Battery Cell Balancing Market. Manufacturers are developing more compact and scalable balancing circuits to support space-constrained applications in portable electronics, drones, and compact EVs. It enables system integrators to deploy active balancing technologies in a wider range of use cases without compromising performance. Modular architectures are also gaining traction, allowing users to customize battery systems with flexible configurations that suit specific energy and load requirements. This design shift is encouraging rapid prototyping and easier integration in diverse industries. The ability to adapt balancing systems across varied voltage ranges and cell counts is strengthening the market's relevance in emerging battery-driven technologies.
- For instance, modular battery systems from companies like HyperDrive Innovation and Turntide Technologies enable rapid scalability and flexible deployment for automotive, industrial, and e-mobility applications.
Market Challenges Analysis:
High Implementation Costs and Design Complexity Restricting Adoption:
The high cost of implementing active balancing systems remains a significant challenge in the Active Battery Cell Balancing Market. Unlike passive balancing, active solutions require complex circuitry, advanced microcontrollers, and energy transfer components, which increase overall system cost. It poses a barrier, especially for low-cost battery applications in consumer electronics or smaller electric vehicles. Design complexity further adds to the difficulty, requiring precise integration with battery management systems to ensure stable operation. Manufacturers must invest in specialized engineering resources, which can slow product development and limit scalability. These factors are compelling some end-users to continue relying on traditional balancing methods despite their limitations.
- For instance, Analog Devices has introduced advanced active cell balancers like the LTC3300, which enable efficient charge redistribution and support higher balancing currents for large-scale battery systems.
Lack of Standardization and Technical Barriers Across Battery Chemistries:
The absence of standard protocols and design guidelines across different battery chemistries presents another challenge. Each battery type—whether lithium-ion, solid-state, or LFP—requires distinct balancing strategies, making universal system compatibility difficult. The Active Battery Cell Balancing Market faces technical hurdles in creating flexible solutions that perform reliably across varied configurations. It limits interoperability and raises the cost and complexity of system validation. Variations in charge-discharge behaviors across cells also increase the difficulty in designing universally adaptable active balancing systems. Without standardization, market penetration across broader application areas may remain constrained.
Market Opportunities:
Growing Demand for Long-Range EVs and Battery Longevity Creates New Avenues:
The increasing demand for long-range electric vehicles and extended battery life presents a strong opportunity for the Active Battery Cell Balancing Market. Automakers are under pressure to enhance vehicle performance without compromising safety or durability. Active balancing supports these goals by ensuring uniform charge distribution and minimizing cell degradation over time. It allows for optimal utilization of every cell, which translates into greater energy efficiency and longer operating ranges. As competition intensifies in the EV sector, manufacturers are likely to invest more in advanced battery management technologies. This trend positions active balancing as a key enabler of next-generation electric mobility.
Expansion of Energy Storage Systems Across Industrial and Utility Applications:
The global push toward renewable energy and grid decentralization is driving large-scale deployment of energy storage systems. These systems require precise battery control to manage fluctuating loads and long discharge cycles. The Active Battery Cell Balancing Market has a significant opportunity in this space, as it supports enhanced cycle life and system reliability. It plays a vital role in stabilizing battery modules in solar, wind, and hybrid storage facilities. The market stands to benefit from growing investments in utility-scale projects and smart grid technologies. Customizable and scalable active balancing solutions are expected to gain traction among energy infrastructure providers.
Market Segmentation Analysis:
By Type
The Active Battery Cell Balancing Market, by type, includes inductive, capacitive, and others. Inductive balancing holds the largest market share due to its high efficiency in transferring energy between cells without dissipating it as heat. It is preferred in electric vehicle battery systems and large-scale energy storage solutions where energy retention and system longevity are priorities. Capacitive balancing is gaining momentum in consumer electronics and lower-voltage applications due to its simpler circuitry and lower cost. It is suitable for compact devices where moderate balancing precision suffices. The “others” category, which includes hybrid systems and emerging architectures, is expanding in niche applications that demand flexible, adaptive balancing across varying cell configurations.
By Application
By application, the Active Battery Cell Balancing Market is segmented into electric vehicles, energy storage systems, consumer electronics, and industrial equipment. Electric vehicles represent the largest segment, driven by the need to maximize battery efficiency, range, and lifespan. Manufacturers prioritize active balancing in EVs to ensure charge uniformity across increasingly complex battery packs. Energy storage systems, particularly in renewable integration and backup power, form the second-largest segment. It supports long cycle life and high reliability in grid-scale storage. Consumer electronics and industrial equipment are growing steadily, driven by rising demand for smart devices, robotics, and power tools. Each segment continues to adopt active balancing to meet performance, safety, and durability expectations.
Segmentations:
By Type
- Inductive Balancing
- Capacitive Balancing
- Others
By Application
- Electric Vehicles
- Energy Storage Systems
- Consumer Electronics
- Industrial Equipment
By Region
- North America
- S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
Asia-Pacific Leads Due to Strong Manufacturing Capabilities and EV Ecosystem
Asia-Pacific holds 49% of the Active Battery Cell Balancing Market, driven by its dominant position in battery production and widespread adoption of electric vehicles. China, Japan, and South Korea lead global lithium-ion battery manufacturing and export, fueling strong demand for energy-efficient balancing solutions. It benefits from government-backed initiatives promoting clean transportation and renewable energy integration. Regional manufacturers are investing in compact, high-performance balancing systems to support evolving EV and energy storage needs. The presence of major OEMs and suppliers ensures innovation and large-scale deployment. Infrastructure growth in emerging economies such as India and Vietnam is further boosting regional demand.
North America Benefits from Technological Innovation and Policy Incentives
North America accounts for 26% of the Active Battery Cell Balancing Market, supported by a strong ecosystem of innovation and clean energy policies. The United States and Canada are actively funding EV expansion, grid upgrades, and advanced battery technologies. It is home to several companies and startups developing intelligent balancing systems tailored for automotive, aerospace, and industrial applications. Demand for high-performance battery management continues to rise across sectors that require safety, reliability, and long life. Regional initiatives in battery recycling and domestic production are also strengthening market growth. Strategic collaborations between automakers and tech providers are accelerating the adoption of advanced battery systems.
Europe Expands Through Regulatory Pressure and Energy Transition Goals
Europe holds 19% of the Active Battery Cell Balancing Market, driven by its commitment to carbon neutrality and energy transformation. Countries including Germany, France, and the Netherlands are investing in EV infrastructure and grid-scale battery storage to meet emissions targets. It is seeing increased cooperation between OEMs and battery developers to improve energy management and safety. Public investment under programs like Horizon Europe supports R&D in smart energy technologies. Growing application of battery systems in industrial automation and distributed generation is fueling further market expansion. Unified regulations across EU member states enable consistent and scalable deployment of active balancing solutions.
Key Player Analysis:
- Siemens
- ON Semiconductor
- Texas Instruments
- Maxim Integrated
- DIODES
- ADI
- Microchip
- Avago
- Intersil
- Renesas
Competitive Analysis:
The Active Battery Cell Balancing Market features a competitive landscape driven by technological innovation, product differentiation, and strategic partnerships. Key players include Texas Instruments, NXP Semiconductors, STMicroelectronics, Analog Devices, Renesas Electronics, and Infineon Technologies. These companies focus on developing high-efficiency balancing ICs and integrated battery management solutions that support scalability and system safety. The market also includes niche players offering specialized solutions for electric vehicles, energy storage systems, and industrial applications. It continues to evolve with rising demand for compact designs, enhanced thermal performance, and intelligent control features. Companies are investing in R&D and collaborating with EV manufacturers and energy solution providers to expand their market presence. The emphasis on energy efficiency, lifecycle extension, and reduced maintenance costs shapes the competitive strategy across the value chain. Firms that deliver customizable, software-integrated, and cost-effective balancing systems are gaining a stronger position in both established and emerging markets.
Recent Developments:
- In September 2024, Tata Electronics and ADI announced a strategic alliance to explore semiconductor manufacturing opportunities in India, including potential use of ADI products in Tata applications.
- In March 2025, Microchip announced the sale of its Tempe, Arizona wafer fabrication facility (“Fab 2”) as part of its operational optimization.
Market Concentration & Characteristics:
The Active Battery Cell Balancing Market exhibits moderate to high market concentration, with a few dominant players controlling significant market share through advanced technologies and strong distribution networks. It is characterized by rapid innovation, high R&D intensity, and evolving product standards tailored to specific battery chemistries and applications. The market favors companies with expertise in power electronics, integrated circuits, and battery management systems. Entry barriers remain high due to the complexity of design, safety requirements, and integration challenges. It demands continuous product improvement to meet the needs of electric vehicles, energy storage systems, and high-performance industrial equipment. The competitive environment encourages collaboration between component manufacturers and OEMs to deliver efficient, scalable, and cost-effective balancing solutions.
Report Coverage:
The research report offers an in-depth analysis based on Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Electric vehicle manufacturers will increasingly adopt active balancing systems to enhance battery efficiency and extend vehicle range.
- The expansion of renewable energy storage projects will drive demand for advanced battery management solutions, including active balancing technologies.
- Advancements in battery chemistries, such as lithium iron phosphate (LFP) and solid-state batteries, will necessitate more sophisticated balancing mechanisms to ensure optimal performance.
- Integration of artificial intelligence and machine learning in battery management systems will enable predictive maintenance and real-time optimization of cell balancing.
- The consumer electronics sector will see increased implementation of active balancing to support the growing need for longer-lasting and safer battery-powered devices.
- Industrial applications, including robotics and automation, will require robust balancing solutions to maintain operational efficiency and equipment longevity.
- Regulatory frameworks focusing on energy efficiency and sustainability will encourage the adoption of active balancing systems across various industries.
- Emerging markets will present new opportunities for active balancing technologies as they invest in electric mobility and renewable energy infrastructure.
- Collaborations between battery manufacturers and technology firms will accelerate the development of integrated balancing solutions tailored to specific applications.
- Continuous research and development efforts will lead to the creation of more compact, cost-effective, and efficient active balancing systems, broadening their applicability.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Active Battery Cell Balancing Market?
What is driving the growth of this market?
Which region leads the market?
What future trends are shaping this market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Active Battery Cell Balancing Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Active Battery Cell Balancing Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2,100 million → 2032: USD 5,865 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Active Battery Cell Balancing Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Active Battery Cell Balancing Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Active Battery Cell Balancing Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Active Battery Cell Balancing Market Drivers
- 3.3 Active Battery Cell Balancing Market Restraints & Challenges
- 3.4 Active Battery Cell Balancing Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Active Battery Cell Balancing Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Active Battery Cell Balancing Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Active Battery Cell Balancing category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Active Battery Cell Balancing Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Active Battery Cell Balancing Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Active Battery Cell Balancing market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Active Battery Cell Balancing Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Active Battery Cell Balancing Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Active Battery Cell Balancing Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Active Battery Cell Balancing (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Active Battery Cell Balancing Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Active Battery Cell Balancing Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Active Battery Cell Balancing Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Active Battery Cell Balancing Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Active Battery Cell Balancing Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Active Battery Cell Balancing Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Active Battery Cell Balancing Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Active Battery Cell Balancing Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Active Battery Cell Balancing Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
