
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Africa Electric Scooter Market Size 2024 | USD 106.5 million |
| Africa Electric Scooter Market, CAGR | 15.2% |
| Africa Electric Scooter Market Size 2032 | USD 330.35 million |
Market Overview
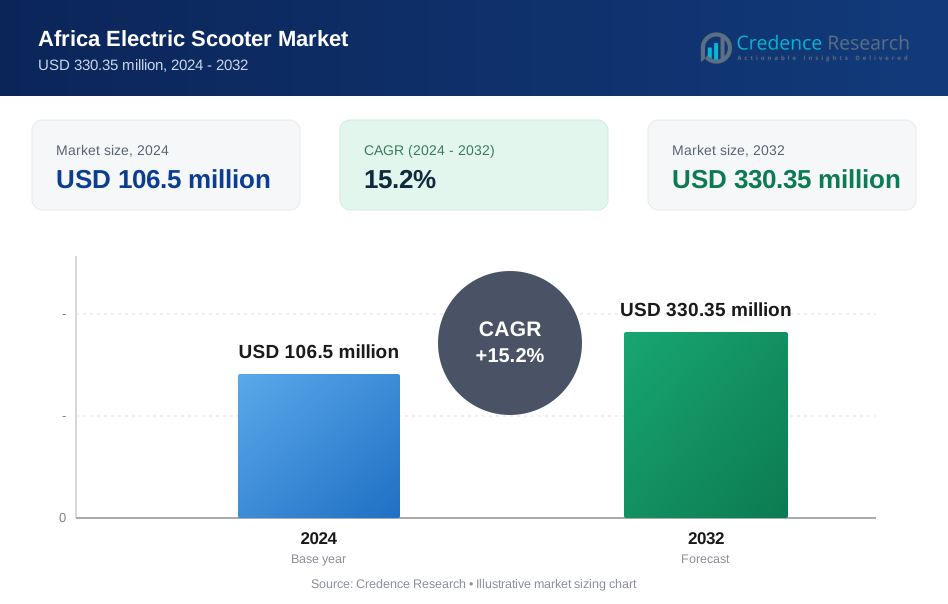
The Africa Electric Scooter Market is projected to grow from USD 106.5 million in 2024 to an estimated USD 330.35 million by 2032, with a compound annual growth rate (CAGR) of 15.2% from 2024 to 2032.
Key drivers of the Africa electric scooter market include rising urbanisation, increasing fuel prices, and the growing demand for affordable and sustainable transportation solutions. Government initiatives promoting electric mobility, such as incentives and subsidies for electric vehicle adoption, are further accelerating market growth. Additionally, advancements in battery technology, leading to improved energy efficiency and longer travel ranges, are enhancing consumer interest in electric scooters. The expansion of charging infrastructure across key urban centres is also playing a crucial role in supporting market adoption. The growing awareness of environmental sustainability and the need to reduce carbon emissions are pushing consumers and businesses toward electric mobility solutions. Fleet operators and ride-sharing platforms are increasingly investing in electric scooters to reduce operational costs and align with global sustainability goals. Furthermore, local manufacturers and startups are entering the market, offering cost-competitive electric scooters tailored to the region’s road and infrastructure conditions.
Regionally, South Africa, Nigeria, and Kenya are emerging as key markets for electric scooters due to their high urban population densities and government support for clean energy initiatives. North African countries, including Egypt and Morocco, are also experiencing growth, driven by increasing investments in green transportation projects. In East Africa, initiatives promoting electric two-wheelers for delivery services and public transport are fostering demand. Despite challenges such as high initial costs and limited charging infrastructure in some regions, the market is expected to expand significantly. Continued technological advancements, policy support, and growing consumer awareness will drive the widespread adoption of electric scooters across Africa in the coming years.
Market insights
- The Africa Electric Scooter Market is expected to grow significantly, from USD 106.5 million in 2024 to USD 330.35 million by 2032, driven by increasing demand for eco-friendly transportation solutions.
- Key drivers include the rising need for sustainable urban mobility options and government initiatives that promote electric vehicles through tax incentives and infrastructure support.
- The adoption of electric scooters is further supported by the growing concern over air pollution and the environmental impact of traditional fuel-powered vehicles.
- However, the market faces challenges such as high upfront costs, limited charging infrastructure, and a lack of consumer awareness, which could slow growth.
- African governments, particularly in countries like Kenya and Nigeria, are playing a key role in driving the adoption of electric scooters with policies aimed at reducing emissions and fostering green mobility.
- The rapid urbanisation across Africa is increasing demand for last-mile connectivity, making electric scooters a practical solution in crowded urban centres.
- Regionally, while major urban centres in Kenya, Nigeria, and South Africa are leading the market, rural areas face slower adoption due to limited infrastructure and awareness.
Market Drivers:
Environmental Concerns and Air Quality
Africa faces significant air pollution challenges, particularly in urban areas where traffic congestion and industrial activities contribute to poor air quality. Many African cities experience high levels of particulate matter and other harmful pollutants, which pose serious health risks to their populations. Transitioning to electric scooters offers an environmentally friendly alternative, helping to reduce these emissions significantly. Electric scooters produce zero tailpipe emissions, which can substantially improve air quality, particularly in densely populated urban environments. For instance, research has shown that cities adopting electric vehicles, including two-wheeled scooters, have seen a reduction of particulate matter emissions by up to 50%, leading to a considerable improvement in urban air quality. This shift not only reduces the carbon footprint but also decreases the reliance on fossil fuels, making electric scooters a sustainable transportation option.
Economic Benefits and Cost Savings
Electric scooters are gaining traction in Africa not just for their environmental benefits but also for their economic advantages. One of the major driving factors behind their adoption is the significant savings they offer in operating and maintenance costs when compared to traditional internal combustion engine (ICE) vehicles. Despite higher upfront costs, electric vehicles are cheaper to run and maintain over their lifespan. For example, studies have indicated that electric scooters can reduce fuel costs by up to 70% and maintenance costs by around 50%, making them a cost-effective alternative to gasoline-powered motorcycles and vehicles. These savings are particularly appealing to businesses and individuals looking for affordable and sustainable transportation options in rapidly growing urban centres.
Government Policies and Incentives
Governments across Africa are increasingly recognising the importance of electric mobility in reducing urban pollution and dependence on imported fossil fuels. As a result, many African governments are implementing supportive policies and incentives to promote the adoption of electric scooters. These measures include tax breaks, rebates, and support for the development of necessary infrastructure, such as charging stations. For instance, in Kenya, the government provides tax exemptions on electric vehicles, which has significantly boosted their adoption in urban centres, particularly in Nairobi. The government's active role in supporting electric mobility is essential in ensuring that electric scooters become an integral part of the transportation system.
Urbanisation and Transportation Demand
Africa's rapid urbanisation is driving an increasing demand for efficient, affordable, and sustainable transportation options. With more people migrating to cities, the need for transportation solutions that can address traffic congestion and provide last-mile connectivity is growing. Electric scooters offer a convenient solution, particularly in crowded cities where traffic jams and limited road infrastructure hinder the use of larger vehicles. For example, lightweight ride-hailing services, including motorbikes and rickshaws, are emerging in regions across Africa, offering practical solutions for last-mile connectivity in densely populated areas. In Nigeria, electric scooters are being integrated into urban transportation networks to address the high demand for such services. By providing a quick, affordable, and eco-friendly alternative to traditional transportation, electric scooters help reduce traffic congestion while meeting the transportation needs of urban populations.
Market Trends:
Adoption of Electric Mobility in Public Transportation
As African cities face challenges with traffic congestion and air pollution, there is an increasing shift towards electric mobility solutions in public transport. Many countries are integrating electric scooters into their public transportation systems to provide a sustainable and cost-effective last-mile connectivity option. For instance, in Rwanda, electric scooters are being explored as part of the government's broader strategy to reduce carbon emissions and improve urban mobility. Studies have shown that using electric scooters for last-mile connectivity can reduce traffic congestion by up to 30%, helping to provide a cleaner mode of transportation.
Technology Advancements in Electric Scooters
Technological innovations in battery efficiency, charging infrastructure, and vehicle performance are transforming the electric scooter market in Africa. Battery life and charging speed have always been barriers to the widespread adoption of electric vehicles, but advancements in lithium-ion battery technology are improving the efficiency and range of electric scooters. For example, new lithium-ion batteries have increased the range of electric scooters to over 100 kilometres on a single charge. In addition, solar-powered charging stations are being developed to reduce the dependency on electricity grids, which is particularly useful in rural areas with inconsistent access to electricity. These innovations are making electric scooters more reliable and convenient for everyday use, driving their adoption in African cities.
Private Sector Investment in Electric Mobility
Private sector investment in the electric scooter market is growing rapidly as companies recognise the potential of green mobility solutions. Many startups and established companies are entering the electric vehicle market, offering new products and services tailored to the needs of African consumers. For example, companies such as GreenScoot and e-mobility startups in South Africa are developing and deploying electric scooters for urban use. Private sector investments are helping to accelerate the roll-out of charging infrastructure, provide maintenance services, and promote awareness about the benefits of electric scooters. It has been reported that private sector investments in electric mobility in Africa have increased by 40% in the past three years, contributing to market growth.
Consumer Awareness and Behavioural Shifts
A significant trend in the electric scooter market is the increasing consumer awareness of the environmental and economic benefits of electric vehicles. More people in African cities are becoming conscious of the environmental impact of traditional transportation options, leading to a growing demand for electric scooters as an eco-friendly alternative. For example, awareness campaigns in major cities like Lagos and Nairobi have resulted in a 25% increase in electric scooter sales. As electric scooters become more affordable and widely available, they are seen as a viable alternative to traditional motorcycles and cars, contributing to the changing attitudes towards sustainable transportation.
Market Challenge Analysis:
Infrastructure Challenges
One of the major challenges hindering the widespread adoption of electric scooters in Africa is the lack of adequate charging infrastructure. Despite the growing demand for electric vehicles, including scooters, many regions still lack sufficient charging stations, especially in rural or less-developed areas. This limited infrastructure not only affects the accessibility of electric scooters but also impedes long-distance travel, as users are concerned about the availability of charging points. Additionally, electricity grids in certain African regions are inconsistent, which further exacerbates the issue. For instance, in some parts of sub-Saharan Africa, power outages are frequent, making it difficult to rely on electric scooters for daily commuting. To address this challenge, both public and private sector investments in charging infrastructure need to increase to ensure the availability of reliable, easily accessible charging stations across urban and rural areas.
High Initial Costs
The high upfront costs associated with electric scooters can be a barrier to their adoption, particularly in low-income regions. While electric scooters offer long-term savings in terms of fuel and maintenance costs, their initial price is often higher than traditional internal combustion engine (ICE) vehicles. This price disparity makes it difficult for many African consumers to make the switch to electric scooters, especially when affordable alternatives are available. In addition, the limited availability of financing options for electric vehicles in some countries further exacerbates this challenge. For instance, in many African countries, banks and financial institutions are hesitant to provide loans for electric vehicles due to their relatively high cost and the limited market for electric vehicles. As a result, many consumers continue to rely on older, cheaper, and more readily available gasoline-powered motorcycles and scooters, limiting the growth potential of the electric scooter market in the region.
Market Opportunities
The electric scooter market in Africa presents significant growth opportunities, particularly as urbanisation continues to accelerate across the continent. As cities grow, so does the demand for efficient, affordable, and eco-friendly transportation solutions. Electric scooters are poised to play a key role in addressing the need for last-mile connectivity, offering an ideal solution for short-distance travel. Moreover, the growing awareness of environmental concerns and the desire to reduce carbon emissions present an opportunity for electric scooters to replace traditional gasoline-powered motorcycles and scooters. Governments and local municipalities are increasingly focusing on reducing urban pollution and promoting cleaner modes of transport, creating a conducive environment for electric mobility adoption.
Furthermore, technological advancements in battery efficiency and charging infrastructure are opening up new opportunities for market expansion. The development of faster-charging stations and more durable, longer-range batteries is making electric scooters more practical for daily use. In addition, the rising interest from the private sector, including investment in electric vehicle startups, infrastructure projects, and charging solutions, is driving innovation and market growth. With the right regulatory support and financial incentives, the electric scooter market in Africa could see rapid expansion, as more consumers, businesses, and government entities look for sustainable alternatives to traditional transportation. This creates a promising opportunity for manufacturers, infrastructure developers, and service providers in the electric mobility sector to capitalise on the continent’s evolving transportation needs.
Market Segmentation Analysis:
By Product The product segment in the electric scooter market includes both personal and commercial electric scooters. Personal electric scooters are designed for individual use, providing an eco-friendly and cost-effective solution for commuting, particularly in urban areas with high traffic congestion. These scooters are ideal for short-distance travel and last-mile connectivity. On the other hand, commercial electric scooters are designed for delivery services, shared mobility platforms like ride-hailing, and businesses requiring fleet operations. The commercial segment is expanding rapidly as cities look for sustainable solutions to address delivery challenges and reduce traffic congestion. Both product categories are growing due to increasing demand for affordable, green mobility options.
By Battery The battery segment plays a critical role in the performance and adoption of electric scooters. Lithium-ion (Li-ion) batteries are the dominant technology in the market, known for their efficiency, longevity, and lightweight characteristics. These batteries offer longer ranges, faster charging times, and better overall performance compared to other battery types. Manufacturers are also focusing on the development of new battery technologies, such as solid-state batteries, to enhance scooter performance and reduce costs. As demand for electric scooters increases, advancements in battery technology will continue to improve the overall user experience and lower the total cost of ownership.
By Voltage The voltage segment in the electric scooter market is divided into low voltage (36V, 48V) and high voltage (60V, 72V) categories. Low-voltage electric scooters are more commonly used for personal transportation, offering a more affordable option for short-distance commutes. These scooters are ideal for urban commuters who need an efficient and environmentally friendly mode of transportation. High-voltage electric scooters, on the other hand, are designed for higher speeds, longer ranges, and more robust performance. These scooters are typically used for commercial applications or longer trips. The demand for both voltage categories is growing as users look for scooters that meet their specific mobility needs.
Segmentation:
Based on the product
- Retro Electric Scooter
- Standing/Self-Balancing Electric Scooters
- Folding Electric Scooters
Based on Battery
- Sealed Lead Acid
- NiMH
- Li-Ion
Based on Voltage
- 24V
- 36V
- 48V
- Greater than 48V
Based on Country
- South Africa
- Morocco
- Algeria
- Egypt
Regional Analysis:
North America
North America is one of the leading regions in the electric scooter market, contributing significantly to the global market share. The increasing adoption of eco-friendly transportation solutions, government initiatives supporting green mobility, and the growing popularity of shared mobility services are key factors driving the market. North America’s market share is estimated at 25% of the global electric scooter market. The United States, in particular, is witnessing rapid growth due to the rise in urbanisation and the need for sustainable last-mile transportation options. For instance, the U.S. government has implemented various subsidies and grants to encourage the adoption of electric vehicles, including electric scooters. Furthermore, cities like Los Angeles and San Francisco have implemented scooter-sharing programs, contributing to the region's dominance in the market.
Europe
Europe holds a substantial portion of the global electric scooter market, with an estimated market share of 30%. The region is a leader in sustainable mobility solutions, driven by stringent environmental regulations, strong government incentives, and increasing consumer awareness of the environmental impact of traditional vehicles. European countries such as Germany, France, and the UK are at the forefront of electric scooter adoption, with cities offering incentives for electric vehicle use and improved infrastructure to support their growth. For instance, Paris has introduced policies to encourage shared electric scooters as part of its initiative to reduce carbon emissions, fostering the growth of the electric scooter market in the region. Additionally, the development of efficient charging infrastructure and battery swap stations across major European cities is supporting further market expansion.
Asia Pacific
Asia Pacific is the fastest-growing region in the electric scooter market, with a market share of around 40%. Countries such as China, India, and Japan are key players driving the rapid adoption of electric scooters. China, in particular, has emerged as a global leader in electric vehicle production and adoption, with the government offering incentives to promote electric scooters and the necessary infrastructure. India is also seeing a rise in electric scooter demand, especially in urban areas where traffic congestion and pollution are growing concerns. For instance, in 2023, India’s electric two-wheeler market grew by over 120%, fuelled by government policies and incentives. The region’s increasing focus on sustainable transportation solutions, coupled with the rapid expansion of battery technology and charging networks, is positioning the Asia Pacific region as a dominant force in the electric scooter market.
Key Player Analysis:
- Honda Motor Co. Ltd.
- KTM AG
- Mahindra GenZe
- Peugeot Scooters
- Ninebot Limited
- Suzuki Motor Corporation
- Terra Motors Corporation
- Vmoto Limited
- Yadea Technology Group Co., Ltd.
- Yamaha Motor Company Limited
Competitive Analysis:
The African electric scooter market is becoming increasingly competitive as both global and regional players expand their presence. Leading companies like Honda, Yamaha, and Suzuki are actively investing in electric mobility, while local startups such as Spiro and GreenScoot are gaining traction with tailored solutions for the African market. Established brands benefit from their global reach and established infrastructure, yet startups are capitalising on the growing demand for eco-friendly, affordable transportation. Companies like TAILG Group are forming strategic partnerships, such as with Kofa in Ghana, to enhance their market share by leveraging local expertise and infrastructure. Furthermore, the expansion of electric vehicle leasing models and the introduction of battery swapping technologies are opening up new opportunities for growth. The sector remains highly dynamic, with a clear shift towards sustainability and innovation, creating a competitive landscape that fosters rapid advancements in technology and infrastructure across the continent.
Recent Developments:
- In November 2023, Uber South Africa introduced a new service, Uber Package, which will use electric scooters for deliveries. The initial deployment of these electric vehicles will begin in Cape Town in December 2023, with a rollout to Johannesburg scheduled for February 2024. This initiative aims to improve urban mobility and sustainability within the company’s service offerings.
- In August 2023, Spiro, an African startup, revealed plans to expand its electric scooter and motorcycle leasing services to Kenya and Uganda. The Kenyan government has expressed support for Spiro’s initiative, which seeks to deploy 1.2 million electric vehicles across the country. This expansion highlights a growing commitment to sustainable transportation solutions in the region.
- In October 2023, TAILG Group, a Chinese e-mobility company, announced a partnership with Kofa, a Ghanaian firm specialising in battery swap networks, to develop a new electric motorcycle named Jidi. The collaboration aims to deploy 200,000 vehicles using Kofa's battery swap infrastructure by 2030. Additionally, TAILG plans to integrate Kofa batteries into both new and existing models, further promoting the adoption of electric vehicles throughout Africa. This initiative marks a significant advancement in sustainable transportation solutions in the region.
Market Concentration & Characteristics:
The African electric scooter market is characterised by a moderate level of concentration, with a mix of global and local players competing for market share. Large international companies like Honda, Yamaha, and Suzuki dominate with established brand recognition and extensive resources, allowing them to lead in product innovation and infrastructure development. However, local startups such as Spiro and GreenScoot are making significant inroads by offering tailored solutions that cater specifically to the unique needs of African consumers, including affordability and sustainability. The market is marked by growing investment in electric vehicle infrastructure, particularly in charging and battery-swapping technologies, which is crucial for widespread adoption. As more players enter the market, competition is intensifying, but there is also collaboration, as evidenced by partnerships like TAILG Group’s alliance with Kofa. Overall, the market is evolving rapidly, driven by innovation, regional demand for sustainable mobility, and government support for green transportation solutions.
Report Coverage:
The research report offers an in-depth analysis based on product type, battery, voltage, and region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, a SWOT analysis, and current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The adoption of electric scooters in Africa will continue to grow as urbanisation and the demand for efficient transportation solutions increase.
- Government policies promoting green mobility and sustainability will support the expansion of electric scooters across major cities.
- Technological advancements in battery efficiency and charging infrastructure will make electric scooters more accessible and convenient for consumers.
- The demand for last-mile connectivity solutions will drive the adoption of electric scooters in densely populated urban areas.
- Private sector investments in electric mobility infrastructure, such as charging stations and battery swap networks, will accelerate market growth.
- Increased awareness of environmental issues and the benefits of electric vehicles will drive consumer demand for eco-friendly transportation options.
- Local electric scooter manufacturers will play a crucial role in catering to the specific needs of the African market, offering affordable and reliable options.
- Strategic partnerships between local and international companies will enhance the development and deployment of electric scooters across Africa.
- The rise of ride-hailing and leasing services will promote the use of electric scooters for shared mobility solutions.
- As the electric scooter market matures, regulatory frameworks and standards will evolve to ensure safety, performance, and quality across the sector
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Africa Electric Scooter Market?
What are the key segments within the Africa Electric Scooter Market?
What are some challenges faced by the Africa Electric Scooter Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Africa Electric Scooter Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Selected Region & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Africa Electric Scooter Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 106.5 million → 2032: USD 330.35 million)
- 2.1.2 Volume & Revenue – Regional Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Africa Electric Scooter Segmentation Snapshot
- 2.2.1 Market Split by Country – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Africa Electric Scooter Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Africa Electric Scooter Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Country
- 3.2 Africa Electric Scooter Drivers
- 3.3 Africa Electric Scooter Restraints & Challenges
- 3.4 Africa Electric Scooter Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Africa Electric Scooter Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Africa Electric Scooter Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regional & Country Regulatory Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Africa Electric Scooter category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Africa Electric Scooter Attractiveness Analysis
- 4.1.1 By Country – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Country – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Country – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Country Opportunity Scorecards
- 4.5.1 Priority Country 1
- 4.5.2 Priority Country 2
- 4.5.3 Priority Country 3
- 4.5.4 Priority Country 4
Note: Priority countries are selected from within the region covered by the study. Numbered entries are indicative and are populated with relevant country names based on market size, growth potential, and strategic relevance.
Chapter 5. Africa Electric Scooter Cross-Border Trade & Market Access Analysis
- 5.1 Intra-Regional & Extra-Regional Trade Overview
- 5.1.1 Regional Export Value by Country (2024)
- 5.1.2 Regional Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Regional Import Value by Country (2024)
- 5.1.4 Regional Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: Cross-border analysis applies where relevant to Africa Electric Scooter. Country trade flows distinguish intra-regional activity from trade with markets outside the region. Regional external trade totals exclude intra-regional flows to avoid double counting. Classifications and transaction measures follow the market scope; volume and route analyses apply only where meaningful.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Africa Electric Scooter Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Africa Electric Scooter Share Analysis – 2024
- 6.2.1 Regional Revenue Share by Company
- 6.2.2 Regional Volume Share by Company (Volume Where Applicable)
- 6.2.3 Company Revenue Share by Country
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Regional Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Africa Electric Scooter Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Revenue Exposure by Country Within the Region
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Africa Electric Scooter (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Africa Electric Scooter
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Africa Electric Scooter – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Country Market Analysis – Regional Overview
- 8.1 Country Market Overview Within the Region
- 8.1.1 Country Volume Share Within the Region (Where Applicable)
- 8.1.2 Country Revenue Share Within the Region
- 8.1.3 Market Volume by Country (Where Applicable)
- 8.1.4 Market Revenue by Country
- 8.1.5 Country Forecasts Through 2032
- 8.2 Cross-Country Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. Africa Electric Scooter – Priority Country 1
Chapter 10. Africa Electric Scooter – Priority Country 2
Chapter 11. Africa Electric Scooter – Priority Country 3
Chapter 12. Africa Electric Scooter – Priority Country 4
Chapter 13. Africa Electric Scooter Company Profiles
- 13.1 [Company 01]
- 13.1.1 Company Overview
- 13.1.2 Key Management Personnel
- 13.1.3 Products & Services Portfolio
- 13.1.4 Financial Performance
- 13.1.5 Regional Market Focus & Country Presence
- 13.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 14. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 15. Research Methodology
- 15.1 Research Framework & Philosophy
- 15.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 15.3 Data Modeling – Country-Level Estimates & Regional Aggregation
- 15.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 15.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 15.6 Quality Control – Four-Layer Validation Framework
- 15.7 Limitations & Standard Assumptions
- 15.8 Disclaimer
