
Agricultural Biologicals Testing Market Overview:
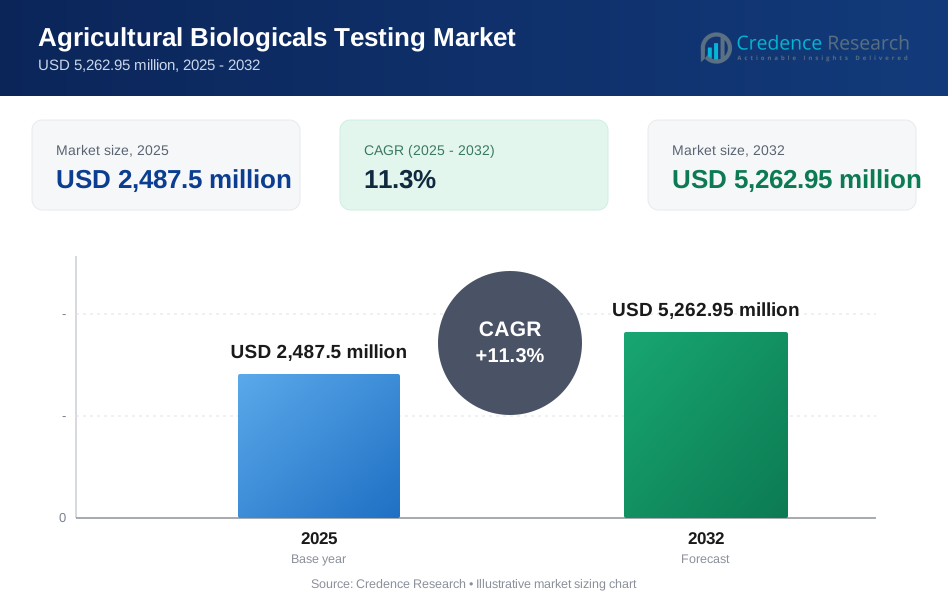
The Agricultural Biologicals Testing Market is projected to grow from USD 2,487.5 million in 2025 to an estimated USD 5,262.95 million by 2032, with a compound annual growth rate (CAGR) of 11.3% from 2025 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Agricultural Biologicals Testing Market Size 2025 | USD 2,487.5 million |
| Agricultural Biologicals Testing Market, CAGR | 11.3% |
| Agricultural Biologicals Testing Market Size 2032 | USD 5,262.95 million |
Agricultural Biologicals Testing Market Insights:
- Rising demand for validated biopesticides, biofertilizers, and biostimulants drives steady adoption of advanced analytical and field testing methods.
- Limited harmonization of global regulatory standards and performance variability across agro-climatic zones continue to restrain smooth expansion.
- North America leads the market with strong regulatory systems, while Europe maintains high testing intensity driven by ecological and compliance priorities.
- Asia-Pacific emerges as the fastest-growing region due to expanding agricultural activity, increasing awareness of natural inputs, and supportive government programs.

Agricultural Biologicals Testing Market Drivers
Growing Regulatory Emphasis On Biological Input Validation
The Agricultural Biologicals Testing Market gains strong momentum as regulators tighten rules for biopesticides, biofertilizers, and biostimulants. It supports manufacturers that need validated safety and performance data to secure approvals. Strong compliance pressure encourages firms to invest in structured field and laboratory studies. Rising global demand for residue-free produce enhances the push for dependable biological inputs. Farmers adopt these products when clear, independently verified results guide decision-making. Testing programs confirm microbial viability, environmental behavior, and crop response. Contract research organizations expand capacity to meet higher submission volumes. The push for reliable scientific evidence strengthens industry investment cycles.
- For instance, Eurofins Agroscience Services recently expanded its specialized laboratory capacity to support the EU’s strict "Farm to Fork" targets, having successfully processed over 15,000 regulatory data points for microbial stability and non-target organism safety in a single reporting cycle.
Rising Demand For Efficacy Data Across Diverse Agro-Climatic Zones
The Agricultural Biologicals Testing Market benefits from the need to generate accurate efficacy results across varied climates. It helps companies refine product claims before commercial launch. Diverse soil and weather patterns require multi-location trials to demonstrate consistent performance. Biological inputs respond differently under changing stress levels, so extensive testing supports credibility. Farmers prefer solutions that show stable field strength across key crops. Governments encourage these trials to reduce dependence on synthetic inputs. CROs increase trial sites to meet this demand. The market moves toward standardized protocols that support international registration.
- For instance, SGS SA utilized its network of 450+ research stations to conduct a multi-year validation study for a new bio-fungicide, demonstrating a consistent 12% to 15% reduction in disease incidence across 20 distinct agro-climatic zones ranging from semi-arid to tropical environments.
Expanding Adoption Of Sustainable Farming Practices Worldwide
Strong interest in low-residue agriculture drives higher testing activity within the Agricultural Biologicals Testing Market. It enables producers to offer alternatives that support environmental goals. Global retailers promote greener supply chains, which increases demand for certified biological inputs. Manufacturers rely on robust data packages to strengthen sustainability claims. Testing frameworks confirm soil health benefits and non-target safety. Farmers evaluate long-term value through verified improvements in yield stability. Research teams focus on microbial interactions to support advanced product development. Wider adoption of eco-friendly inputs encourages steady market expansion.
Increasing Commercialization Of Next-Generation Microbial And Biochemical Products
The Agricultural Biologicals Testing Market grows with rapid innovation in microbial consortia, peptides, and fermentation-based inputs. It helps developers validate complex mode-of-action pathways before regulatory submission. New biological formats require deeper characterization of stability and compatibility. Companies rely on advanced testing tools to strengthen data packages for global markets. Field trials on high-value crops support early adoption. Demand rises from firms that seek to differentiate through verified performance. Testing labs invest in genomic and metabolomic tools to handle advanced biologicals. More product pipelines entering commercialization lift testing needs worldwide.
Agricultural Biologicals Testing Market Trends
Integration Of Advanced Analytical Technologies Into Testing Protocols
Strong digital adoption shapes modern workflows in the Agricultural Biologicals Testing Market. It supports the use of genomics, metabolomics, and high-resolution imaging for product characterization. Automated systems track microbial viability and product decay rates. AI-driven platforms enhance pattern recognition in complex biological interactions. Labs rely on smart sensors to monitor field conditions and improve data quality. Precision tools strengthen confidence in trial outcomes. Companies use advanced analytics to shorten development cycles. These tools help improve accuracy without raising operational load.
Growth Of Third-Party Contract Research Capacity Across Key Regions
Demand for outsourced studies rises as companies turn to CROs for faster execution within the Agricultural Biologicals Testing Market. It helps streamline multi-trial programs across continents. CROs expand greenhouse, controlled-environment, and open-field facilities. Service providers invest in upgraded equipment to meet global study requirements. Firms request faster turnaround while maintaining regulatory-grade data. New partnerships emerge to strengthen regional presence. Multi-country project coordination becomes a core service offering. Broader outsourcing adoption increases competition among service providers.
Shift Toward Validation Frameworks Supporting Regenerative Agriculture
Regenerative farming pushes new testing priorities across the Agricultural Biologicals Testing Market. It builds demand for studies focused on soil carbon, microbial diversity, and root health. Buyers expect biological inputs to support long-term soil recovery. Labs evaluate nutrient cycling and organic matter improvements with stricter parameters. Testing programs analyze stress tolerance effects on crops. Data packages highlight ecological gains alongside yield effects. Developers position biologicals as core tools for regenerative models. The trend supports broader testing on system-level outcomes.
- For instance, Biome Makers utilized its BeCrop® technology to analyze over 10 million taxonomic data points across global soil samples, providing manufacturers with a standardized metric to prove that specific biological applications increased microbial functional diversity by 26% within a single growing season.
Expansion Of Post-Market Performance Monitoring Programs
The Agricultural Biologicals Testing Market expands its focus beyond pre-approval studies to lifecycle evaluation. It enables producers to track real-world results after market entry. Governments request updated performance evidence for renewal cycles. Companies monitor field complaints to refine formulations. Large growers share structured field data with testing partners. Digital farm platforms supply continuous usage insights. Post-market testing strengthens product consistency across planting seasons. The trend supports better product stewardship frameworks.
- For instance, Staphyt SA implemented a post-market monitoring program using a network of 200 "Real-Life" trial sites, which documented a 94% consistency rate in the nitrogen-fixation performance of commercialized biofertilizers across 5 distinct soil pH gradients over 3 consecutive years.
Agricultural Biologicals Testing Market Challenges Analysis
Variability In Biological Performance Under Real-World Conditions
The Agricultural Biologicals Testing Market faces difficulty when performance fluctuates across environments. It manages inputs influenced by temperature, soil type, moisture, and microbial competition. Developers struggle to predict outcomes across diverse production systems. CROs need larger site networks to capture these variables. Farmers hesitate when trial results lack uniformity. Regulatory agencies request expanded datasets to confirm stability. Testing cycles become longer due to the need for seasonal repetition. The challenge increases cost pressure on early-stage companies.
Lack Of Globally Harmonized Standards And Validation Protocols
The Agricultural Biologicals Testing Market operates within fragmented regulatory landscapes. It handles inconsistent testing rules across countries. Companies prepare separate data packages for each region. Labs adjust protocols to match local guidelines, which raises complexity. Approval delays occur when definitions of biological categories differ. Emerging markets lack established frameworks, adding uncertainty. Developers rely on expert consultation to manage varied compliance paths. The absence of global harmonization slows product deployment across borders.
Agricultural Biologicals Testing Market Opportunities
Rising Investments In Next-Generation Testing Infrastructure And Digital Tools
The Agricultural Biologicals Testing Market gains opportunity from stronger investment flows. It benefits from labs adopting automation, AI analytics, and climate-controlled test systems. Producers seek integrated platforms that combine lab and field trial insights. Digital tools help accelerate study design and reduce protocol deviations. Governments fund innovation programs that support biological evaluation. Private firms invest in dedicated microbial research centers. Testing accuracy improves as advanced diagnostics become widely accessible. The shift strengthens the competitive position of specialized CROs.
Greater Adoption Of Biological Inputs In High-Value And Export-Oriented Agriculture
The Agricultural Biologicals Testing Market expands into segments that demand verified performance for premium crops. It supports growers that need compliant products for export markets with strict residue rules. High-value horticulture encourages product differentiation through biological solutions. Testing validates benefits tied to quality, shelf life, and plant stress tolerance. Developers enter partnerships with grower groups to run targeted trials. More companies pursue global registrations, which lifts testing volumes. Emerging regions invest in biological inputs to secure higher farm profitability. Strong interest in residue-free production positions testing providers for sustained growth.
Agricultural Biologicals Testing Market Segmentation Analysis:
By Product Type
The Agricultural Biologicals Testing Market evaluates biopesticides, biofertilizers, biostimulants, and other biological inputs to confirm reliability and performance. Biopesticides require extensive testing to verify microbial purity, strain strength, and field efficacy against target pests. Biofertilizers undergo validation for nutrient-release patterns and soil interaction behavior. Biostimulants need proof of plant growth impact and stress tolerance benefits under controlled and field conditions. Other biological inputs follow similar testing frameworks to secure regulatory clearance. The market benefits from rising demand for low-residue products across key crop systems. It supports manufacturers that seek stronger data packages for competitive positioning. Validation across this segment strengthens user confidence and improves adoption.
- For instance, Koppert Biological Systems utilized rigorous testing protocols to certify that their Trichoderma harzianum T-22 strain maintains a spore concentration of at least \(1\times 10^{9}\) CFU per gram throughout its 12-month shelf life, ensuring consistent bio-fungicidal performance.
By Testing Method
The Agricultural Biologicals Testing Market applies laboratory testing, field testing, in-situ testing, and remote sensing to build robust performance datasets. Laboratory testing helps analyze microbial viability, formulation stability, and biochemical pathways under controlled conditions. Field testing validates real-world crop response across diverse agro-climatic zones. In-situ testing captures soil and root interactions without disturbing natural environments, which improves accuracy. Remote sensing supports widespread monitoring of plant health and treatment effects through drone and satellite tools. Each method contributes unique insights that strengthen product evaluation. Companies prefer multi-method strategies to improve dataset depth. The segment enhances regulatory readiness through structured evidence generation.
By Technology
The Agricultural Biologicals Testing Market uses molecular techniques, biochemical techniques, genetic engineering tools, and bioinformatics to study biological inputs in detail. Molecular methods support strain identification and contamination detection through PCR and sequencing. Biochemical techniques help assess enzyme profiles, metabolite production, and nutrient-related activity. Genetic engineering tools validate traits in enhanced or modified strains. Bioinformatics manages large datasets to predict field behavior and optimize formulation pathways. These technologies improve understanding of mode-of-action patterns. They help shorten development cycles and strengthen scientific credibility. Broader technological integration improves test precision across all product categories.
- For instance, Corteva Agriscience uses high-throughput CRISPR-based screening and bioinformatics to validate nitrogen-fixation genes in Methylobacterium symbioticum, confirming through molecular markers that the bacteria colonizes 90% of plant phyllosphere tissues within 48 hours of application.
By Application
The Agricultural Biologicals Testing Market serves analytical, field support, regulatory, and other application needs through structured programs. Analytical testing confirms composition, potency, and microbial characteristics in early development. Field support services evaluate crop performance, environmental impact, and soil response. Regulatory testing prepares the data required for approvals across major markets. Other applications include shelf-life evaluation and compatibility assessments. The segment supports manufacturers through end-to-end testing workflows. It aligns with rising global standards for biological inputs. Strong demand across applications expands service provider capacity worldwide.
By End-User
The Agricultural Biologicals Testing Market supports biological product manufacturers, government agencies, and other stakeholders. Manufacturers rely on advanced testing to validate product claims and prepare regulatory dossiers. Government agencies use independent testing to enforce safety, environmental, and efficacy standards. Other end-users include research institutions and grower groups seeking verified data. Each user group drives demand for consistent, science-based evaluation frameworks. Testing partners provide tailored solutions to match approval timelines and crop-specific needs. Strong participation from multiple end-users strengthens market stability. Industry collaboration improves data quality across global biological portfolios.
Segmentation:
By Product Type
- Biopesticides
- Biofertilizers
- Biostimulants
- Others
By Testing Method
- Laboratory Testing
- Field Testing
- In-Situ Testing
- Remote Sensing
By Technology
- Molecular Techniques
- Biochemical Techniques
- Genetic Engineering
- Bioinformatics
By Application
- Analytical
- Field Support
- Regulatory
- Others
By End-User
- Biological Product Manufacturers
- Government Agencies
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America holds the largest share of the Agricultural Biologicals Testing Market. It benefits from strict regulatory frameworks, strong adoption of biological inputs, and a dense network of contract research organizations. The region leads in laboratory infrastructure and advanced analytical capabilities. Government-backed sustainability programs strengthen demand for validated biological solutions. It attracts manufacturers seeking faster and more predictable approval cycles. The Agricultural Biologicals Testing Market gains consistent growth from rising investment in biological innovation across the United States and Canada.
Europe represents the second-largest share due to its mature regulatory environment and strong commitment to eco-friendly agriculture. It enforces detailed performance and safety requirements that drive high testing volume. The region supports strong research partnerships between universities, laboratories, and biological producers. Companies focus on soil health and biodiversity testing, which increases demand for specialized protocols. It maintains high testing intensity across biopesticides, biofertilizers, and biostimulants. Regional sustainability policies encourage broader use of validated biological inputs.
Asia-Pacific holds a fast-growing share led by expanding agricultural production and rising awareness of natural crop solutions. It gains demand from large-scale farming systems that seek residue-free alternatives. Testing providers increase field trial capacity to support diverse climates, soil types, and pest pressures. Governments invest in biological research centers to strengthen domestic innovation. The region moves toward stricter compliance rules that require structured data packages. Strong interest in microbial technologies positions the Agricultural Biologicals Testing Market for long-term expansion across emerging economies.
Key Player Analysis:
- Eurofins Scientific SE
- SGS SA
- Intertek Group plc
- Bureau Veritas SA
- ALS Limited
- Syntech Research
- Staphyt S.A.
- Anadiag Group
- i2L Research
- RJ Hill Laboratories Ltd.
- LAUS GmbH
- Bionema Ltd.
Competitive Analysis:
The Agricultural Biologicals Testing Market features strong competition among global testing firms, regional laboratories, and specialized research institutions. It encourages providers to expand capabilities in molecular diagnostics, microbial characterization, and multi-location field trials. Leading companies differentiate through advanced analytical tools, shorter turnaround times, and regulatory expertise. They invest in digital platforms that support data integration across laboratory and field environments. The market benefits from collaborations between CROs, manufacturers, and government bodies to create consistent testing standards. Competitive intensity grows as firms add new services linked to soil microbiome studies and environmental impact evaluation. Providers strengthen their positions by building trial networks across major crop-producing regions to support global registration needs. Continuous innovation in testing technologies helps maintain service quality and operational efficiency within the Agricultural Biologicals Testing Market.
Recent Developments:
- In July 2025, Eurofins Agroscience Servicesstrengthened its market position by completing the acquisition of Kalyx, a leader in AgroScience Field GLP and Seed Trials in Australia and New Zealand. This follows their September 2024 acquisition of Verdelab Bioscience, which expanded their European capabilities in specialized vegetable seed testing and plant pathology.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Testing Method, Technology, Application, End-User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Growing demand for verified biological inputs will strengthen global reliance on structured testing programs within the Agricultural Biologicals Testing Market.
- Regulatory bodies will tighten approval rules, which drives higher investment in analytical and field validation frameworks.
- Adoption of AI-enabled tools will improve data accuracy, shorten development cycles, and support complex biological evaluations.
- Expansion of multi-location field networks will help companies generate climate-specific performance datasets.
- Bioinformatics and molecular tools will gain wider use to evaluate microbial interactions and predict real-world behavior.
- Manufacturers will prioritize testing partnerships to secure faster registration in competitive biological product segments.
- Growth in sustainable and residue-free farming will lift testing volumes across key crop systems.
- Emerging markets will expand testing capacity to support rising domestic production of biological inputs.
- Strong collaboration between research institutes and CROs will shape standardized protocols across global regions.
- Continuous innovation in microbial and biochemical products will increase long-term testing requirements.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Regulatory Emphasis on Biological Input Validation
Tightening global regulations for biopesticides, biofertilizers, and biostimulants require manufacturers to provide validated safety and efficacy data, driving demand for structured laboratory and field testing services.
Rising Demand for Efficacy Data Across Diverse Agro-Climatic Zones
Manufacturers and regulators require robust, multi-location trial data to demonstrate consistent product performance across different climates and soil types, increasing the need for comprehensive testing programs.
Expanding Adoption of Sustainable Farming Practices
The shift toward low-residue and eco-friendly agriculture is boosting demand for certified biological inputs, which in turn drives the need for rigorous testing to validate environmental and crop health benefits.
Increasing Commercialization of Next-Generation Microbial and Biochemical Products
Rapid innovation in microbial consortia, peptides, and fermentation-based biologicals necessitates advanced testing to validate new modes of action and ensure regulatory compliance, expanding the market for specialized testing services.
Integration of Advanced Analytical Technologies
The adoption of genomics, metabolomics, and AI-driven analytics in testing protocols enhances data accuracy and efficiency, encouraging more manufacturers to invest in comprehensive biologicals testing.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Agricultural Biologicals Testing Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Agricultural Biologicals Testing Market projected to grow between 2025 and 2032?
Which Agricultural Biologicals Testing Market segment held the largest share in 2025?
What are the primary factors fueling the growth of the Agricultural Biologicals Testing Market?
Who are the leading companies in the Agricultural Biologicals Testing Market?
Which region commanded the largest share of the Agricultural Biologicals Testing Market in 2025?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Biological Product Manufacturers
- 1.2.2 Government Agencies
- 1.2.3 Others
- 1.3 By Technology
- 1.3.1 Molecular Techniques
- 1.3.2 Biochemical Techniques
- 1.3.3 Genetic Engineering
- 1.3.4 Bioinformatics
- 1.4 By Product Type
- 1.4.1 Biopesticides
- 1.4.2 Biofertilizers
- 1.4.3 Biostimulants
- 1.4.4 Others
- 1.5 By Testing Method
- 1.5.1 Laboratory Testing
- 1.5.2 Field Testing
- 1.5.3 In-Situ Testing
- 1.5.4 Remote Sensing
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 2,487.5 million → 2032: USD 5,262.95 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Agricultural Biologicals Testing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Agricultural Biologicals Testing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Agricultural Biologicals Testing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Agricultural Biologicals Testing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Agricultural Biologicals Testing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Agricultural Biologicals Testing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Agricultural Biologicals Testing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Agricultural Biologicals Testing Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 2,487.5 million → 2032: USD 5,262.95 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Agricultural Biologicals Testing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2025-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2025-2032
- 12.3.4 Volume Forecast, 2025-2032
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Biological Product Manufacturers
- 12.3.7.2 Government Agencies
- 12.3.7.3 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2025-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2025-2032
- 12.4.4 Volume Forecast, 2025-2032
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Molecular Techniques
- 12.4.7.2 Biochemical Techniques
- 12.4.7.3 Genetic Engineering
- 12.4.7.4 Bioinformatics
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2025-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2025-2032
- 12.5.4 Volume Forecast, 2025-2032
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Biopesticides
- 12.5.7.2 Biofertilizers
- 12.5.7.3 Biostimulants
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Testing Method - Market Size and Forecast, 2025-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2025-2032
- 12.6.4 Volume Forecast, 2025-2032
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Laboratory Testing
- 12.6.7.2 Field Testing
- 12.6.7.3 In-Situ Testing
- 12.6.7.4 Remote Sensing
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Agricultural Biologicals Testing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Agricultural Biologicals Testing Geographic Market Outlook, 2025-2032
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Agricultural Biologicals Testing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Agricultural Biologicals Testing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Eurofins Scientific SE
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 SGS SA
- 18.4 Intertek Group plc
- 18.5 Bureau Veritas SA
- 18.6 ALS Limited
- 18.7 Staphyt S.A.
- 18.8 Syntech Research
- 18.9 Anadiag Group
- 18.10 RJ Hill Laboratories Ltd.
- 18.11 Bionema Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

