
Artificial Intelligence In IVD Market Overview:
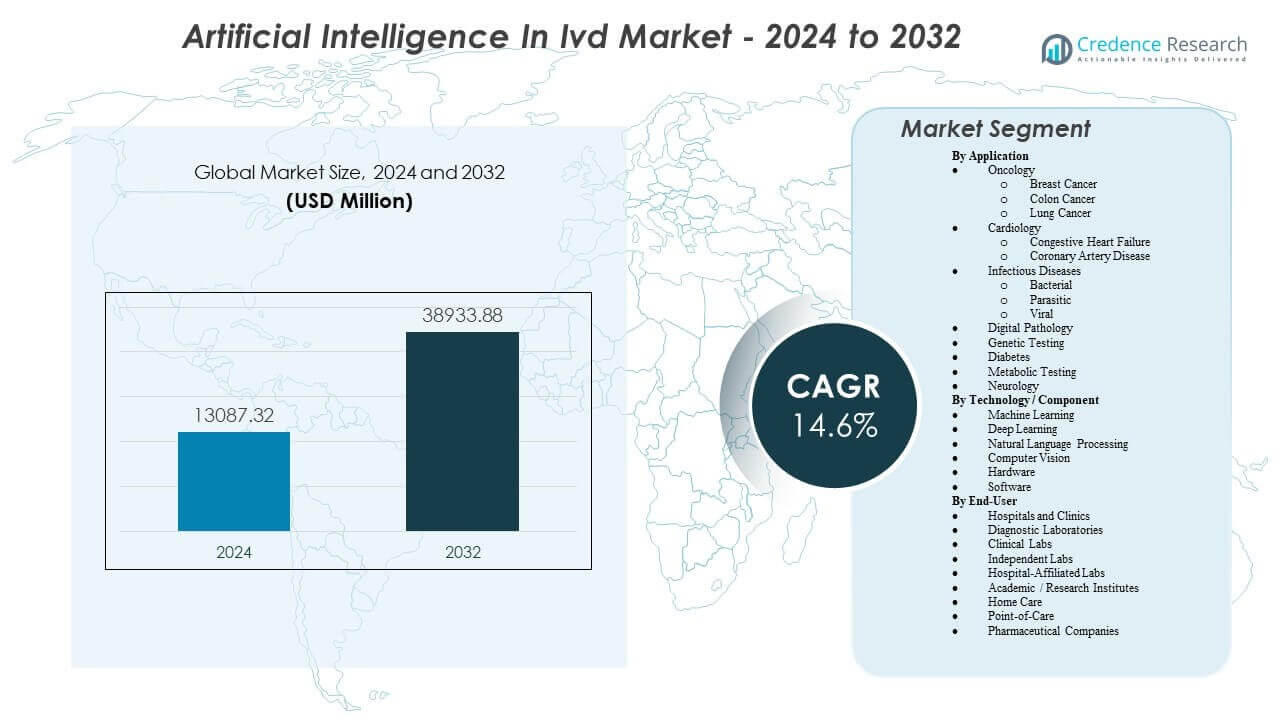
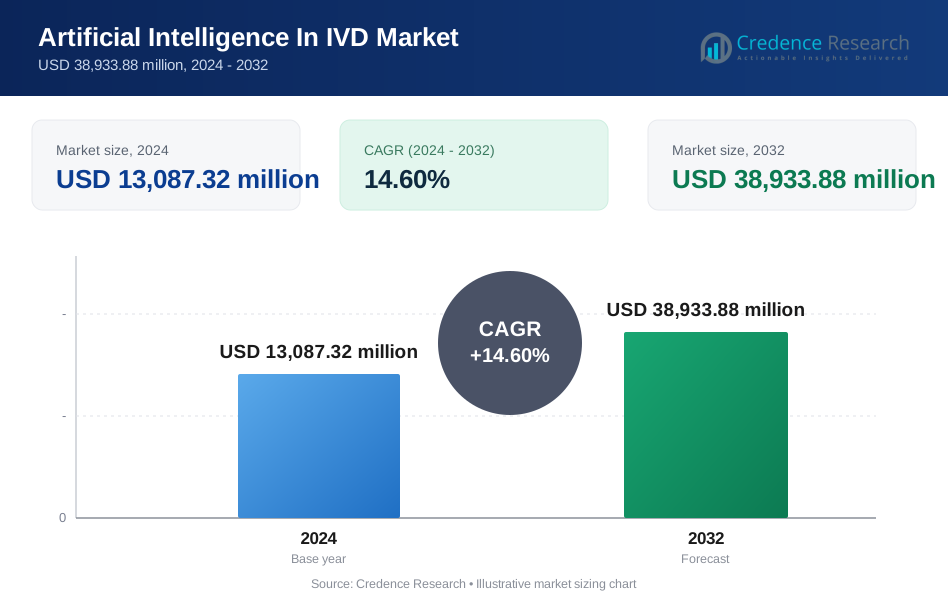
The Artificial Intelligence In Ivd Market is projected to grow from USD 13,087.32 million in 2024 to an estimated USD 38,933.88 million by 2032, with a compound annual growth rate (CAGR) of 14.6% from 2024 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Artificial Intelligence In IVD Market Size 2024 | USD 13,087.32 million |
| Artificial Intelligence In IVD Market, CAGR | 14.6% |
| Artificial Intelligence In IVD Market Size 2032 | USD 38,933.88 million |
Strong market drivers include rising demand for early disease detection, which encourages laboratories to deploy AI tools that identify patterns not easily recognized by traditional methods. Providers seek automation to stabilize operations amid shortages of skilled laboratory professionals. Companies develop adaptive algorithms that support real-time interpretation, enhancing diagnostic performance across oncology, infectious disease testing, and genetic analysis. Adoption grows rapidly as AI improves reporting precision and strengthens coordinated workflows across large and mid-sized laboratories.
North America leads the market due to advanced digital infrastructure, strong clinical research activities, and high adoption of automated diagnostic systems across healthcare networks. Europe follows with widespread integration of digital pathology, molecular platforms, and AI-supported screening programs. Asia Pacific emerges as the fastest-growing region as countries expand diagnostic capacity and invest in digital transformation efforts across hospitals and laboratories. Latin America and the Middle East & Africa show steady progress, supported by modernization initiatives and rising utilization of AI-based diagnostic tools.
Artificial Intelligence In IVD Market Insights:
- The Artificial Intelligence In Ivd Market is projected to grow from USD 13,087.32 million in 2024 to USD 38,933.88 million by 2032, registering a 14.6% CAGR during the forecast period.
- Strong demand for early disease detection and automated diagnostic interpretation drives wider adoption of AI tools across oncology, infectious diseases, genetic testing, and digital pathology.
- Market growth faces restraints such as regulatory complexity, data quality issues, and challenges in validating AI algorithms across diverse populations and laboratory environments.
- North America leads the market due to strong digital infrastructure and high deployment across healthcare systems, while Europe follows with rising integration of AI-enhanced diagnostic workflows.
- Asia Pacific emerges as the fastest-growing region due to expanding laboratory capacity, increasing digital health investments, and rising acceptance of AI-driven diagnostic solutions.
Artificial Intelligence In IVD Market Drivers
Growing Adoption of AI-Enhanced Diagnostic Workflows Across Clinical and Laboratory Settings
Healthcare systems adopt automated diagnostic workflows that raise testing accuracy and speed. Providers rely on machine learning tools that cut manual errors and support clear clinical decisions. Laboratories handle rising test volumes with scalable platforms that improve sample analysis and reporting. It strengthens seamless movement of data across instruments and software systems. The Artificial Intelligence In Ivd Market benefits from hospitals seeking efficient operations. Clinicians value systems that highlight subtle disease markers. Vendors expand integrated diagnostic tools that support specialty and routine testing. Demand rises for solutions that adapt to multiple conditions and care settings.
- For instance, Beckman Coulter’s DxU Iris integrated urinalysis workcell utilizes Digital Flow Morphology technology and AI to automatically classify 12 particle types, reducing manual microscopic reviews by up to 78% in high-volume laboratory settings.
Rising Demand for Early Disease Detection Supported by Predictive Analytics Integration
Predictive analytics tools help detect diseases at earlier stages with clear pattern identification. Providers rely on algorithms that support quick interpretation of complex biological signals. It lifts diagnostic precision across oncology, infectious disease, and metabolic testing. The Artificial Intelligence In Ivd Market gains traction from rising expectations for timely risk assessment. Patients expect faster diagnosis with reduced uncertainty. Hospitals deploy automated systems that highlight critical cases for rapid intervention. Developers improve models that learn from expanding datasets. Adoption grows in public health programs that seek stronger surveillance.
Expansion of Personalized Medicine Driving Algorithm-Based Interpretation of Patient Data
Personalized care models require tools that link test results with patient profiles. Providers adopt algorithms that narrow treatment choices with targeted insights. It improves therapy alignment with molecular and genetic signals. The Artificial Intelligence In Ivd Market advances due to demand for testing that supports precision care. Laboratories use automated tools that classify disease subtypes clearly. Vendors offer platforms that unify multiple data formats for easy interpretation. Growth strengthens where clinicians require rapid matching of test insights with treatment plans. Research institutions rely on AI to guide biomarker analysis.
Increasing Shortage of Skilled Laboratory Workforce Accelerating Automation Deployment
Laboratories face staffing gaps that pressure workflow stability. Automated systems reduce manual steps and improve testing timelines. It supports high throughput without lowering diagnostic accuracy. The Artificial Intelligence In Ivd Market expands because automation fills expertise shortages. Hospitals value tools that require minimal manual oversight. Routine tasks shift toward AI-enabled systems that boost efficiency. Developers design platforms that train staff quickly with intuitive interfaces. Global health systems depend on automation to stabilize diagnostic operations.
- For instance, the Sysmex DI-60 Automated Cell Image Analyzer integrates AI-based morphology to pre-classify white blood cells, enabling laboratories to maintain a processing speed of up to 30 slides per hour while significantly reducing the need for specialized manual hematology expertise.
Artificial Intelligence In IVD Market Trends
Integration of Multimodal Data Platforms Unifying Imaging, Molecular, and Clinical Insights
Multimodal systems combine imaging, molecular results, and patient history within one interface. Providers value unified dashboards that simplify clinical interpretation. It helps teams assess disease progression with stronger clarity. The Artificial Intelligence In Ivd Market moves toward platforms that link diverse diagnostic streams. Vendors develop tools that merge genomic, radiologic, and pathology inputs. Laboratories benefit from reduced fragmentation in data management. Growth rises as health systems demand cohesive analytical frameworks. Adoption strengthens where clinicians require consolidated views of complex cases.
Expansion of Cloud-Based AI Models Supporting Scalable and Remote Diagnostic Capabilities
Cloud platforms support large datasets and flexible deployment models. Laboratories access AI algorithms without heavy hardware investment. It raises reliability of remote diagnostic workflows. The Artificial Intelligence In Ivd Market shifts toward solutions that enable distributed testing networks. Providers gain stronger access to real-time analytics. Vendors update cloud engines rapidly to improve accuracy. Healthcare systems use remote tools to strengthen continuity of care. Scaling becomes easier for institutions with limited local resources.
Emergence of Adaptive Algorithms Improving Diagnostic Precision Through Real-Time Learning Cycles
Adaptive models improve predictions by learning from new clinical datasets. Providers depend on continuous updates that refine classification accuracy. It raises confidence in results across diverse conditions. The Artificial Intelligence In Ivd Market experiences a shift toward self-improving tools. Laboratories value systems that adjust to evolving disease patterns. Vendors integrate real-time training cycles to support greater flexibility. Research centers invest in adaptive platforms to guide experimental diagnostics. Growth increases due to stability in performance across variable populations.
- For instance, Caption Health (now part of GE HealthCare) developed adaptive AI for the Caption AI platform, which provides real-time guidance during ultrasound acquisition; clinical studies showed that medical professionals with no prior ultrasound experience were able to perform diagnostic-quality exams in 98.8% of patients across diverse body types.
Growing Integration of AI with Point-of-Care Testing Devices for Faster Screening Outcomes
Point-of-care systems gain AI tools that raise immediate interpretation precision. Providers value quick screening capabilities that guide care decisions. It strengthens community-level testing programs. The Artificial Intelligence In Ivd Market moves toward decentralized diagnostic support. Vendors design compact tools with automated scoring functions. Patients benefit from shorter wait times and clearer results. Remote clinics use AI-supported devices to manage high testing demand. Adoption rises where infrastructure for central labs remains limited.
- For instance, the Sight OLO analyzer by Sight Diagnostics uses computer vision and AI to perform a Complete Blood Count (CBC) from a finger-prick sample, delivering lab-grade results in 10 minutes by analyzing over 1,000 digital images per sample.
Market Challenges Analysis
Regulatory Complexity Slowing Validation of AI-Driven Diagnostic Models Across Regions
Regulatory bodies evaluate AI models with strict validation processes that slow adoption. Stakeholders navigate varying guidelines for algorithm approval. It places pressure on developers who must meet deep documentation requirements. The Artificial Intelligence In Ivd Market faces delays due to long review cycles. Health systems hesitate when clarity around compliance remains low. Vendors adjust product design to satisfy multiple regulatory expectations. Testing laboratories require assurance regarding model transparency. Growth slows when evidence standards vary widely across countries.
Limitations in Data Quality Affecting Algorithm Reliability Across Diverse Patient Populations
Data sources differ in structure and completeness, which reduces model accuracy. Laboratories struggle with inconsistent sample labeling and formatting. It weakens predictive performance in clinical settings. The Artificial Intelligence In Ivd Market encounters challenges when datasets fail to represent broad populations. Providers hesitate when bias risks appear high. Vendors invest in improving dataset diversity with controlled inputs. Validation teams examine model performance across new cohorts. Health systems require robust evidence before adopting large-scale automation.
Market Opportunities
Rising Investment in AI-Enabled Precision Diagnostics Across Public and Private Healthcare Systems
Governments and private investors increase funding for AI-supported diagnostic infrastructure. Hospitals expand digital capabilities to strengthen disease management programs. It fuels demand for advanced tools that combine biological and clinical signals. The Artificial Intelligence In Ivd Market gains new opportunities through partnerships and research collaborations. Vendors launch scalable platforms for underserved regions. Universities explore algorithm-based innovations that support specialty diagnostics. Startups create targeted models for complex conditions. Funding momentum accelerates commercialization of next-generation solutions.
Expansion Potential in Emerging Markets Through Scalable, Low-Resource AI Diagnostic Platforms
Emerging economies modernize laboratory networks with cost-efficient AI tools. Providers adopt modular systems that operate with limited physical infrastructure. It supports wide deployment across community health centers. The Artificial Intelligence In Ivd Market benefits from rising demand for accessible testing. Vendors produce compact tools suited for decentralized workflows. Government programs strengthen support for AI-guided public health initiatives. Screening programs expand through mobile and portable platforms. Growth increases where diagnostic gaps remain significant.
Market Segmentation Analysis:
By Application
The application segment in the Artificial Intelligence In Ivd Market expands due to broad use across oncology, cardiology, infectious diseases, and metabolic testing. Oncology leads demand because breast, colon, and lung cancer diagnostics require strong pattern recognition and automated insight. Cardiology gains traction with tools that support detection of congestive heart failure and coronary artery disease. Infectious disease testing improves through models that classify bacterial, parasitic, and viral pathogens with clear accuracy. Digital pathology platforms adopt AI to interpret slides with consistent reliability. Genetic testing uses it to process complex markers that guide precision care. Diabetes and metabolic testing depend on automated scoring functions that support screening and continuous disease monitoring. Neurology benefits from tools that highlight subtle biomarkers for early disorder identification.
- For instance, Google Health’s AI model demonstrated a 5.7% reduction in false positives and a 9.4% reduction in false negatives when screening mammograms for breast cancer compared to human radiologists.
By Technology / Component
The technology segment in the Artificial Intelligence In Ivd Market grows due to strong use of machine learning, deep learning, NLP, and computer vision. Machine learning drives routine workflows that require fast predictive scoring. Deep learning models detect intricate patterns that traditional systems miss. NLP supports extraction of insights from structured and unstructured diagnostic text. Computer vision strengthens image-based diagnostics in pathology and radiology-linked testing. Hardware demand rises where high-performance systems process large datasets with stable speed. Software adoption increases as laboratories integrate cloud and on-premise tools that support automated decision pathways. It strengthens overall testing efficiency and consistency across applications.
- For instance, Paige AI received FDA de novo authorization for its "Paige Prostate" deep learning system, which achieved an Area Under the Curve (AUC) of 0.99 in detecting prostate cancer in digital slides.
By End-User
The end-user segment in the Artificial Intelligence In Ivd Market includes hospitals, clinics, diagnostic laboratories, clinical labs, and independent labs. Hospitals deploy AI tools to raise diagnostic throughput and support rapid care decisions. Diagnostic laboratories use automated platforms to manage high sample volumes. Clinical labs apply it to reduce manual interpretation steps and stabilise reporting timelines. Independent labs adopt flexible solutions that fit varied testing menus. Hospital-affiliated labs rely on coordinated workflows that integrate with electronic records. Academic and research institutes explore algorithm models for experimental diagnostics. Home care and point-of-care settings use compact AI systems that guide quick screening. Pharmaceutical companies employ AI-supported diagnostics to strengthen trial monitoring and biomarker evaluation.
Segmentation:
By Application
- Oncology
- Breast Cancer
- Colon Cancer
- Lung Cancer
- Cardiology
- Congestive Heart Failure
- Coronary Artery Disease
- Infectious Diseases
- Bacterial
- Parasitic
- Viral
- Digital Pathology
- Genetic Testing
- Diabetes
- Metabolic Testing
- Neurology
By Technology / Component
- Machine Learning
- Deep Learning
- Natural Language Processing
- Computer Vision
- Hardware
- Software
By End-User
- Hospitals and Clinics
- Diagnostic Laboratories
- Clinical Labs
- Independent Labs
- Hospital-Affiliated Labs
- Academic / Research Institutes
- Home Care
- Point-of-Care
- Pharmaceutical Companies
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America holds 35% of the Artificial Intelligence In Ivd Market, driven by strong adoption of automated diagnostics across the United States and Canada. Hospitals and laboratories expand AI-enabled workflows that strengthen early disease detection and reporting accuracy. It supports high-throughput testing needs linked to oncology, genetic screening, and infectious disease programs. Vendors reinforce their presence through partnerships with major health systems. Research institutions contribute to algorithm development that aligns with precision medicine initiatives. Regulatory clarity encourages evaluation and safe deployment of advanced diagnostic software.
Europe accounts for 30% of market share, supported by strict diagnostic quality standards and strong digital health strategies across leading nations like Germany, United Kingdom, and France. Laboratories integrate AI tools to reduce errors and accelerate interpretation of complex datasets. It strengthens cancer diagnostics, infectious disease surveillance, and digital pathology workflows. Regional investments support cloud-based diagnostic platforms and multimodal imaging tools. Academic centers contribute to model validation using large-scale datasets. Hospitals seek interoperable systems that support consistent reporting across departments.
Asia Pacific captures 25% and remains the fastest-growing region, with strong momentum across China, India, and Japan. Healthcare providers adopt compact AI diagnostic systems to support large population screening programs. It accelerates early detection efforts across oncology, cardiac disorders, and metabolic diseases. Governments invest in digital health infrastructure that supports scalable diagnostic platforms. Latin America holds 5%, led by adoption in Brazil and Mexico. Middle East & Africa hold 5%, with growth centered in GCC nations and South Africa through upgrades in hospital diagnostics.
Key Player Analysis:
- Roche Diagnostics GmbH
- Thermo Fisher Scientific Inc.
- Abbott Laboratories
- Danaher Corporation
- Siemens Healthineers AG
- Illumina Inc.
- Hologic Inc.
- Sysmex Corporation
- QIAGEN N.V.
- PathAI Inc.
- Tempus Labs Inc.
- Proscia Inc.
- Indica Labs Inc.
- Visiopharm A/S
- Ibex Medical Analytics Ltd.
Competitive Analysis:
The competitive landscape of the Artificial Intelligence In Ivd Market features strong activity from global diagnostics leaders and emerging AI-focused companies. Firms such as Roche Diagnostics GmbH, Abbott Laboratories, and Siemens Healthineers AG expand portfolios with integrated molecular, imaging, and digital pathology solutions. It strengthens workflow automation and improves diagnostic precision across high-volume testing environments. AI-driven innovators including PathAI Inc., Tempus Labs Inc., and Ibex Medical Analytics Ltd. accelerate adoption through advanced algorithms and deep learning-driven tools. Companies compete on accuracy, speed, cloud deployment capability, and integration with laboratory information systems. Strategic collaborations help vendors secure access to high-quality datasets and clinical validation partners. Hardware and software manufacturers align to support higher processing capacity for multimodal diagnostics. It drives stronger performance across oncology, infectious disease testing, and digital pathology. Firms pursue regulatory clearances that influence customer confidence and long-term adoption. Growth strategies center on scalable platforms, geographic expansion, and partnerships with hospitals and diagnostic networks.
Recent Developments:
- In November 2025, Roche collaborated with Manifold Bio, paying $55 million for access to its AI-powered drug discovery technology to develop shuttles crossing the blood-brain barrier for brain drugs. This partnership leverages AI to identify biological pathways for targeted therapies in neuroscience.
- In October 2025, Thermo Fisher Scientific announced a strategic collaboration with OpenAI to integrate advanced AI capabilities into its clinical research business and Accelerator Drug Development platform, aiming to accelerate drug development cycles and improve trial efficiency.
- In May 2025, Diagnostics.ai launched PCR.AI, a cutting-edge platform that automates PCR result interpretation with over 99.9% accuracy, streamlining laboratory workflows and enhancing diagnostic precision in IVD applications.
Report Coverage:
The research report offers an in-depth analysis based on Application, Technology / Component, End-User, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- AI-driven diagnostic platforms will strengthen disease detection accuracy and support faster interpretation of complex clinical data across multiple therapeutic areas.
- Integration of multimodal data systems will expand adoption by unifying imaging, molecular, and pathology insights within streamlined diagnostic workflows.
- Cloud-based AI models will gain wider use due to strong demand for scalable solutions that support remote and high-volume laboratory environments.
- Advancements in adaptive algorithms will refine real-time learning cycles and raise confidence in outputs across diverse patient populations.
- Digital pathology growth will accelerate as providers adopt automated slide analysis tools that reduce turnaround times and improve reporting consistency.
- AI-supported genetic and molecular testing will expand due to rising focus on personalized medicine and targeted biomarker interpretation.
- Point-of-care devices with embedded AI features will gain momentum and support decentralized screening efforts across emerging markets.
- Regulatory clarity will improve acceptance of automated systems and encourage broader integration into routine diagnostic pathways.
- Collaboration between diagnostics manufacturers and AI-focused firms will stimulate innovation across software and hardware ecosystems.
- Global health systems will rely on predictive diagnostic models to strengthen early detection programs and manage rising testing workloads.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Adoption of AI-Enhanced Diagnostic Workflows
Healthcare providers and laboratories are increasingly implementing AI-driven diagnostic workflows to improve accuracy, reduce manual errors, and accelerate turnaround times, especially in high-volume testing environments. This trend is driven by the need for scalable solutions that can handle rising test volumes and support clinical decision-making.
Rising Demand for Early Disease Detection Supported by Predictive Analytics
AI-powered predictive analytics enable earlier and more precise disease detection by identifying complex patterns in biological data that traditional methods may miss. This is particularly impactful in oncology, infectious diseases, and metabolic testing, where timely intervention can significantly improve patient outcomes.
Expansion of Personalized Medicine and Algorithm-Based Interpretation
The shift toward personalized medicine is fueling demand for AI tools that can interpret genetic, molecular, and clinical data to guide targeted therapies. Laboratories and clinicians benefit from automated systems that classify disease subtypes and match test results with individualized treatment plans.
Shortage of Skilled Laboratory Workforce Accelerating Automation
A global shortage of skilled laboratory professionals is prompting healthcare systems to adopt AI-enabled automation, which reduces reliance on manual expertise and stabilizes diagnostic operations. Automated platforms help maintain high throughput and consistent quality even with limited staffing.
Integration of Multimodal Data Platforms
The unification of imaging, molecular, and clinical data through AI-powered multimodal platforms is enhancing diagnostic clarity and workflow efficiency. These integrated systems reduce data fragmentation and support comprehensive disease assessment, driving broader adoption across healthcare settings.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Artificial Intelligence In Ivd Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Artificial Intelligence In Ivd Market projected to grow between 2024 and 2032?
Which Artificial Intelligence In Ivd Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Artificial Intelligence In Ivd Market?
Who are the leading companies in the Artificial Intelligence In Ivd Market?
Which region commanded the largest share of the Artificial Intelligence In Ivd Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Hospitals and Clinics
- 1.2.2 Diagnostic Laboratories
- 1.2.3 Clinical Labs
- 1.2.4 Independent Labs
- 1.2.5 Academic / Research Institutes
- 1.2.6 Point-of-Care
- 1.3 By Application
- 1.3.1 Oncology
- 1.3.2 Cardiology
- 1.3.3 Infectious Diseases
- 1.3.4 Digital Pathology
- 1.3.5 Genetic Testing
- 1.3.6 Metabolic Testing
- 1.4 By Technology / Component
- 1.4.1 Machine Learning
- 1.4.2 Deep Learning
- 1.4.3 Natural Language Processing
- 1.4.4 Computer Vision
- 1.4.5 Hardware
- 1.4.6 Software
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 13,087.32 million → 2032: USD 38,933.88 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Artificial Intelligence In IVD Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Artificial Intelligence In IVD Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Artificial Intelligence In IVD Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Artificial Intelligence In IVD Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Artificial Intelligence In IVD Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Artificial Intelligence In IVD Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Artificial Intelligence In IVD Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Artificial Intelligence In IVD Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 13,087.32 million → 2032: USD 38,933.88 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Artificial Intelligence In IVD Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals and Clinics
- 12.3.7.2 Diagnostic Laboratories
- 12.3.7.3 Clinical Labs
- 12.3.7.4 Independent Labs
- 12.3.7.5 Academic / Research Institutes
- 12.3.7.6 Point-of-Care
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Oncology
- 12.4.7.2 Cardiology
- 12.4.7.3 Infectious Diseases
- 12.4.7.4 Digital Pathology
- 12.4.7.5 Genetic Testing
- 12.4.7.6 Metabolic Testing
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology / Component - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Machine Learning
- 12.5.7.2 Deep Learning
- 12.5.7.3 Natural Language Processing
- 12.5.7.4 Computer Vision
- 12.5.7.5 Hardware
- 12.5.7.6 Software
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Artificial Intelligence In IVD End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Artificial Intelligence In IVD Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Artificial Intelligence In IVD Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Artificial Intelligence In IVD Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Roche Diagnostics GmbH
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Thermo Fisher Scientific Inc.
- 18.4 Abbott Laboratories
- 18.5 Danaher Corporation
- 18.6 Siemens Healthineers AG
- 18.7 Illumina Inc.
- 18.8 Hologic Inc.
- 18.9 Sysmex Corporation
- 18.10 QIAGEN N.V.
- 18.11 PathAI Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

