
Market Overview
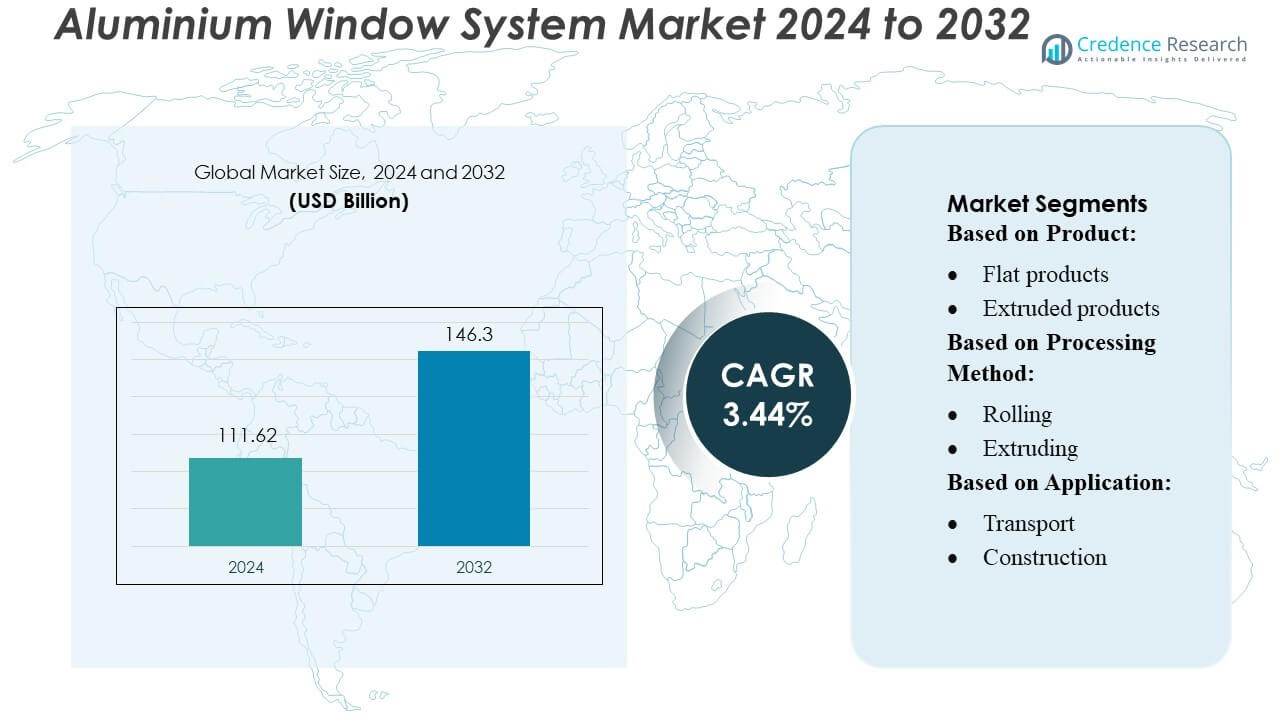
Aluminium Window System Market size was valued USD 111.62 billion in 2024 and is anticipated to reach USD 146.3 billion by 2032, at a CAGR of 3.44% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Aluminium Window System Market Size 2024 | USD 111.62 Billion |
| Aluminium Window System Market, CAGR | 3.44% |
| Aluminium Window System Market Size 2032 | USD 146.3 Billion |
The aluminium window system market is shaped by major players such as Pella Corporation, ANDERSEN CORPORATION, JELD-WEN, Inc., Masonite, Cornerstone Building Brands, Inc., Marvin, PGT INNOVATIONS, SIERRA PACIFIC WINDOWS, Steves & Sons Inc., and Kömmerling, all of which compete intensely on innovation, energy efficiency, and design flexibility. The region leading the market is Asia-Pacific, commanding approximately 39 % of the global market share, driven by rapid urbanization, large-scale infrastructure development, and strong demand for sustainable building materials.
Market Insights
- The Aluminium Window System Market was valued at USD 111.62 billion in 2024 and is projected to reach USD 146.3 billion by 2032 at a CAGR of 3.44%, driven by rising construction and renovation activities.
- Increasing demand for energy-efficient building envelopes and lightweight, durable materials drives market expansion, with thermal-break systems and recycled aluminium gaining strong traction.
- Product innovation and design differentiation define competitive dynamics, as leading players focus on slim-profile frames, automation-ready systems, and enhanced performance standards to strengthen market share.
- High initial installation costs, fluctuating raw material prices, and limited awareness in developing regions act as restraints, slowing adoption across price-sensitive segments.
- Asia-Pacific leads with 39% regional share, supported by rapid urban development and infrastructure growth, while the sliding window segment continues to dominate due to its space-efficient design and widespread use across residential and commercial buildings.
Market Segmentation Analysis:
By Product
Flat products dominate the Aluminium Window System Market with an estimated over 35% share, driven by their widespread use in architectural façades, curtain walls, and fenestration systems requiring high surface uniformity and structural strength. Their superior recyclability and compatibility with anodizing and powder-coating processes strengthen adoption in energy-efficient commercial buildings. Extruded products also show strong growth due to demand for complex profile designs, while forged, long, cast, and other product categories serve niche applications with moderate uptake influenced by precision engineering and cost-effectiveness.
- For instance, Pella Corporation leverages its Shenandoah, Iowa facility-one of approximately 20 total manufacturing sites operated by the company-to support high-volume production of wood windows, including all wooden double-hung windows.
By Processing Method
Extruding represents the leading processing method, accounting for around 40% of market share, as it enables the production of lightweight, custom-shaped aluminium profiles used extensively in modern window frames and structural framing systems. Its ability to optimize strength-to-weight ratio and support thermal-break technologies makes it the preferred choice for high-performance window solutions. Rolling and drawn processes follow, primarily supporting sheet-based applications and precision components, while casting and forging remain smaller segments used in heavy-duty structural parts requiring enhanced durability and dimensional stability.
- For instance, Sierra Pacific Windows uses .075-inch thick extruded aluminium in its Multi-Slide Plus doors, providing both structural strength and long-term durability.
By Application
Construction remains the dominant application segment with more than 45% share, propelled by rapid urbanization, rising investments in smart buildings, and increasing adoption of energy-efficient façades and window solutions. Aluminium’s corrosion resistance, formability, and recyclability underpin its growing preference in residential and commercial developments. Transport and electrical & electronics represent expanding segments due to lightweighting initiatives and thermal conductivity needs, while packaging, machinery, consumer durables, foil stock, and other applications contribute steady demand shaped by industrial modernization and sustainability initiatives.
Key Growth Drivers
1. Rising Demand for Energy-Efficient Building Solutions
The Aluminium Window System Market grows strongly as builders prioritize energy-efficient designs aligned with global green building standards. Aluminium frames support high-performance glazing, thermal-break technology, and superior insulation, helping commercial and residential projects achieve better energy ratings. Government incentives promoting sustainable construction further accelerate adoption. Additionally, aluminium’s recyclability and long service life reduce lifecycle costs, making it increasingly favored over traditional materials. This sustainability-driven shift continues to stimulate product innovation and premium system installations across major urban infrastructure projects.
- For instance, Masonite’s 2022 Environmental, Social & Governance report shows the company reduced its Scope 1 and 2 greenhouse gas emissions by 34% since 2019, demonstrating its commitment to lower-carbon operations.
2. Rapid Urbanization and Expansion of Infrastructure Projects
Accelerating urbanization, particularly in Asia-Pacific and the Middle East, drives significant demand for modern aluminium window systems. Large-scale investments in smart cities, commercial towers, mass housing projects, and transportation hubs create substantial opportunities for high-strength, lightweight, and corrosion-resistant window structures. Builders increasingly prefer aluminium for its design flexibility and compatibility with advanced façade systems. The expansion of mixed-use developments and industrial zones strengthens procurement of standardized and custom architectural profiles, thereby sustaining stable volume growth across global construction value chains.
- For instance, JWC8500 series hybrid window, launched in Canada, features a 26% slimmer frame that increases glass area and achieves a U-factor of 0.82 W/m²·°C, helping surpass Canada’s 2030 energy efficiency targets.
3. Advancements in Extrusion Technologies and Fabrication Precision
Technological upgrades in extrusion processes and fabrication equipment contribute directly to market expansion. Modern extrusion lines enable complex profile geometries, improved surface finishing, and enhanced dimensional accuracy for premium window systems. Integration of automation, robotics, and CNC machining ensures better precision, reduced waste, and faster production cycles. Manufacturers also adopt thermal-break extrusion and multi-chamber frame designs, supporting superior insulation performance. These process improvements elevate the quality and performance of aluminium window systems, expanding their use in high-end architectural and energy-sensitive installations.
Key Trends & Opportunities
1. Growing Adoption of Smart and Automated Window Systems
The market benefits from rising adoption of smart window technologies integrated with sensors, automatic shading, and IoT-enabled climate control solutions. Aluminium frames provide structural strength and design flexibility needed to support motorized components and advanced glazing units. Demand for smart homes and commercial buildings further accelerates this trend. Manufacturers explore embedded photovoltaics, self-tinting glass, and intelligent ventilation systems, creating opportunities for premium aluminium window solutions that enhance energy efficiency, occupant comfort, and building automation capabilities.
- For instance, Richmond, Virginia plant is outfitted with “smart press” machines capable of pressing up to 40 doors at once, while 42-inch interactive screens display real-time product images at each workstation to optimize alignment and quality control.
2. Increasing Use of Recycled Aluminium in Window Profiles
Sustainability initiatives encourage the use of recycled aluminium, which requires significantly less energy to produce and aligns with circular economy goals. Manufacturers actively shift toward low-carbon aluminium billets, creating a growing market for eco-friendly window systems. This trend opens opportunities for companies investing in closed-loop recycling, green certifications, and carbon-reduced product lines. As developers prioritize materials with lower environmental footprints, recycled aluminium window systems gain preference in green buildings, public infrastructure, and environmentally regulated construction sectors.
- For instance, Andersen holds SCS Global Services’ Recycled Content certification for its 100 Series windows, Renewal by Andersen® lines, and A-Series windows, confirming verified recycled content in these profiles.
3. Rising Preference for Slimline and Aesthetic Architectural Designs
A notable trend involves the growing preference for slimline frames that offer larger glass areas, improved natural lighting, and modern architectural aesthetics. Aluminium's inherent strength allows manufacturers to design minimalistic yet durable profiles that support expansive façades and panoramic window installations. This creates opportunities in luxury real estate, commercial towers, and premium residential developments. Demand for custom colors, textured finishes, and seamless corner joining techniques also fuels innovation, allowing suppliers to deliver visually appealing, high-performance window systems.
Key Challenges
1. Fluctuating Aluminium Prices and Supply Chain Volatility
The market faces challenges due to volatility in aluminium prices influenced by global energy costs, geopolitical tensions, and raw material supply disruptions. Sudden price spikes increase the cost of extrusion, fabrication, and final window installations, impacting profitability for manufacturers and contractors. Import-dependent regions face additional risks from logistics delays and tariffs. These fluctuations complicate production planning and contract pricing, forcing companies to adopt hedging strategies, diversify supplier networks, and improve operational efficiency to maintain competitiveness.
2. Competition from Alternative Window Materials
Despite strong market presence, aluminium window systems compete with uPVC, composite, and timber solutions that offer lower upfront costs or better thermal insulation in specific climates. uPVC windows, in particular, gain traction in residential markets due to affordability and low maintenance requirements. This competition pressures aluminium manufacturers to invest in thermal-break technologies, advanced coatings, and value-added customization to differentiate their products. Without continuous innovation, aluminium systems may lose share in cost-sensitive and energy-regulated building segments.
Regional Analysis
North America
North America accounts for around 15% market share, with demand driven by growing renovation activity and energy-efficiency requirements across residential and commercial buildings. The U.S. remains the largest contributor, supported by rising adoption of durable, low-maintenance aluminium frames in high-rise construction. Manufacturers benefit from advanced extrusion technologies that improve precision and performance. Increasing emphasis on green building certifications and stricter thermal performance standards continues to push builders toward upgraded aluminium window systems. Overall, the region maintains steady growth backed by strong construction and retrofit investments.
Asia-Pacific
Asia-Pacific dominates the Aluminium Window System Market with around 50% market share, supported by rapid urbanization, expanding residential construction, and large commercial infrastructure projects. China and India drive most of the demand as developers prefer aluminium for its durability, low maintenance, and design flexibility. Government investments in smart cities and sustainable buildings further strengthen adoption. Growing local extrusion capacity also reduces production costs, enabling wider use of aluminium frames in both premium and mid-range projects. The region’s strong construction pipeline ensures continued leadership in overall market volume.
Europe
Europe holds about 20% market share, driven by strict building energy regulations and widespread use of thermally efficient window systems. Countries such as Germany, the U.K., and France lead demand due to strong renovation activity and high emphasis on sustainable architectural designs. Aluminium windows gain preference for their superior insulation when paired with thermal-break technology and advanced glazing. Rising adoption of slim-frame and modern façade solutions also supports market expansion. The region’s mature construction sector ensures stable, high-value demand, especially in commercial and institutional buildings.
Latin America
Latin America represents around 8–10% market share, driven by expanding urban housing demand and increasing use of aluminium frames in mid-rise and commercial construction. Brazil and Mexico lead the region, supported by infrastructure upgrades and rising preference for cost-efficient, lightweight window systems. Although the market is price-sensitive, aluminium's long lifespan and low maintenance requirements strengthen adoption. Gradual growth in industrial facilities and public-sector projects further supports demand. As construction activity stabilizes and modernization initiatives continue, the region exhibits steady and improving market potential.
Middle East & Africa
The Middle East & Africa region holds about 5% market share, supported by large-scale commercial projects, luxury residential developments, and government-led infrastructure expansion. Aluminium windows are widely preferred due to their corrosion resistance and suitability for harsh climatic conditions. Countries such as the UAE, Saudi Arabia, and South Africa lead adoption as they invest in modern architectural façades and energy-efficient building designs. Growing interest in high-performance window systems with improved insulation and custom aesthetics contributes to gradual but consistent market growth across the region.
Market Segmentations:
By Product:
- Flat products
- Extruded products
By Processing Method:
- Rolling
- Extruding
By Application:
- Transport
- Construction
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Aluminium Window System Market features a competitive landscape led by major players such as Pella Corporation, SIERRA PACIFIC WINDOWS, Masonite, Cornerstone Building Brands, Inc., JELD-WEN, Inc., Steves & Sons Inc., ANDERSEN CORPORATION, Marvin, PGT INNOVATIONS, and Kömmerling. The Aluminium Window System Market remains highly competitive, driven by continuous advancements in design efficiency, durability, and energy performance. Manufacturers focus on integrating thermal insulation technologies, corrosion-resistant alloys, and slim-frame aesthetics to meet evolving building standards and customer preferences. The market benefits from growing construction activity, with companies strengthening their portfolios through automated fabrication, precision engineering, and modular system development. Sustainability remains a major competitive factor, encouraging adoption of recyclable materials and low-carbon production processes. Firms also enhance competitiveness through strategic distribution expansions, digital configurators, and customized architectural solutions, enabling them to cater to diverse residential, commercial, and industrial applications while maintaining strong market differentiation.
Key Player Analysis
- Pella Corporation
- SIERRA PACIFIC WINDOWS
- Masonite
- Cornerstone Building Brands, Inc.
- JELD-WEN, Inc.
- Steves & Sons Inc.
- ANDERSEN CORPORATION
- Marvin
- PGT INNOVATIONS
- Kömmerling
Recent Developments
- In August 2024, Home Electrification and Appliance Rebates (HEAR) program was launched by Arizona which is designed to help low- and middle-income households save on energy-efficient HVAC equipment and other appliances.
- In April 2024, Andersen Corporation announced the expansion of its retractable screen portfolio by launching a retractable screen for Andersen patio doors. This new product focuses on offering seamless access to fresh air and unobstructed views while keeping insects out by combining form with function for enhanced functionality and comfort.
- In February 2024, Pella Corporation introduced the Steady Set Interior Installation System at the International Builders' Show (IBS) in Las Vegas. The new system is recognized for its speed, efficiency, and safety, allowing for most of the window installation to be completed from inside the home.
Report Coverage
The research report offers an in-depth analysis based on Product, Processing Method, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will adopt more energy-efficient aluminium systems to meet stricter building performance standards.
- Manufacturers will increase the use of recyclable and low-carbon aluminium to support sustainability goals.
- Demand will grow for slim-profile and minimalist frame designs in modern residential and commercial projects.
- Automation and digital fabrication technologies will enhance production accuracy and reduce lead times.
- Smart window systems with integrated sensors and automated controls will gain wider acceptance.
- Thermal-break technologies will continue to advance, improving insulation and reducing heat transfer.
- Urbanization and infrastructure development will boost demand for durable aluminium window solutions.
- Companies will expand customization options to meet diverse architectural and aesthetic requirements.
- Strategic collaborations with builders, architects, and façade specialists will strengthen market presence.
- Growth in renovation and retrofit activities will increase adoption of high-performance aluminium window upgrades.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Energy-Efficient Building Solutions
The push for energy-efficient buildings is accelerating demand for aluminium window systems, as these frames support advanced glazing and thermal-break technologies that improve insulation and help meet global green building standards. Government incentives and sustainability certifications further encourage adoption in both new construction and renovation projects.
Rapid Urbanization and Infrastructure Expansion
Asia-Pacific and other emerging regions are experiencing rapid urbanization and large-scale infrastructure investments, driving significant demand for modern, durable, and lightweight aluminium window systems in residential, commercial, and public sector developments.
Advancements in Extrusion and Fabrication Technologies
Technological improvements in extrusion and fabrication enable the production of complex, high-precision aluminium profiles with enhanced strength, slim aesthetics, and superior insulation. These innovations support the growing preference for premium, high-performance window systems in both commercial and residential applications.
Sustainability and Use of Recycled Aluminium
Manufacturers are increasingly using recycled aluminium, which reduces energy consumption and carbon footprint, aligning with circular economy goals and green building requirements. This shift is making aluminium window systems more attractive for environmentally conscious developers and public projects.
Growth in Smart and Automated Window Systems
The integration of sensors, automation, and IoT-enabled controls into aluminium window systems is creating new opportunities, as demand rises for smart homes and commercial buildings that prioritize occupant comfort, energy management, and advanced building automation.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Aluminium Window System Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Aluminium Window System Market projected to grow between 2025 and 2032?
Which Aluminium Window System Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Aluminium Window System Market?
Who are the leading companies in the Aluminium Window System Market?
Which region commanded the largest share of the Aluminium Window System Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Flat products
- 1.2.2 Extruded products
- 1.2.3 Forged products
- 1.2.4 Cast products
- 1.2.5 Long products
- 1.3 By Application
- 1.3.1 Construction
- 1.3.2 Transport
- 1.3.3 Electrical & Electronics
- 1.3.4 Machinery
- 1.3.5 Consumer Durables
- 1.4 By Processing Method
- 1.4.1 Extruding
- 1.4.2 Rolling
- 1.4.3 Drawing
- 1.4.4 Casting
- 1.4.5 Forging
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 111.62 billion → 2032: USD 146.3 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Aluminium Window System Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Aluminium Window System Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Aluminium Window System Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Aluminium Window System Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Aluminium Window System Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Aluminium Window System Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Aluminium Window System Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Aluminium Window System Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 111.62 billion → 2032: USD 146.3 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Aluminium Window System Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Flat products
- 12.3.7.2 Extruded products
- 12.3.7.3 Forged products
- 12.3.7.4 Cast products
- 12.3.7.5 Long products
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Construction
- 12.4.7.2 Transport
- 12.4.7.3 Electrical & Electronics
- 12.4.7.4 Machinery
- 12.4.7.5 Consumer Durables
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Processing Method - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Extruding
- 12.5.7.2 Rolling
- 12.5.7.3 Drawing
- 12.5.7.4 Casting
- 12.5.7.5 Forging
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Aluminium Window System End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Aluminium Window System Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Aluminium Window System Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Aluminium Window System Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Pella Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 ANDERSEN CORPORATION
- 18.4 JELD-WEN, Inc.
- 18.5 Masonite
- 18.6 Cornerstone Building Brands, Inc.
- 18.7 Marvin
- 18.8 PGT INNOVATIONS
- 18.9 SIERRA PACIFIC WINDOWS
- 18.10 Steves & Sons Inc.
- 18.11 Kömmerling
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

