
Market Overview
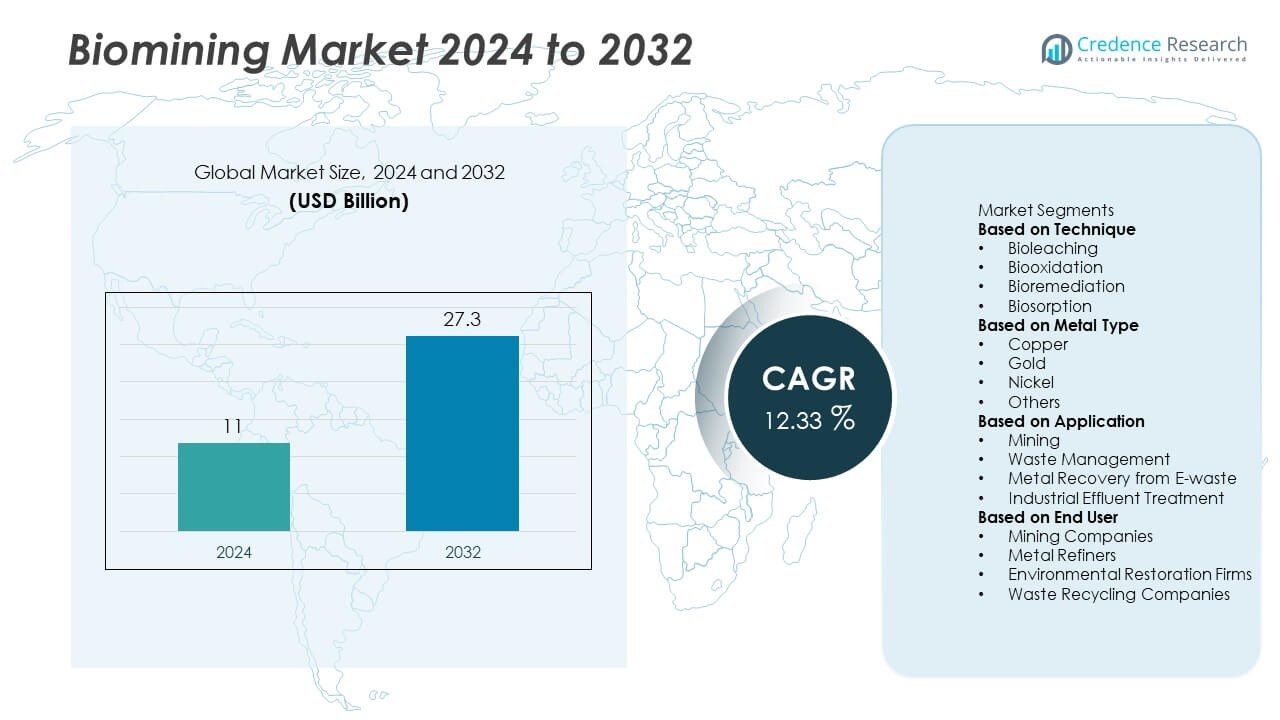
The Biomining Market was valued at USD 11 billion in 2024 and is projected to reach USD 27.3 billion by 2032, growing at a 12.33% CAGR during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Biomining Market Size 2024 | USD 11 Billion |
| Biomining Market, CAGR | 12.33% |
| Biomining Market Size 2032 | USD 27.3 Billion |
Top players in the Biomining market include Biomine USA, Rio Tinto, BHP Group, Freeport-McMoRan, Glencore, Anglo American, Metso Outotec, Barrick Gold Corporation, Denison Mines, and BioteQ Environmental Technologies. These companies strengthen their positions by adopting advanced bioleaching and biooxidation technologies to recover metals from low-grade ores, mining waste, and e-waste streams while reducing environmental impact. Their focus on microbial optimization, bioreactor efficiency, and sustainable processing helps drive market expansion. North America leads the market with a 33% share, supported by strong mining infrastructure and high adoption of eco-friendly extraction methods, followed by Asia Pacific and Europe with growing biomining applications.
Market Insights
- The Biomining market reached USD 11 billion in 2024 and will grow at a 12.33% CAGR through the forecast period.
- Demand rises as mining companies adopt eco-friendly extraction methods, using bioleaching and biooxidation to process low-grade ores while meeting strict environmental regulations.
- Key trends include rapid growth of microbial metal recovery from e-waste and strong advancement in engineered microorganisms, with bioleaching leading the technique segment at a 46% share.
- Competition intensifies as major players expand bioreactor capabilities and invest in microbial engineering, though slow processing rates and limited effectiveness for certain ore types remain restraints.
- North America leads regional adoption with a 33% share, followed by Asia Pacific at 28% and Europe at 27%, supported by strong mining investment, sustainability initiatives, and rising demand for battery and critical metals.
Market Segmentation Analysis:
By Technique
Bioleaching dominates the technique segment with a market share of 46%, driven by its efficiency in extracting metals from low-grade ores while reducing energy use and chemical dependence. This method supports sustainable mining by lowering emissions and minimizing waste generation. Biooxidation gains traction in gold and refractory ore processing, while bioremediation plays a key role in restoring contaminated soils and mine tailings. Biosorption expands across industrial effluent treatment. Growing demand for environmentally sound extraction practices continues to strengthen bioleaching’s leadership in large-scale mining operations.
- For instance, companies like Rio Tinto utilize bioleaching in their operations to extract copper from low-grade ores, significantly reducing energy consumption by up to 30% compared to traditional methods.
By Metal Type
Copper leads the metal type segment with a market share of 41%, supported by extensive adoption of bioleaching for low-grade copper sulfide ores. The process lowers operational costs and enables extraction from deposits unsuitable for conventional methods. Gold follows, driven by rising use of biooxidation to improve recovery from refractory ores. Nickel gains momentum as demand rises for battery-grade materials. Other metals, including cobalt and rare earth elements, show growing potential. Increasing need for sustainable metal recovery reinforces copper’s dominant position in biomining applications.
- For instance, Freeport-McMoRan uses bioleaching at its Morenci mine, extracting copper from ore with lower grades that would otherwise be unprofitable to mine, thus enhancing operational efficiency.
By Application
Mining holds the dominant share in the application segment with a market share of 52%, as companies use biomining to improve extraction efficiency and reduce environmental impact. The method offers strong benefits for processing low-grade ores and reducing waste volumes. Waste management applications grow due to rising need for bioremediation of contaminated mining zones. Metal recovery from e-waste expands quickly as industries seek cost-effective, eco-friendly extraction of copper, gold, and rare elements. Industrial effluent treatment also advances, supported by biosorption technologies. Mining’s strong operational suitability keeps it the leading application.
Key Growth Drivers
Growing Need for Eco-Friendly Metal Extraction
Demand for sustainable extraction methods drives strong adoption of biomining across global mining operations. Companies seek alternatives to energy-intensive smelting and chemical-heavy leaching to reduce emissions and environmental damage. Bioleaching and biooxidation offer lower operating costs, reduced waste generation, and improved efficiency for low-grade ores, making them suitable for large-scale use. Rising global pressure to adopt greener technologies strengthens the shift toward biological metal recovery, especially as mining firms commit to decarbonization and environmentally responsible extraction practices.
- For instance, the Zijinshan mine in China, operated by Zijin Mining Industry Co., uses commercial bioleaching to treat low-grade copper ore, achieving an estimated 80% recovery of copper with the process also reportedly leading to energy savings and a reduction in greenhouse gas emissions compared to conventional smelting.
Rising Demand for Critical and Battery Metals
The increasing demand for copper, nickel, cobalt, and rare earth elements fuels the growth of biomining as conventional reserves decline and ore grades drop. Biomining techniques help extract metals from complex, refractory, or low-grade ore bodies that traditional methods cannot exploit economically. The expansion of electric vehicles, renewable energy systems, and electronics accelerates the need for sustainable metal recovery. Biomining supports long-term supply security by enabling extraction from unconventional deposits while maintaining lower environmental impact.
- For instance, Vale S.A. has partnered with the Mining Innovation, Rehabilitation, and Applied Research Corporation (MIRARCO) on an industrial research program to develop, pilot, and work towards commercializing bioleaching processes for recovering nickel and cobalt from mine waste and low-grade pyrrhotite tailings in Ontario, Canada, improving the potential recovery of metals from materials that would otherwise be considered waste.
Expansion of Bioremediation and Waste Recovery Applications
The market grows as industries adopt biomining technologies to treat contaminated soils, tailings, and metal-laden effluents. Bioremediation and biosorption provide cost-effective solutions for cleaning mining waste, recovering valuable metals, and reducing long-term environmental liabilities. Growing regulations on waste disposal, water contamination, and land restoration strengthen adoption across mining, industrial processing, and waste management sectors. Rising interest in circular economy practices further boosts the use of microbial recovery systems to extract metals from e-waste and industrial residues.
Key Trends & Opportunities
Growth of E-Waste Metal Recovery Using Microbial Processes
A major trend involves expanding biomining applications in e-waste recycling to recover gold, copper, nickel, and rare earth elements from discarded electronics. Microbial processes offer safer alternatives to hazardous chemical methods and improve recovery yields from complex waste streams. This trend creates opportunities for scalable, low-energy recycling plants in regions experiencing rapid electronic waste generation. The shift toward sustainable urban mining strengthens the role of biomining as a key technology in metal recovery from secondary sources.
- For instance, Umicore, a global leader in materials technology, uses a unique pyro-hydrometallurgical process in their electronic waste and battery recycling facilities, combining high-temperature smelting with subsequent chemical treatment, which enables high recovery rates for precious metals like gold and valuable battery metals such as cobalt, nickel, and copper.
Advancements in Microbial Engineering and Bio-Reactors
Technological progress in microbial engineering, genetic modification, and controlled bioreactor systems is improving extraction speeds, metal recovery rates, and process stability. Engineered microbes enhance tolerance to extreme conditions and increase efficiency for multiple metals. Advanced reactors allow precise control of temperature, aeration, and nutrient conditions, enabling continuous and high-yield operations. These developments open opportunities for commercializing biomining in large-scale industrial operations and expanding use across diverse metal categories.
- For instance, BASF has developed a chemical product called LixTRA™, a novel leaching aid that enhances bioleaching efficiency for copper recovery by increasing the wettability of ore particles.
Rising Adoption of Low-Carbon Mining Technologies
Mining companies increasingly adopt biomining to align with global decarbonization goals and ESG commitments. Bio-based extraction methods help reduce carbon emissions, energy use, and chemical discharge. This trend strengthens opportunities for biomining companies to partner with large mining firms seeking cleaner operations and regulatory compliance. Growing investments in green mining facilities and government incentives for sustainable technologies further support market expansion.
Key Challenges
Slow Processing Rates Compared to Conventional Methods
Biomining processes often operate more slowly than traditional chemical leaching or smelting, creating challenges for high-volume production environments. Operators may require longer extraction cycles to achieve desired metal recovery levels, limiting adoption in mines with tight production schedules. This constraint intensifies when handling complex ores or operating in colder climates. Companies must balance sustainability advantages with operational efficiency, and many continue investing in microbial optimization to address speed limitations.
Limited Effectiveness Across Certain Ore Types
Biomining performs well with sulfide ores but is less effective for oxide ores or materials with limited microbial accessibility. This restricts its use across broader mineral deposits and limits adoption among mining firms dependent on conventional extraction routes. Variability in ore composition, metal concentration, and mineral structure affects microbial activity and recovery rates. As a result, biomining companies must invest in research to improve compatibility with diverse ore types while addressing technical barriers that constrain full-scale implementation.
Regional Analysis
North America
North America holds a market share of 33%, driven by strong investment in sustainable mining technologies and advanced research capabilities in bioleaching and bioremediation. The region benefits from large copper and gold mining operations that increasingly adopt biomining to reduce environmental impact and process low-grade ores. Growing e-waste recycling initiatives also support market expansion. Government regulations promoting cleaner extraction methods and reduced chemical use further encourage adoption. Strong collaboration between mining companies, biotechnology firms, and research institutions positions North America as a leading market for commercial biomining applications.
Europe
Europe accounts for a market share of 27%, supported by stringent environmental regulations, strong focus on circular economy principles, and rising demand for low-carbon extraction technologies. The region invests heavily in microbial-based metal recovery to reduce reliance on imported critical minerals. Biomining is also used in soil restoration, waste management, and industrial effluent treatment. Growing interest in recovering metals from e-waste enhances market activity, especially in technologically advanced countries. Europe’s commitment to sustainable resource management and research-driven innovation strengthens its position in the global biomining landscape.
Asia Pacific
Asia Pacific holds a market share of 28%, driven by rapid industrialization, expanding mining activities, and rising metal consumption in electronics, construction, and renewable energy. Countries with large mineral reserves adopt biomining to process low-grade copper, gold, and nickel ores while reducing environmental damage. The region also witnesses strong growth in e-waste recycling, creating new opportunities for microbial extraction technologies. Government initiatives promoting sustainable mining practices and rising investments in biotechnology accelerate adoption. Asia Pacific’s strong mining output and growing research capabilities support its rising global influence.
Latin America
Latin America captures a market share of 8%, supported by abundant copper, gold, and nickel reserves and increasing use of bioleaching in large-scale mining operations. Countries with strong mineral industries adopt biomining to process low-grade ores and reduce energy-intensive smelting. Environmental concerns and community pressures encourage mining companies to integrate microbial technologies for tailings treatment and land restoration. The region also sees expanding interest in metal recovery from mining waste as governments promote sustainable extraction practices. Growing foreign investment and partnerships with global biotechnology firms support steady growth.
Middle East & Africa
The Middle East & Africa region holds a market share of 4%, driven by growing interest in sustainable mining practices across countries with significant mineral resources. The region adopts biomining to enhance extraction efficiency and manage environmental impact in copper, gold, and uranium deposits. Limited water resources encourage the use of bio-based methods that require fewer chemicals and less energy. Emerging mining projects and rising investment in resource development create new opportunities. Although adoption remains gradual, increasing focus on responsible mining and technology partnerships supports market expansion across select countries.
Market Segmentations:
By Technique
- Bioleaching
- Biooxidation
- Bioremediation
- Biosorption
By Metal Type
- Copper
- Gold
- Nickel
- Others
By Application
- Mining
- Waste Management
- Metal Recovery from E-waste
- Industrial Effluent Treatment
By End User
- Mining Companies
- Metal Refiners
- Environmental Restoration Firms
- Waste Recycling Companies
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape includes major players such as Biomine USA, Rio Tinto, BHP Group, Freeport-McMoRan, Glencore, Anglo American, Metso Outotec, Barrick Gold Corporation, Denison Mines, and BioteQ Environmental Technologies. These companies strengthen their positions by integrating advanced bioleaching, biooxidation, and bioremediation technologies into mining and waste recovery operations. Their strategies focus on improving metal recovery rates from low-grade ores, expanding microbial processing capabilities, and reducing environmental impact. Many invest in R&D partnerships with biotechnology institutes to accelerate microbial strain development and optimize bio-reactor performance. Technological advancements in microbial engineering, controlled leaching environments, and real-time monitoring enhance operational efficiency. Companies also expand biomining applications into e-waste recycling and contaminated site restoration to meet rising sustainability demands. Strengthening ESG commitments, reducing chemical usage, and lowering energy consumption remain key priorities that help these players maintain competitive advantage in the global biomining market.
Key Player Analysis
- Biomine USA
- Rio Tinto
- BHP Group
- Freeport-McMoRan
- Glencore
- Anglo American
- Metso Outotec
- Barrick Gold Corporation
- Denison Mines Corp.
- BioteQ Environmental Technologies
Recent Developments
- In June 2025, Rio Tinto reported that its Mining Microbiome Analytics Platform (“M‑MAP”) project collected over 2,500 rock, water, soil and tailings samples and developed one of the largest mine‑site microbial databases in the industry.
- In 2024, Rio Tinto filed a patent application for a microbial‑assisted heap leaching process targeting copper‑containing sulfidic ores and waste materials.
- In August 2023, the BHP Group, the majority owner (57.5%) and operator of the Escondida copper mine, announced that it would complete strategic studies on options including the application of its proprietary Full SaL (Simple Approach to Leaching) technology at the mine.
Report Coverage
The research report offers an in-depth analysis based on Technique, Metal Type, Application, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Adoption of bioleaching and biooxidation will increase as mining firms target low-impact extraction.
- Demand for battery metals will accelerate biomining use in copper, nickel, and cobalt recovery.
- Engineered microorganisms will improve metal recovery rates and processing efficiency.
- E-waste recycling will emerge as a major growth area for microbial metal extraction.
- Bioremediation technologies will expand to support mine-site restoration and soil cleanup.
- Mining companies will invest more in bioreactors and controlled microbial processing systems.
- ESG commitments will drive faster replacement of chemical-heavy extraction methods.
- Governments will promote biomining through green mining policies and sustainability incentives.
- Partnerships between mining firms and biotech companies will strengthen technological innovation.
- Biomining will become a key solution for accessing metals from complex and low-grade ores.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Biomining market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Biomining market projected to grow between 2025 and 2032?
Which Biomining market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Biomining market?
Who are the leading companies in the Biomining market?
Which region commanded the largest share of the Biomining market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Biomining Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Biomining Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 11 billion → 2032: USD 27.3 billion)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Biomining Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Biomining Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Biomining Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Biomining Market Drivers
- 3.3 Biomining Market Restraints & Challenges
- 3.4 Biomining Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Biomining Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Biomining Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Biomining category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Biomining Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Biomining Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Biomining. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Biomining Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Biomining Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Biomining Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Biomining (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Biomining
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Biomining Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Biomining Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Biomining Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Biomining Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Biomining Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Biomining Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Biomining Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Biomining Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
