
Market Overview:
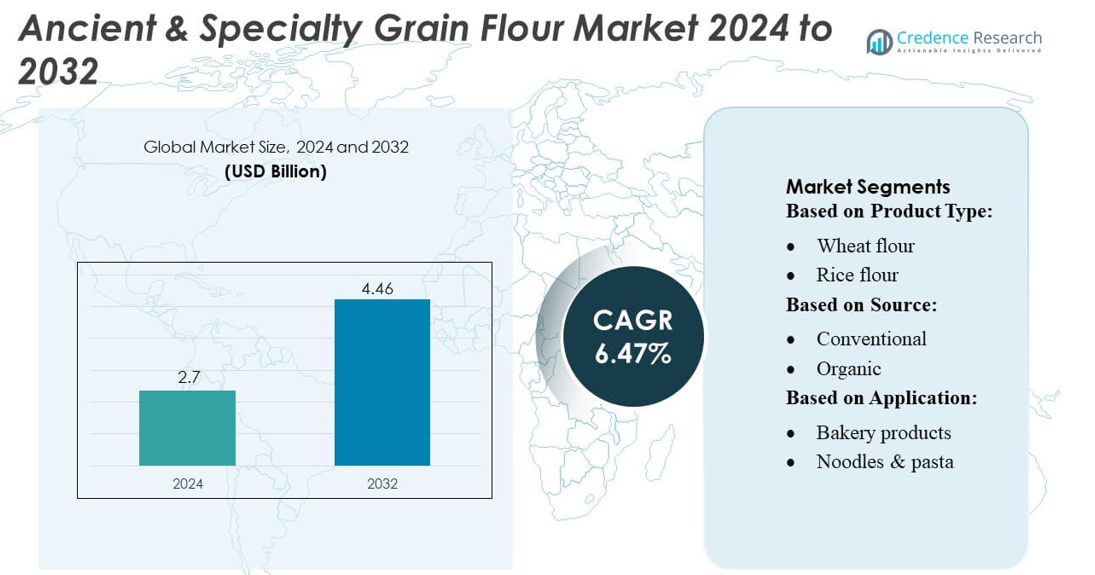
Ancient & Specialty Grain Flour Market size was valued USD 2.7 billion in 2024 and is anticipated to reach USD 4.46 billion by 2032, at a CAGR of 6.47% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Ancient & Specialty Grain Flour Market Size 2024 | USD 2.7 billion |
| Ancient & Specialty Grain Flour Market, CAGR | 6.47% |
| Ancient & Specialty Grain Flour Market Size 2032 | USD 4.46 billion |
The Ancient & Specialty Grain Flour market is led by prominent companies including Dave's Killer Bread, ADM, King Arthur Baking, ConAgra Foods, Bay State Milling, Ardent Mills, Bobs Red Mill, Project Potluck, Cargill, and General Mills, which drive innovation and expand product portfolios to include gluten-free, organic, and nutrient-rich flours. These players focus on scaling production capacities, enhancing milling technologies, and developing fortified and functional grain flours to meet growing consumer demand. North America emerges as the leading region, holding a significant market share of approximately 35%, driven by high consumer awareness, strong retail infrastructure, and widespread adoption of health-focused and clean-label products. Continuous investments in product development, sustainable sourcing, and distribution across retail, foodservice, and e-commerce channels enable these companies to maintain competitive advantage and capture emerging opportunities, particularly in bakery, convenience food, and functional food applications.
Market Insights
- The Ancient & Specialty Grain Flour Market size was valued at USD 2.7 billion in 2024 and is anticipated to reach USD 4.46 billion by 2032, growing at a CAGR of 6.47% during the forecast period.
- North America is the leading region with approximately 35% market share, driven by high consumer awareness, strong retail infrastructure, and widespread adoption of gluten-free, organic, and functional grain flours.
- Wheat and almond flours dominate the product segment due to versatility and high demand in bakery, noodles, and convenience food applications, while organic flours are gaining traction as consumers increasingly prefer clean-label and sustainable products.
- Key drivers include rising health consciousness, growing preference for gluten-free and high-protein diets, and expansion of functional and fortified flour offerings across bakery and convenience food segments.
- Competitive players focus on scaling production, improving milling technologies, product innovation, and distribution across retail, e-commerce, and foodservice channels, while market restraints include high raw material costs and limited awareness in emerging regions.
Market Segmentation Analysis:
By Product Type
Wheat flour dominates the Ancient & Specialty Grain Flour market, accounting for the largest share due to its versatility and wide adoption across bakery and confectionery products. For instance, companies like Bob’s Red Mill have expanded their whole wheat and spelt flour lines, achieving annual production volumes exceeding 50,000 metric tons. Rising consumer preference for high-protein, fiber-rich flours and clean-label ingredients drives demand. Alternative flours such as almond, chickpea, and oat flours are witnessing growth due to gluten-free trends and functional health benefits, supporting market diversification.
- For instance, Bob's Red Mill Natural Foods - a leading specialist in whole‑grain and alternative flours - offers over 400 different products spanning traditional wheat flours, ancient‑grain flours, and gluten‑free varieties.
By Source
Conventional grain flours hold the majority market share, primarily driven by established production infrastructure and consistent availability. Leading producers such as King Arthur Flour have optimized milling processes to maintain quality across large-scale conventional wheat and rice flour production, reaching capacities above 40,000 tons annually. However, organic flours are rapidly gaining traction, fueled by increasing health awareness and clean-label trends. Companies like Arrowhead Mills report that organic variants now contribute over 20% of their overall revenue, reflecting growing consumer preference for sustainably sourced and non-GMO ingredients.
- For instance, ADM’s global logistics network - including roughly 150 warehouses and terminals, and a fleet comprising nearly 32,000 rail cars, 610 trucks, and over 1,700 trailers - ensures stable sourcing, storage, and distribution of raw grain and milled flour worldwide.
By Application
Bakery products represent the dominant application segment, capturing the largest market share due to steady demand for bread, cakes, and pastry products. For instance, large-scale industrial bakeries sourcing specialty flours like teff, sorghum, and rye from producers such as General Mills report annual procurement volumes exceeding 30,000 tons. Noodles, pasta, and convenience foods are also driving demand, supported by the rising adoption of gluten-free and high-protein diets. Growth is fueled by urbanization, rising disposable incomes, and increasing consumer interest in functional and ancient grains that enhance texture, flavor, and nutritional value.
Key Growth Drivers
Rising Health Awareness and Nutritional Demand
Increasing consumer focus on health and wellness drives the adoption of ancient and specialty grain flours. Flours such as quinoa, teff, and chickpea are recognized for high protein, fiber, and micronutrient content, fueling demand in bakery, confectionery, and convenience food applications. Companies are expanding product lines to offer nutrient-dense alternatives, with large-scale producers reporting annual output exceeding tens of thousands of metric tons. Functional benefits and gluten-free properties further enhance market appeal, especially among urban and health-conscious consumers.
- For instance, HealthSense® High‑Fiber Wheat Flour delivers up to 10× the fiber of traditional refined wheat flour, while maintaining taste, texture, and baking functionality.
Expansion of Gluten-Free and Specialty Diets
Growing prevalence of gluten intolerance, celiac disease, and the popularity of low-carb or high-protein diets contribute to market growth. Specialty flours like almond, rice, and chickpea are increasingly used in gluten-free bakery products and pasta, driving adoption across retail and foodservice segments. Producers are investing in dedicated processing lines to ensure cross-contamination-free production, increasing consumer confidence. For instance, manufacturers have scaled production of chickpea and almond flours to meet annual demands exceeding 20,000 tons in North America and Europe.
- For instance, Red Mill still uses traditional quartz millstones quarried in France, where carefully controlled inter‑stone spacing and slow-speed grinding preserve nutrient integrity and flavor, ensuring consistency across its over 400 product offerings.
Innovation in Product Formats and Applications
Product innovation in ready-to-use mixes, flours blended with functional ingredients, and fortified variants expands market potential. Companies like Bob’s Red Mill and Arrowhead Mills develop pre-mixes for bakery, pasta, and convenience foods, improving shelf stability and ease of use. Technological advancements in milling and extrusion allow preservation of nutrients while enhancing texture and taste. Such innovations cater to both industrial and home consumers, driving higher adoption rates and reinforcing the market’s growth across multiple applications, including bakery, noodles, and animal feed.
Key Trends & Opportunities
Rising Demand for Organic and Clean-Label Products
Organic and sustainably sourced grain flours are gaining traction as consumers increasingly prioritize clean-label ingredients and environmentally friendly production. Organic wheat, spelt, and almond flours now represent a growing share of sales in North America and Europe. Manufacturers are expanding organic production lines, with some reporting over 20% of annual revenue from organic variants. This trend presents opportunities for premium product launches, private-label partnerships, and export-oriented strategies targeting health-conscious and environmentally aware consumers globally.
- For instance, Glanbia reported that "nutritional and functional ingredients" (including proteins, nutrients, vitamins, trace elements, minerals, bioactive ingredients and related premixes) account for 53.7% of its net sales mix.
Emergence of Ancient Grains in Bakery and Convenience Foods
Ancient grains such as teff, sorghum, and millet are increasingly incorporated into breads, pasta, and snack products. For instance, industrial bakeries sourcing teff flour for flatbreads report annual procurement volumes exceeding 10,000 tons. The trend is driven by both nutritional value and premium positioning, appealing to urban consumers seeking functional and novel flavors. Growth in ready-to-eat and convenience segments amplifies opportunities for product differentiation, allowing manufacturers to create value-added offerings with enhanced protein, fiber, and antioxidant content.
- For instance, General Mills the company notes that 86% of its cereal products provide at least 8 grams of whole grain per labeled serving, ensuring consistent nutritional value per portion.
Key Challenges
High Production Costs and Supply Chain Constraints
Specialty and ancient grains often incur higher cultivation and milling costs compared with conventional wheat or rice. Limited cultivation regions, dependence on seasonal harvests, and complex milling processes increase input costs. Companies face challenges in maintaining consistent supply, particularly for niche grains like teff or quinoa. Fluctuating raw material prices impact profit margins, making cost management crucial. This challenge is amplified in regions with limited infrastructure or organic certification requirements, constraining large-scale adoption and creating barriers for smaller or emerging producers.
Limited Consumer Awareness in Emerging Markets
While demand for ancient and specialty grains is growing in developed regions, awareness remains low in several emerging markets. Consumers often lack knowledge about health benefits, cooking methods, and applications, limiting adoption. Manufacturers must invest in marketing, education, and product demonstrations to increase familiarity. Additionally, higher retail prices of specialty flours compared with conventional options can hinder market penetration, necessitating targeted strategies to balance affordability and nutritional appeal while driving growth in underdeveloped regions.
Regional Analysis
North America
North America leads the Ancient & Specialty Grain Flour market, holding the largest share of approximately 35%, driven by high consumer awareness of health and wellness trends. The region benefits from a mature retail sector, widespread adoption of gluten-free and organic products, and established industrial bakery infrastructure. Companies like Bob’s Red Mill and Arrowhead Mills have scaled production, supplying over 50,000 tons annually of specialty flours including almond, chickpea, and quinoa. Strong demand for functional, high-protein, and clean-label products in the U.S. and Canada continues to drive market expansion and product innovation.
Europe
Europe accounts for roughly 28% of the market, with robust demand for organic and ancient grain flours in bakery, pasta, and convenience food segments. Countries such as Germany, France, and the U.K. prioritize clean-label, gluten-free, and high-fiber products, supporting growth in rye, spelt, and oat flours. Leading producers, including Doves Farm and Finax, have optimized production lines to deliver over 40,000 tons annually of specialty flours. Strong health-conscious consumer behavior, combined with government support for organic farming, positions Europe as a key growth region for both conventional and organic ancient grain flours.
Asia-Pacific
The Asia-Pacific region holds an estimated 20% market share, driven by rising urbanization, increasing disposable income, and evolving dietary patterns. Growing consumer interest in functional foods and protein-rich diets supports adoption of ancient grains such as millet, sorghum, and chickpea. Local players, alongside international entrants, are expanding production and distribution networks to meet rising demand in China, India, and Japan. Industrial bakery, convenience food, and health-focused retail segments are primary growth areas. Awareness campaigns highlighting nutritional benefits of specialty flours further contribute to market penetration, particularly in urban and semi-urban centers.
Latin America
Latin America contributes around 10% to the market, with growing interest in gluten-free and high-fiber flours. Consumers in Brazil, Mexico, and Argentina increasingly prefer quinoa, chickpea, and amaranth flours for bakery and snack applications. Supply chain developments, coupled with government initiatives supporting organic and sustainable agriculture, are enhancing the availability of ancient grains. Local producers are scaling production to meet both domestic and export demands, while multinational brands expand distribution networks. Rising urban health-conscious populations and increasing investment in functional foods provide opportunities for further market growth in the region.
Middle East & Africa (MEA)
MEA represents roughly 7% of the global market, with demand concentrated in urban centers where health awareness and premium product consumption are rising. Ancient grains like millet, sorghum, and chickpea are increasingly used in bakery, noodles, and convenience foods. Import reliance is high due to limited local cultivation, prompting international suppliers to establish distribution partnerships. Rapid growth in retail chains and foodservice sectors, alongside increased interest in functional and gluten-free products, drives market expansion. While price sensitivity remains a challenge, urban consumer adoption and awareness campaigns create significant growth potential.
Market Segmentations:
By Product Type:
- Wheat flour
- Rice flour
By Source:
- Conventional
- Organic
By Application:
- Bakery products
- Noodles & pasta
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Ancient & Specialty Grain Flour market is highly competitive, with leading players including Dave's Killer Bread, ADM, King Arthur Baking, ConAgra Foods, Bay State Milling, Ardent Mills, Bobs Red Mill, Project Potluck, Cargill, and General Mills. The Ancient & Specialty Grain Flour market is highly competitive, driven by continuous product innovation, expanding distribution channels, and increasing consumer demand for health-oriented and functional flours. Companies focus on diversifying product portfolios to include gluten-free, organic, and nutrient-rich flours derived from ancient grains such as quinoa, teff, millet, and chickpea. Strategic initiatives include scaling production capacities, improving milling technologies, and enhancing supply chain efficiency to meet rising global demand. Market participants emphasize quality certifications, clean-label products, and sustainable sourcing to differentiate their offerings. Additionally, expansion into e-commerce and retail channels, alongside collaborations with bakery and convenience food manufacturers, strengthens market presence. Continuous innovation, coupled with marketing that highlights nutritional benefits, ensures competitive advantage in this dynamic landscape, fostering growth while meeting evolving consumer preferences and supporting adoption across bakery, noodles, pasta, and convenience food applications.
Key Player Analysis
- Dave's Killer Bread
- ADM
- King Arthur Baking
- ConAgra Foods
- Bay State Milling
- Ardent Mills
- Bobs Red Mill
- Project Potluck
- Cargill
- General Mills
Recent Developments
- In August 2024, Ardent Mills announced plans to update and expand its flour mill in Commerce City, Colorado. The investment will modernize the facility while supporting regional customers and local agricultural, manufacturing and food industries.
- In January 2024, The Italian Milling Industry Association, which is co-funded by the European Commission, announced the launch of its campaign called as Pure Flour From Europe in India with an aim to promote the premium soft wheat flour in the country.
- In March 2023, Scoular represents a transformational step for Nepra and its ability to continue pushing the boundaries of novel food the complete convergence of Nepra's R&D into Scoular's global supply chain
Report Coverage
The research report offers an in-depth analysis based on Product Type, Source, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for gluten-free and high-protein flours is expected to rise steadily.
- Organic and clean-label flours will gain greater consumer preference globally.
- Expansion of bakery, convenience food, and functional food applications will drive market growth.
- Adoption of ancient grains like teff, millet, and sorghum will increase across urban and health-conscious consumers.
- Technological advancements in milling and processing will improve product quality and shelf life.
- E-commerce and online retail channels will become major distribution avenues.
- Emerging markets in Asia-Pacific, Latin America, and the Middle East will see faster adoption.
- Product innovation in fortified and nutrient-enhanced flours will continue to attract consumers.
- Sustainability and ethical sourcing will influence procurement and production practices.
- Collaboration with foodservice and bakery industries will create new growth opportunities.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Health Awareness and Nutritional Demand
Consumers are increasingly seeking flours with higher protein, fiber, and micronutrient content, such as quinoa, teff, and chickpea, to support health and wellness goals. This trend is driving demand for ancient and specialty grain flours in bakery, confectionery, and convenience food applications.
Expansion of Gluten-Free and Specialty Diets
The prevalence of gluten intolerance, celiac disease, and the popularity of low-carb or high-protein diets are fueling the adoption of gluten-free flours like almond, rice, and chickpea. Producers are investing in dedicated processing lines to meet the growing demand for specialty diet products.
Innovation in Product Formats and Applications
Companies are developing ready-to-use mixes, fortified blends, and functional flour variants, expanding the market's reach into bakery, pasta, and convenience foods. Technological advancements in milling and extrusion are enhancing product quality and consumer appeal.
Rising Demand for Organic and Clean-Label Products
Consumers are prioritizing organic, non-GMO, and sustainably sourced flours, prompting manufacturers to expand organic product lines and secure clean-label certifications. This shift supports premium pricing and opens new market opportunities, especially in North America and Europe.
Emergence of Ancient Grains in Bakery and Convenience Foods
Ancient grains like teff, millet, and sorghum are being incorporated into breads, snacks, and ready-to-eat foods, appealing to urban and health-conscious consumers seeking novel flavors and enhanced nutritional profiles. This trend is driving product differentiation and market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Ancient & Specialty Grain Flour Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Ancient & Specialty Grain Flour Market projected to grow between 2025 and 2032?
What is the major growth driving factors for global Ancient & Specialty Grain Flour market?
Which Ancient & Specialty Grain Flour Market segment held the largest share in 2024?
Who are the leading companies in the Ancient & Specialty Grain Flour Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Source
- 1.2.1 Conventional
- 1.2.2 Organic
- 1.3 By Application
- 1.3.1 Bakery products
- 1.3.2 Noodles & pasta
- 1.3.3 Convenience foods
- 1.3.4 Confectionery
- 1.3.5 Animal feed
- 1.4 By Product Type
- 1.4.1 Wheat flour
- 1.4.2 Rice flour
- 1.4.3 Almond flour
- 1.4.4 Chickpea flour
- 1.4.5 Oat flour
- 1.4.6 Teff flour
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2.7 billion → 2032: USD 4.46 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Ancient & Specialty Grain Flour Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Ancient & Specialty Grain Flour Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Ancient & Specialty Grain Flour Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Ancient & Specialty Grain Flour Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Ancient & Specialty Grain Flour Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Ancient & Specialty Grain Flour Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Ancient & Specialty Grain Flour Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Ancient & Specialty Grain Flour Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2.7 billion → 2032: USD 4.46 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Ancient & Specialty Grain Flour Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Source - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Conventional
- 12.3.7.2 Organic
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Bakery products
- 12.4.7.2 Noodles & pasta
- 12.4.7.3 Convenience foods
- 12.4.7.4 Confectionery
- 12.4.7.5 Animal feed
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Wheat flour
- 12.5.7.2 Rice flour
- 12.5.7.3 Almond flour
- 12.5.7.4 Chickpea flour
- 12.5.7.5 Oat flour
- 12.5.7.6 Teff flour
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Ancient & Specialty Grain Flour End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Ancient & Specialty Grain Flour Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Ancient & Specialty Grain Flour Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Ancient & Specialty Grain Flour Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Dave's Killer Bread
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 ADM
- 18.4 King Arthur Baking
- 18.5 ConAgra Foods
- 18.6 Bay State Milling
- 18.7 Ardent Mills
- 18.8 Bobs Red Mill
- 18.9 Project Potluck
- 18.10 Cargill
- 18.11 General Mills
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

