
Market Overview:
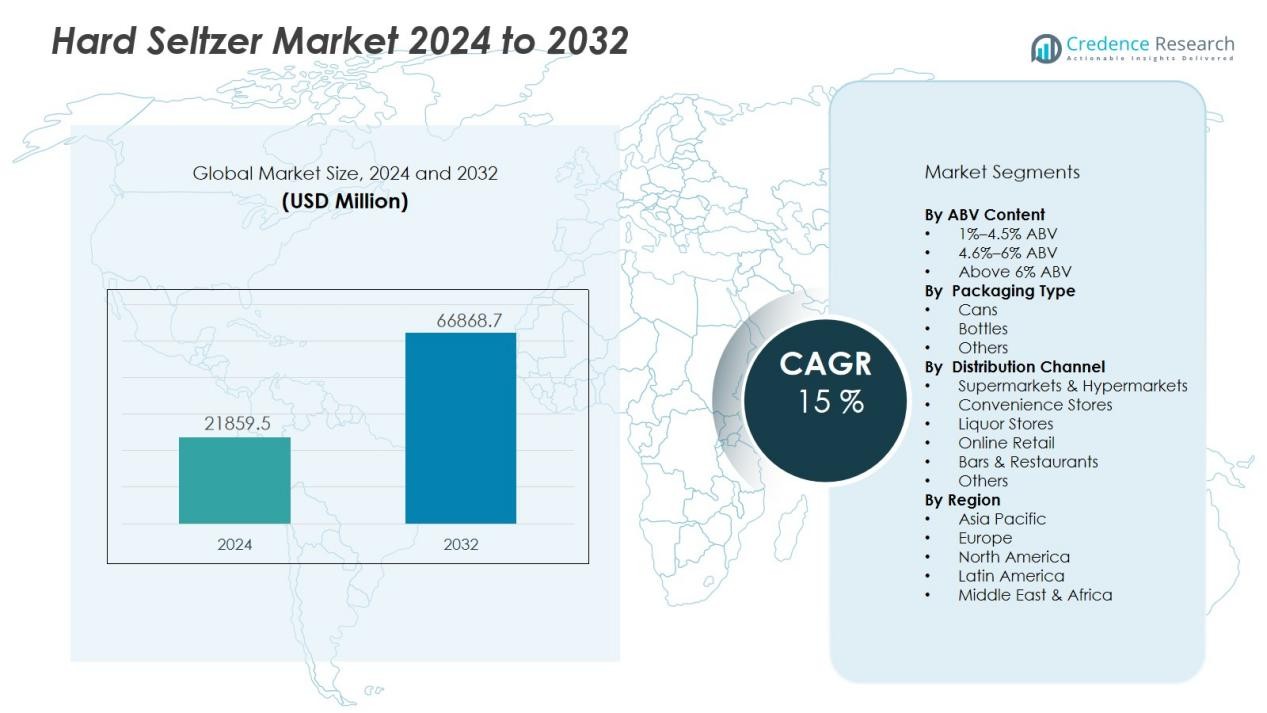
The hard seltzer market size was valued at USD 21859.5 million in 2024 and is anticipated to reach USD 66868.7 million by 2032, at a CAGR of 15 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Hard seltzer Market Size 2024 | USD 21859.5Million |
| Hard seltzer Market, CAGR | 15 % |
| Hard seltzer Market Size 2032 | USD 66868.7 Million |
The market’s growth is fueled by multiple factors, including increasing awareness of wellness-driven lifestyles, the shift away from traditional beer and high-calorie cocktails, and innovative flavor launches. Hard seltzers appeal to consumers seeking convenience, moderation, and variety, with major alcohol companies investing heavily in product diversification and marketing. Seasonal and limited-edition flavors, eco-friendly packaging, and premium offerings are further enhancing market visibility and adoption.
Regionally, North America dominates the hard seltzer market, led by the United States where the category originated and continues to account for the highest consumption levels. Europe is experiencing steady adoption, particularly in markets with a strong demand for low-calorie alcoholic beverages. The Asia-Pacific region is emerging as a high-potential growth area, supported by urbanization, rising disposable incomes, and a growing interest in flavored ready-to-drink alcoholic beverages.
Market Insights:
- The hard seltzer market was valued at USD 21,859.5 million in 2024 and is projected to reach USD 66,868.7 million by 2032, driven by a CAGR of 15% during the forecast period.
- Rising consumer demand for low-calorie, low-sugar, and gluten-free beverages is positioning hard seltzers as preferred alternatives to traditional beer and cocktails.
- Innovation in flavor profiles, including tropical, botanical, and seasonal varieties, continues to expand consumer interest and attract younger demographics.
- Aggressive marketing strategies, celebrity endorsements, and strong social media presence strengthen brand visibility and boost adoption among millennials and Gen Z.
- North America dominates with 65% market share, while Europe accounts for 20% and Asia-Pacific with Latin America together contribute 15%, reflecting diverse regional adoption levels.
- Market challenges include saturation, high competition, regulatory pressures, and consumer fatigue, requiring brands to focus on differentiation and operational efficiency.
- Opportunities lie in premiumization, sustainable packaging, e-commerce expansion, and penetration into emerging markets, ensuring long-term growth momentum.
Market Drivers:
Rising Demand for Low-Calorie and Health-Conscious Alcoholic Beverages:
The hard seltzer market benefits significantly from a global shift toward healthier drinking alternatives. Consumers are actively seeking low-calorie, low-sugar, and gluten-free options that align with fitness-oriented lifestyles. It positions itself as a suitable substitute for traditional beer and high-calorie cocktails, offering a lighter and more refreshing experience. This health-driven preference continues to expand the consumer base and strengthen market penetration.
- For instance, Viva Tequila Seltzer has pioneered the use of premium blanco tequila as the alcohol base, creating a distinctive product with 88 calories and zero sugar that differentiates itself from traditional fermented sugar-based seltzers.
Innovation in Flavors and Product Diversification:
Continuous innovation in flavor profiles is a core driver of the hard seltzer market. Leading brands are introducing seasonal, tropical, and region-specific flavors to maintain consumer interest and cater to evolving taste preferences. It also includes premium product lines, botanical blends, and limited-edition releases that differentiate offerings in a competitive space. Such diversification not only attracts younger demographics but also broadens appeal across wider age groups.
- For instance, Topo Chico launched its Aguas Frescas Hard Seltzer line in 2023, featuring 4 unique flavors including Hibiscus Lime and Passionfruit Mango, achieving 100 calories per can while maintaining authentic aguas frescas-inspired taste profiles.
Strategic Marketing and Celebrity Endorsements:
Aggressive branding campaigns and endorsements play a critical role in accelerating demand within the hard seltzer market. Companies leverage social media, influencer marketing, and celebrity partnerships to build aspirational value and create strong brand recall. It resonates particularly well with millennials and Gen Z, who are highly responsive to lifestyle-driven marketing. These strategies continue to boost awareness and consumption across multiple distribution channels.
Expansion Across On-Trade and Off-Trade Channels:
The availability of hard seltzers across supermarkets, convenience stores, bars, and restaurants significantly supports growth. The hard seltzer market benefits from increased shelf space, attractive packaging, and strategic placements in retail outlets. It also leverages on-trade channels where experiential consumption and trial opportunities drive repeat purchases. This dual-channel expansion ensures strong accessibility and consistent growth momentum worldwide.
Market Trends:
Premiumization, Flavor Experimentation, and Functional Positioning:
The hard seltzer market is witnessing a strong trend toward premiumization, with brands introducing craft-inspired, botanical-infused, and exotic flavor combinations to differentiate their offerings. Consumers are gravitating toward unique blends such as tropical fruits, herbs, and floral notes that go beyond the traditional citrus base. It also reflects a growing preference for products that balance indulgence with perceived health benefits, leading to launches of low-carb and low-alcohol variants. Functional positioning is emerging, with some brands integrating electrolytes, vitamins, or natural energy boosters to capture wellness-focused audiences. Seasonal and limited-edition releases create excitement and encourage repeat purchases. This trend emphasizes brand innovation as a central growth lever across both developed and emerging markets.
- For instance, Truly Hard Seltzer has successfully expanded its flavor portfolio with over 30 distinct options, including tropical and botanical blends, reinforcing its reputation for innovation.
Sustainability, Packaging Innovation, and Global Expansion:
Sustainability has become a critical theme within the hard seltzer market, with companies adopting eco-friendly packaging formats, recyclable cans, and reduced carbon production processes. It aligns with rising consumer demand for environmentally responsible products while enhancing brand reputation. Packaging innovation also extends to sleek can designs and multipack options that appeal to convenience-driven buyers. Global expansion is accelerating, with leading brands entering Asia-Pacific and Latin America, where urban populations and rising disposable incomes fuel demand. Digital platforms and direct-to-consumer strategies strengthen international presence, allowing companies to engage new audiences effectively. These combined trends reinforce the market’s evolution from a regional phenomenon into a global lifestyle-oriented beverage category.
- For instance, Boston Beer Company's Truly Hard Seltzer reformulated its entire portfolio of 30 flavors using real fruit juice technology, contributing to improved taste profiles and sustained market competitiveness.
Market Challenges Analysis:
Market Saturation, Brand Differentiation, and Consumer Fatigue:
The hard seltzer market faces challenges from rapid saturation, with multiple global and regional brands competing for limited shelf space. Intense competition creates difficulty in sustaining consumer loyalty, as buyers often experiment with different flavors and labels. It also encounters consumer fatigue as novelty wears off and the category risks being perceived as a short-lived trend. Maintaining differentiation requires constant innovation, but frequent product launches increase operational costs and pressure on margins. Shifts in consumer attention toward alternative beverages such as ready-to-drink cocktails and flavored spirits further intensify the competitive landscape. These dynamics threaten long-term brand stability.
Regulatory Pressures, Distribution Hurdles, and Economic Sensitivity:
Strict regulations on alcohol labeling, advertising, and sugar content present significant hurdles for the hard seltzer market. It must navigate varying rules across regions, which complicates international expansion and delays product approvals. Distribution challenges persist in emerging economies where logistics and infrastructure limit accessibility. Rising raw material costs, particularly for natural flavors and aluminum cans, affect profitability and pricing strategies. Economic slowdowns or reduced disposable incomes can directly impact discretionary spending on premium beverages. These combined challenges require strategic adaptation to sustain growth momentum.
Market Opportunities:
Expansion into Emerging Markets and Untapped Consumer Segments:
The hard seltzer market holds strong opportunities in emerging regions such as Asia-Pacific and Latin America, where rising urbanization and disposable incomes drive demand for convenient alcoholic beverages. Young consumers in these markets are eager to adopt global lifestyle trends, making them prime targets for innovative marketing campaigns. It can leverage untapped demographics, including female drinkers and health-conscious consumers, who increasingly prefer low-calorie alternatives over traditional beer and spirits. Growth in e-commerce platforms also enhances accessibility, allowing brands to reach wider audiences. Localized flavors tailored to regional preferences further strengthen adoption and market penetration. This geographic and demographic expansion offers long-term growth potential.
Product Innovation, Functional Beverages, and Sustainability Advantage:
Innovation remains a central opportunity for the hard seltzer market, with growing scope for functional formulations that include natural energy boosters, vitamins, or adaptogens. It can expand into premium and craft-inspired segments that appeal to consumers seeking authenticity and exclusivity. Sustainable practices, such as eco-friendly packaging and carbon-neutral production, also create strong competitive differentiation. Collaborations with hospitality chains, music festivals, and sports events enable broader brand exposure and experiential engagement. The increasing demand for ready-to-drink cocktails and flavored beverages positions hard seltzers well to diversify and extend their category relevance. These opportunities ensure continued momentum and resilience against shifting consumer trends.
Market Segmentation Analysis:
By ABV Content
The hard seltzer market is segmented by alcohol by volume (ABV), typically ranging between 4% and 6%, with the 4.5% to 5% category holding the largest share due to its balance of lightness and refreshment. Consumers seeking moderation prefer this range, making it the most widely distributed segment. Higher ABV options between 6% and 8% are gaining traction among consumers who want stronger alternatives without shifting to traditional beer or spirits. It continues to diversify ABV ranges to appeal to both casual and premium segments.
- For instance, Bud Light Seltzer, produced by Anheuser-Busch, launched with a 5% ABV and rapidly achieved distribution in all 50 U.S. states in its launch year, reaching over 35,000 retail stores nationwide.
By Packaging Type
Packaging plays a central role in shaping consumer perception and convenience within the hard seltzer market. Cans dominate the segment, offering portability, recyclability, and wide retail acceptance. Sleek can designs and multipack formats drive strong adoption across both on-trade and off-trade channels. Bottled formats exist but represent a smaller share due to higher costs and reduced portability. It remains focused on eco-friendly and recyclable packaging innovations to align with sustainability goals.
- For instance, Ball Packaging Europe’s 330 ml ultra-light aluminium can weighs just under 9.5 grams per can, showcasing advanced lightweighting technology without compromising strength.
By Distribution Channel
The distribution of hard seltzers spans supermarkets, convenience stores, liquor shops, online platforms, bars, and restaurants. Off-trade channels dominate sales, with supermarkets and convenience stores providing wide accessibility and promotional visibility. On-trade channels, including restaurants, pubs, and events, are crucial for experiential consumption and new product trials. Online sales are expanding rapidly, particularly among younger demographics who value convenience and brand variety. It leverages multi-channel strategies to ensure broad market reach and consistent consumer engagement.
Segmentations:
By ABV Content:
- 1%–4.5% ABV
- 6%–6% ABV
- Above 6% ABV
By Packaging Type:
- Cans
- Bottles
- Others
By Distribution Channel:
- Supermarkets & Hypermarkets
- Convenience Stores
- Liquor Stores
- Online Retail
- Bars & Restaurants
- Others
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America :
North America holds 65% market share in the global hard seltzer market and continues to dominate as the category’s largest consumer region. The United States drives this leadership, supported by early adoption, aggressive brand marketing, and wide product availability across retail and on-trade channels. It benefits from a strong millennial and Gen Z consumer base that prioritizes low-calorie and convenient beverage formats. Seasonal launches, premium variants, and celebrity endorsements further fuel demand and brand loyalty. Canada also contributes steadily, with rising adoption in urban centers where wellness-oriented alcohol consumption is gaining traction. The mature retail infrastructure across the region strengthens product visibility and accessibility.
Europe :
Europe accounts for 20% market share in the global hard seltzer market, supported by increasing consumer preference for lighter alcoholic beverages. The region benefits from strong traditions in beer and wine but is gradually embracing hard seltzers as an alternative choice, particularly among younger demographics. It has seen growth through flavor innovation, craft positioning, and sustainability-focused packaging, which align with European consumer values. Key markets such as the United Kingdom, Germany, and France are expanding distribution across supermarkets and specialty outlets. Rising demand for low-sugar beverages is accelerating brand entry and collaborations with hospitality sectors. The trend of premium and artisanal drinks further supports category growth across the continent.
Asia-Pacific and Latin America :
Asia-Pacific and Latin America together contribute 15% market share in the global hard seltzer market, but both regions hold significant long-term growth potential. Urbanization, rising disposable incomes, and cultural shifts toward global lifestyle beverages are fueling adoption. It gains traction among young consumers in countries such as Japan, China, India, Brazil, and Mexico, where awareness of low-calorie alcohol alternatives is increasing. Localized flavors inspired by tropical fruits and spices create strong consumer appeal. E-commerce expansion and partnerships with local distributors enhance product reach and awareness. Growing investments from international and regional players are expected to establish these markets as key contributors to future industry expansion.
Key Player Analysis:
- Mark Anthony Brands International
- Anheuser-Busch InBev
- Carlsberg Group
- The Coca-Cola Company
- Heineken N.V.
- Diageo plc
- San Juan Seltzer, Inc.
- The Boston Beer Company
- Constellation Brands, Inc.
- Molson Coors Beverage Company
- Kopparberg
Competitive Analysis:
The hard seltzer market is highly competitive, driven by strong global and regional players investing heavily in product innovation and marketing strategies. Key participants include Mark Anthony Brands International, Anheuser-Busch InBev, Carlsberg Group, The Coca-Cola Company, Heineken N.V., Diageo plc, and San Juan Seltzer, Inc. It reflects a mix of multinational beverage giants leveraging scale and distribution strength alongside niche producers targeting local markets with unique flavors. Mark Anthony Brands leads with White Claw, while Anheuser-Busch and Heineken capitalize on established retail networks to expand reach. Coca-Cola and Diageo are entering through brand diversification and premium positioning to capture health-conscious consumers. Carlsberg and regional brands strengthen presence with localized offerings and craft-inspired variations. It remains characterized by aggressive flavor innovation, eco-friendly packaging, and celebrity-driven marketing, making brand differentiation critical for sustaining market share in an increasingly crowded space.
Recent Developments:
- In August 2025, Carlsberg Group signed a multi-year partnership with UEFA to become the Official Beer of UEFA National Team Football.
- In July 2025, The Coca-Cola Company announced the launch of a new version of its signature beverage made with U.S. cane sugar, scheduled for release in the United States later in the fall.
- In August 2025, The Boston Beer Company announced a leadership change as Jim Koch returned as CEO, following Michael Spillane’s resignation after a strong second quarter performance.
Market Concentration & Characteristics:
The hard seltzer market displays moderate to high concentration, with leading players such as White Claw, Truly Hard Seltzer, Bud Light Seltzer, and Corona Hard Seltzer capturing significant global revenue share. It is characterized by strong brand-driven competition, rapid flavor innovation, and heavy marketing investments that create differentiation in a crowded space. Regional and craft producers are also entering the category with niche offerings, but large multinational beverage companies maintain dominance through scale and distribution strength. The market reflects fast-changing consumer preferences, where health-conscious choices, premium positioning, and sustainability practices define brand competitiveness. This balance of global leadership and localized innovation shapes the industry’s dynamic growth trajectory.
Report Coverage:
The research report offers an in-depth analysis based on ABV Content, Packaging Type, Distribution Channel and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The hard seltzer market will continue expanding as consumers increasingly prioritize healthier alcoholic beverage choices.
- Innovation in flavors, including exotic, botanical, and functional blends, will remain a primary growth driver.
- Premiumization will strengthen, with craft-inspired and limited-edition variants attracting affluent and experience-driven consumers.
- Sustainability initiatives such as recyclable packaging and carbon-neutral production will enhance brand reputation and consumer loyalty.
- E-commerce and direct-to-consumer platforms will play a larger role in distribution, particularly among younger demographics.
- On-trade channels such as bars, restaurants, and festivals will boost visibility and encourage experiential consumption.
- Expansion into emerging regions such as Asia-Pacific and Latin America will create significant opportunities for international and local brands.
- Strategic collaborations with lifestyle, sports, and entertainment sectors will support stronger consumer engagement.
- Intense competition from ready-to-drink cocktails and flavored spirits will push brands to differentiate through innovation and marketing.
- The market will evolve into a broader lifestyle category, reinforcing its position as a mainstream alternative to beer and traditional alcoholic beverages.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Health-Conscious Consumer Preferences
A growing focus on wellness and fitness is driving consumers to seek low-calorie, low-sugar, and gluten-free alcoholic beverages, positioning hard seltzers as a preferred alternative to traditional beer and high-calorie cocktails.
Flavor Innovation and Product Diversification
Continuous introduction of new, seasonal, and region-specific flavors, along with premium and botanical-infused variants, keeps consumer interest high and attracts younger demographics seeking variety and novelty.
Aggressive Marketing and Celebrity Endorsements
Major brands leverage social media, influencer partnerships, and celebrity endorsements to build aspirational value and strong brand recall, particularly among millennials and Gen Z, boosting adoption and category visibility.
Convenient and Sustainable Packaging
The dominance of portable, recyclable cans and the adoption of eco-friendly packaging solutions align with consumer demand for convenience and sustainability, enhancing product appeal and supporting retail expansion.
Expansion Across Multiple Distribution Channels
Widespread availability in supermarkets, convenience stores, bars, restaurants, and online platforms ensures strong accessibility, while on-trade channels encourage experiential consumption and repeat purchases.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the hard seltzer market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the hard seltzer market projected to grow between 2024 and 2032?
Which hard seltzer market segment held the largest share in 2024?
What are the primary factors fueling the growth of the hard seltzer market?
Who are the leading companies in the hard seltzer market?
Which region commanded the largest share of the hard seltzer market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By ABV Content
- 1.2.1 1%–4.5% ABV
- 1.2.2 4.5%–6% ABV
- 1.2.3 Above 6% ABV
- 1.3 By Packaging Type
- 1.3.1 Cans
- 1.3.2 Bottles
- 1.3.3 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 21,859.5 million → 2032: USD 66,868.7 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Hard Seltzer Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Hard Seltzer Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Hard Seltzer Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Hard Seltzer Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Hard Seltzer Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Hard Seltzer Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Hard Seltzer Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Hard Seltzer Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 21,859.5 million → 2032: USD 66,868.7 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Hard Seltzer Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By ABV Content - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 1%–4.5% ABV
- 12.3.7.2 4.5%–6% ABV
- 12.3.7.3 Above 6% ABV
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Packaging Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Cans
- 12.4.7.2 Bottles
- 12.4.7.3 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Hard Seltzer Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Hard Seltzer Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Hard Seltzer Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Mark Anthony Brands International
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Anheuser-Busch InBev
- 17.4 Carlsberg Group
- 17.5 The Coca-Cola Company
- 17.6 Heineken N.V.
- 17.7 Diageo plc
- 17.8 San Juan Seltzer, Inc.
- 17.9 The Boston Beer Company
- 17.10 Constellation Brands, Inc.
- 17.11 Molson Coors Beverage Company
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

