
Market Overview
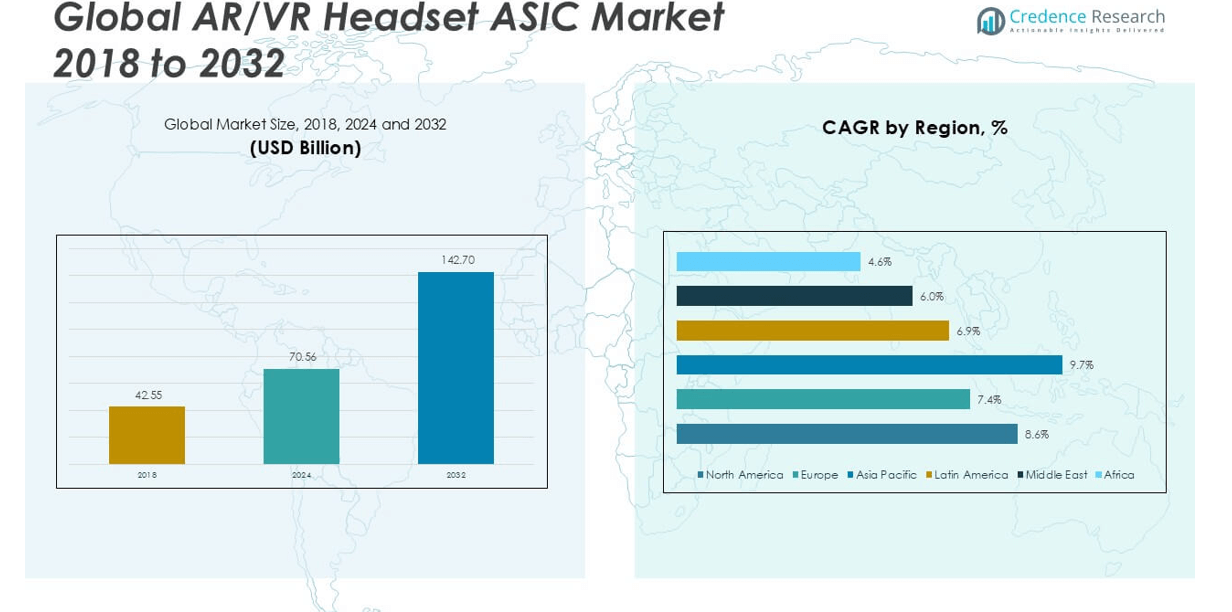
The AR/VR Headset ASIC market size was valued at USD 42.55 billion in 2018, increased to USD 70.56 billion in 2024, and is anticipated to reach USD 142.70 billion by 2032, growing at a CAGR of 8.57% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| AR/VR Headset ASIC Market Size 2024 | USD 70.56 billion |
| AR/VR Headset ASIC Market, CAGR | 8.57% |
| AR/VR Headset ASIC Market Size 2032 | USD 142.70 billion |
The AR/VR Headset ASIC market is led by top players such as Sony Group Corporation, Meta, Apple Inc., Samsung, HTC Corporation, Microsoft, Lenovo, Seiko Epson Corporation, Panasonic Corporation, Nvidia, Qualcomm, and Intel Corporation. These companies are driving innovation through custom ASIC development to support high-performance, low-latency experiences across consumer and enterprise applications. North America emerged as the leading region in 2024, holding the highest market share of 41.4%, driven by strong technological infrastructure, early adoption, and significant investments in immersive technology. The region continues to benefit from a robust semiconductor ecosystem and the presence of major AR/VR developers and manufacturers.
Market Insights
- The AR/VR Headset ASIC market was valued at USD 70.56 billion in 2024 and is projected to reach USD 142.70 billion by 2032, growing at a CAGR of 8.57% during the forecast period.
- Increasing demand for immersive experiences in gaming, healthcare, and training applications is fueling the adoption of advanced ASICs in AR/VR headsets.
- Integration of AI and edge processing capabilities within ASICs is a key trend, enabling improved performance, real-time tracking, and lower latency across devices.
- North America held the largest regional share in 2024 at 41.4%, followed by Asia Pacific at 31.0%; by device type, VR headsets accounted for the dominant share due to widespread use in consumer entertainment.
- High development costs, thermal management challenges, and lack of standardization across platforms continue to restrain broader market adoption, especially for emerging players.
Market Segmentation Analysis:
By Device Type
The AR/VR Headset ASIC market, segmented by device type, is dominated by VR headsets, which accounted for the largest market share in 2024. VR headsets are widely adopted in gaming and simulation applications due to their immersive capabilities and mature hardware ecosystem. The increasing affordability of standalone VR headsets and integration of high-performance ASICs that enable smooth graphics rendering have contributed to their dominance. AR headsets are gaining momentum in enterprise and industrial applications, while mixed reality headsets are emerging with growth potential driven by advancements in real-time 3D spatial computing.
- For instance, Sony’s PlayStation VR2, launched with custom AMD ASICs, delivers 4K HDR visuals at 2000x2040 resolution per eye, supporting advanced eye tracking and adaptive rendering.
By Component
Among the component segments, ASICs (Application-Specific Integrated Circuits) hold the dominant market share due to their critical role in enhancing processing efficiency for graphics rendering, AI workloads, and sensor fusion. The demand for high-performance, low-power chips has grown significantly with the increasing complexity of AR/VR applications. Custom-designed ASICs enable faster computation, reduced latency, and improved battery life—key factors in optimizing the user experience. Displays and sensors also contribute substantially to the market, driven by the need for high-resolution visuals and accurate spatial tracking in both consumer and enterprise applications.
- For instance, Qualcomm’s Snapdragon XR2 Gen 2 platform integrates an AI engine capable of 15 TOPS (trillions of operations per second) to support 3Kx3K per eye displays at 90fps with ultra-low latency processing.
By Application
The gaming and entertainment segment leads the AR/VR Headset ASIC market by application, commanding the highest market share in 2024. This dominance is attributed to the strong consumer demand for immersive gaming experiences and interactive media, coupled with the widespread adoption of VR gaming platforms. ASICs tailored for high-refresh-rate graphics and low-latency interaction enhance user engagement. Other segments like healthcare and education are witnessing rapid adoption due to their growing use in surgical simulation, remote training, and virtual classrooms, while industrial and retail applications benefit from improved visualization and real-time data overlays.
Market Overview
Rising Demand for Immersive Consumer Experiences
The increasing consumer demand for immersive experiences in gaming, entertainment, and social interaction is a major growth driver for the AR/VR Headset ASIC market. Advanced ASICs enable low-latency, high-resolution graphics rendering, crucial for enhancing realism in virtual environments. As consumer electronics brands invest heavily in VR ecosystems, the adoption of specialized ASICs has surged to support complex tasks such as real-time motion tracking and 3D rendering. This demand is further amplified by the growing popularity of virtual concerts, esports, and metaverse platforms, all of which rely on high-performance AR/VR headsets.
- For instance, Meta’s Quest 3 uses a custom Qualcomm XR2 Gen 2 chip to achieve 2.5 times the graphical performance of its predecessor, enabling lifelike rendering and 3D spatial interaction.
Technological Advancements in ASIC Design
Rapid innovations in ASIC architecture—such as edge AI integration, power efficiency, and miniaturization—are accelerating the market’s growth. These enhancements enable headsets to handle more complex computations locally, reducing the dependency on external hardware or cloud processing. The inclusion of sensor fusion capabilities within ASICs also improves tracking accuracy and interaction responsiveness. As semiconductor technology progresses, ASICs are becoming more affordable and accessible, allowing OEMs to develop lighter, more powerful AR/VR headsets suited for both consumer and enterprise use cases, ranging from training simulations to remote assistance.
- For instance, Apple’s custom-designed R1 chip in the Vision Pro processes input from 12 cameras, 6 microphones, and 5 sensors every 12 milliseconds, ensuring near-instantaneous responsiveness.
Expanding Applications Across Industry Verticals
The expanding utility of AR/VR technologies across healthcare, education, industrial training, and retail has significantly boosted the demand for specialized ASICs. In healthcare, AR/VR headsets powered by optimized ASICs support applications like surgical planning and therapy. In manufacturing, they enable hands-free training and maintenance with real-time overlays. Education sectors are leveraging immersive learning tools for interactive instruction, especially in STEM fields. The versatility of ASICs in catering to diverse application requirements ensures that the market continues to grow beyond the consumer space, opening avenues for long-term industrial adoption.
Key Trends & Opportunities
Integration of AI and Edge Processing Capabilities
One of the key trends shaping the AR/VR Headset ASIC market is the integration of AI processing directly into ASICs. This allows devices to support intelligent behavior such as real-time scene recognition, adaptive rendering, and predictive motion tracking without relying on external processing units. AI-enabled ASICs offer significant performance improvements while reducing latency, which is crucial for delivering seamless user experiences. As edge AI gains momentum, the opportunity to deploy smarter, more autonomous headsets in sectors like healthcare diagnostics, education personalization, and industrial automation is expected to grow.
- For instance, Nvidia’s Jetson Orin Nano, used in AR/VR development kits, supports 40 TOPS AI performance, enabling real-time object detection and spatial awareness in low-latency environments.
Growing Investments in the Metaverse Ecosystem
The rising investment in metaverse development by major tech players is creating new opportunities for the AR/VR Headset ASIC market. As the metaverse evolves, the need for high-performance, low-power, and compact processing units becomes essential for supporting persistent virtual environments and complex interactions. ASICs tailored for AR/VR headsets will play a critical role in enabling immersive digital platforms where users can work, socialize, and engage in commerce. This trend opens avenues for innovation in ASIC design, focusing on scalability, thermal management, and integration with advanced networking technologies.
- For instance, Qualcomm’s Snapdragon XR2+ Gen 2 supports 4.3K resolution per eye at 90 Hz and can integrate up to 12 concurrent cameras with sub-12 ms passthrough latency—targeting Samsung and Google’s future MR headsets.
Key Challenges
High Development and Manufacturing Costs
Developing advanced ASICs for AR/VR headsets involves significant R&D investment, specialized design tools, and manufacturing processes. These high upfront costs can pose barriers to entry for smaller companies and limit widespread innovation. Additionally, ASICs must be tailored to specific performance needs, making economies of scale difficult to achieve without large production volumes. For many manufacturers, the trade-off between performance optimization and cost efficiency remains a critical challenge, impacting pricing strategies and delaying time-to-market for new headset models.
Thermal Management and Power Efficiency Constraints
One of the major technical challenges in AR/VR headset ASIC design is managing heat dissipation and maintaining power efficiency in compact form factors. As processing demands increase, especially with the addition of AI and 3D rendering capabilities, the risk of overheating becomes significant. Ensuring reliable thermal performance without compromising user comfort or battery life remains a complex engineering hurdle. Poor thermal regulation can lead to throttled performance, reduced device lifespan, and negative user experiences, thus affecting overall product adoption in both consumer and professional markets.
Limited Standardization Across Platforms
The AR/VR ecosystem is still fragmented, with various hardware and software platforms lacking common standards. This lack of interoperability creates challenges for ASIC developers who must design chips compatible with multiple architectures and interfaces. Without a unified framework, scalability becomes difficult, and development cycles are extended due to the need for customization. This also increases integration complexity for headset manufacturers and can delay adoption in enterprise environments where compatibility and long-term support are essential. Standardization will be key to overcoming this challenge and enabling faster market growth.
Regional Analysis
North America
North America dominated the AR/VR Headset ASIC market in 2024 with the highest regional market share of approximately 41.4%, valued at USD 29.19 billion, up from USD 17.79 billion in 2018. The region is projected to reach USD 59.21 billion by 2032, growing at a CAGR of 8.6%. This growth is fueled by strong consumer demand for immersive gaming, well-established tech infrastructure, and early adoption of advanced ASIC designs by leading companies. High R&D investments, presence of major semiconductor players, and growing applications in healthcare and education further support the region's market leadership.
Europe
Europe accounted for around 19.4% of the global AR/VR Headset ASIC market in 2024, with its value rising from USD 8.70 billion in 2018 to USD 13.70 billion. The market is expected to reach USD 25.43 billion by 2032, expanding at a CAGR of 7.4%. The region’s growth is driven by increasing use of AR/VR headsets in industrial design, automotive simulation, and healthcare applications. EU-backed initiatives promoting immersive technologies and growing investments in educational tools leveraging AR/VR also contribute to the demand for high-performance ASICs tailored for these devices.
Asia Pacific
Asia Pacific held a market share of approximately 31.0% in 2024, with a value of USD 21.85 billion, up from USD 12.49 billion in 2018. It is projected to reach USD 48.14 billion by 2032, making it the fastest-growing region with a CAGR of 9.7%. This robust growth is driven by high consumer adoption in countries like China, Japan, and South Korea, along with strong manufacturing capabilities and rising tech investments. The region benefits from the presence of several semiconductor fabrication hubs and rapid integration of AR/VR solutions in retail, training, and mobile gaming sectors.
Latin America
Latin America represented a modest 4.6% share of the global AR/VR Headset ASIC market in 2024, growing from USD 1.97 billion in 2018 to USD 3.23 billion. The market is expected to reach USD 5.76 billion by 2032, with a CAGR of 6.9%. Growth in this region is driven by expanding access to digital technologies and increased demand for affordable VR solutions in education and entertainment. Governments and private institutions are gradually adopting immersive technologies to enhance learning and employee training, creating opportunities for ASIC providers focused on cost-efficient, low-power processing units.
Middle East
The Middle East accounted for about 2.3% of the AR/VR Headset ASIC market in 2024, with the market size rising from USD 1.07 billion in 2018 to USD 1.61 billion. It is projected to reach USD 2.69 billion by 2032, growing at a CAGR of 6.0%. Regional growth is supported by smart city projects, digital transformation in sectors like retail and tourism, and a growing focus on experiential marketing. The increasing adoption of AR/VR in luxury retail and hospitality is creating demand for customized ASICs that can deliver high-performance, immersive user experiences in compact form factors.
Africa
Africa held the smallest share of the global AR/VR Headset ASIC market in 2024, contributing just 1.4%, with a market value increasing from USD 0.52 billion in 2018 to USD 0.97 billion. It is expected to reach USD 1.47 billion by 2032, reflecting a CAGR of 4.6%. Market growth is relatively slow due to limited infrastructure and lower access to advanced AR/VR technologies. However, increasing efforts in digital education, low-cost headset availability, and growing mobile internet penetration are gradually encouraging adoption. ASIC providers targeting entry-level solutions may find emerging opportunities in localized AR/VR deployments for training and education.
Market Segmentations:
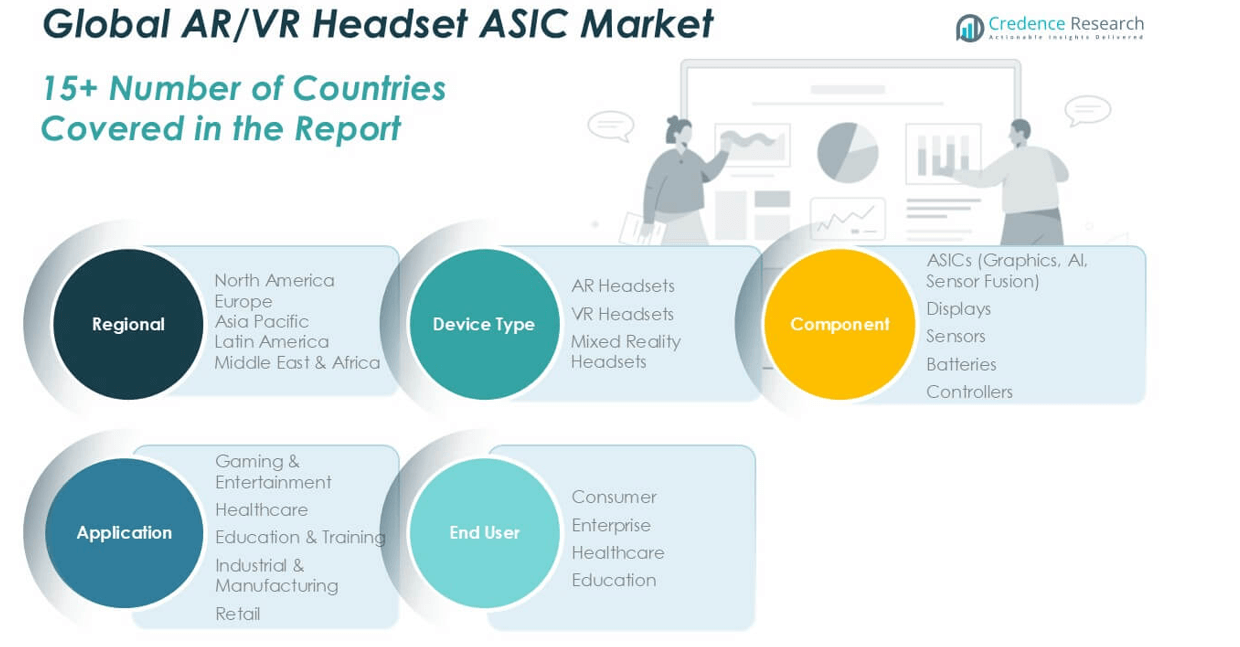
By Device Type
- AR Headsets
- VR Headsets
- Mixed Reality Headsets
By Component
- ASICs (Graphics, AI, Sensor Fusion)
- Displays
- Sensors
- Batteries
- Controllers
By Application
- Gaming & Entertainment
- Healthcare
- Education & Training
- Industrial & Manufacturing
- Retail
By End User
- Consumer
- Enterprise
- Healthcare
- Education
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The AR/VR Headset ASIC market features a competitive landscape characterized by a mix of established semiconductor companies, consumer electronics giants, and specialized AR/VR technology providers. Key players such as Sony Group Corporation, Meta, Apple Inc., Samsung, HTC Corporation, and Microsoft are actively investing in proprietary ASIC development to enhance performance and reduce power consumption in their respective headset offerings. Semiconductor firms like Nvidia, Qualcomm, and Intel continue to innovate in AI-integrated and sensor-fusion chipsets, targeting both high-end and mainstream markets. Collaborations between hardware manufacturers and ASIC developers are becoming increasingly common, aiming to accelerate product development cycles and deliver tailored computing capabilities. Startups and niche providers are also entering the space with application-specific innovations, particularly in areas like lightweight wearables and edge AI processing. Continuous R&D, strategic partnerships, and acquisitions remain key strategies as companies vie
Key Player Analysis
- Sony Group Corporation
- Meta
- Apple Inc.
- Samsung
- HTC Corporation
- Microsoft
- Lenovo
- Seiko Epson Corporation
- Panasonic Corporation
- Nvidia
- Qualcomm
- Intel Corporation
Recent Developments
- In April 2025, Apple Vision Air announced the launch of a lighter and cheaper version of the AR/VR Headset. To compute mainstream mainly for Indian Tech customers, due to the rise in demand and excitement among a certain group, the company is aiming to attract most of the population with its low-cost, effective strategy.
- In August 2024, Microsoft announced its plans to launch a mixed-reality headset to compete with its rival Apple. With the partnership at its early stage between Microsoft and Samsung, the company might increase its production capacity.
- In June, 2024, Apple Inc. launched vision OS 2 which provided new spatial computing experiences to Vision Pro. Through this the user can turn their photos into spatial photos, gestures for navigating visionOS and many more ways to take advantage of spatial computing. In June 2024, Google formed a collaboration with the artist Grand Palais Immersif’s recent exhibition “Loading: Urban Art in the Digital Age Exhibition” which is an immersive exhibition that portrays the history of urban art and sheds light on the impact of digital technologies. In May 2024, Alo Moves and Meta formed a partnership that will features 3D classes for a new level of immersion. Under this partnership, Alo Moves will utilize Meta Quest 3 in the same rooms as the instructors for classes spanning yoga, Pilates and meditation.
- In April 2024, Meta. And EssilorLuxottica formed a partnership to produce second-generation smart glasses which expands the Ray-Ban Meta smart glasses collection. It includes additional features such as updates to Meta AI that will make the glasses more useful. In January 2024, Sony Group Corporation developed an immersive spatial content creation system which includes XR HMD which delivers high quality 4K OLED microdisplays, video see through functions and a pair of controllers that are used for intuitive interaction with 3D objects and precise pointing.
Market Concentration & Characteristics
The AR/VR Headset ASIC Market exhibits a moderately concentrated structure, dominated by a few key players with strong technological capabilities and significant R&D investments. Companies such as Sony, Meta, Apple, and Nvidia hold substantial market influence due to proprietary chip designs and integration into in-house headset platforms. It features high barriers to entry driven by complex design requirements, high development costs, and the need for advanced manufacturing infrastructure. The market prioritizes performance efficiency, low power consumption, and seamless integration with sensors and displays. Demand is concentrated in consumer electronics, healthcare, and industrial training applications. It continues to shift toward customized ASICs that support real-time graphics rendering and AI-driven functionalities. The presence of a few vertically integrated firms enables them to control both hardware and software stacks, reinforcing their market position. Regional concentration is strong in North America and Asia Pacific, where leading semiconductor manufacturers and AR/VR device producers operate with advanced production capabilities
Report Coverage
The research report offers an in-depth analysis based on Device Type, Component, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will witness steady growth driven by increasing adoption of AR/VR technologies across consumer and enterprise applications.
- Demand for customized ASICs will rise as device manufacturers seek performance optimization and power efficiency.
- AI integration in ASICs will become standard, enabling smarter real-time user interactions and adaptive environments.
- Mixed reality headsets will gain traction, expanding beyond niche applications into mainstream enterprise use.
- Asia Pacific is expected to emerge as the fastest-growing region due to rising manufacturing capabilities and consumer demand.
- Continued investment in the metaverse ecosystem will create new opportunities for high-performance AR/VR ASICs.
- ASICs supporting edge computing will see higher adoption to reduce latency and dependency on external hardware.
- Miniaturization of chipsets will enable the development of lighter, more ergonomic headsets.
- Strategic collaborations between semiconductor firms and headset manufacturers will accelerate innovation cycles.
- Market players will increasingly focus on thermal efficiency and cross-platform compatibility in future ASIC designs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the AR/VR Headset ASIC Market?
What factors are driving the growth of the AR/VR Headset ASIC Market?
What are some challenges faced by the AR/VR Headset ASIC Market?
Who are the major players in the AR/VR Headset ASIC Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 AR/VR Headset ASIC Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global AR/VR Headset ASIC Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 70.56 billion → forecast year: USD 142.70 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 AR/VR Headset ASIC Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. AR/VR Headset ASIC Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 AR/VR Headset ASIC Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 AR/VR Headset ASIC Market Drivers
- 3.3 AR/VR Headset ASIC Market Restraints & Challenges
- 3.4 AR/VR Headset ASIC Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 AR/VR Headset ASIC Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 AR/VR Headset ASIC Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, AR/VR Headset ASIC category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 AR/VR Headset ASIC Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. AR/VR Headset ASIC Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the AR/VR Headset ASIC market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 AR/VR Headset ASIC Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 AR/VR Headset ASIC Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 AR/VR Headset ASIC Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in AR/VR Headset ASIC (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New AR/VR Headset ASIC Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global AR/VR Headset ASIC Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America AR/VR Headset ASIC Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe AR/VR Headset ASIC Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific AR/VR Headset ASIC Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America AR/VR Headset ASIC Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East AR/VR Headset ASIC Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa AR/VR Headset ASIC Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. AR/VR Headset ASIC Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
