
Artificial Intelligence In Pharmaceutical Market Overview:
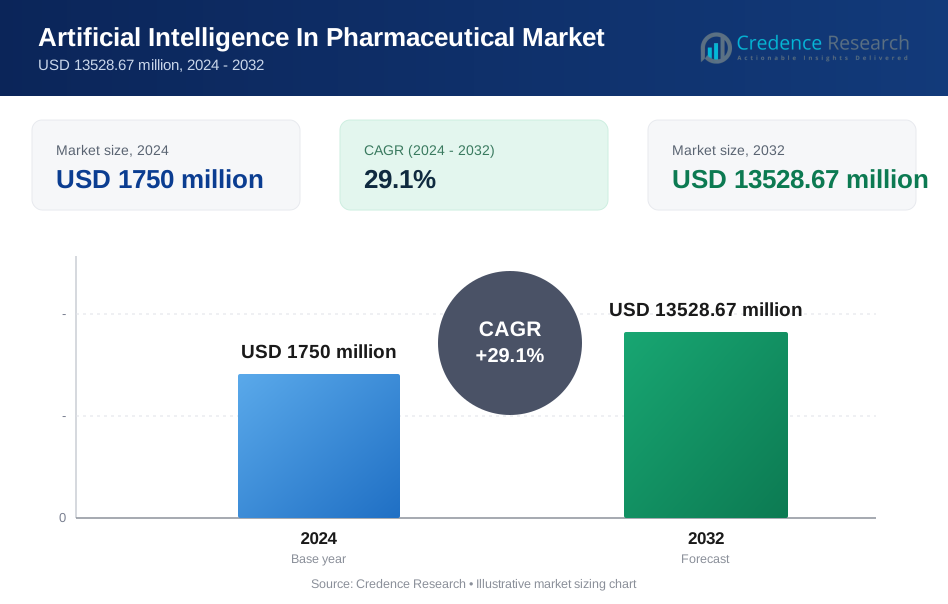
The Artificial Intelligence In Pharmaceutical Market is projected to grow from USD 1750 million in 2024 to an estimated USD 13528.67 million by 2032, with a compound annual growth rate (CAGR) of 29.1% from 2024 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Artificial Intelligence In Pharmaceutical Market Size 2024 | USD 1750 million |
| Artificial Intelligence In Pharmaceutical Market, CAGR | 29.1% |
| Artificial Intelligence In Pharmaceutical Market Size 2032 | USD 13528.67 million |
Strong market drivers include the need to shorten development timelines, improve patient selection, and reduce trial failures. Companies deploy AI to refine molecular design, predict disease behavior, and enhance biomarker discovery. Early research stages benefit from algorithms that reduce manual processing and improve candidate selection accuracy. Clinical teams apply AI to enhance protocol design and risk monitoring. Demand for precision medicine reinforces deeper integration of genomic and clinical insights. Manufacturing teams adopt predictive tools to stabilize quality and reduce disruptions. These factors collectively reinforce sustained adoption across the pharmaceutical lifecycle.
North America leads due to strong digital maturity, early adoption by major pharmaceutical companies, and extensive AI research ecosystems. Europe expands through regulatory support, academic–industry collaboration, and growing focus on ethical AI deployment. Asia Pacific emerges as the fastest-growing region driven by expanding pharmaceutical manufacturing, rising clinical trial activity, and government investment in AI infrastructure. Countries like China, Japan, and India integrate AI into discovery, diagnostics, and trial operations to improve efficiency and competitiveness. Other regions strengthen adoption through modernization efforts and broader acceptance of data-driven healthcare innovation.

Artificial Intelligence In Pharmaceutical Market Insights:
- The Artificial Intelligence In Pharmaceutical Market is projected to grow from USD 1750 million in 2024 to USD 13528.67 million by 2032, supported by a 29.1% CAGR driven by rapid digital transformation.
- Strong market growth comes from rising demand for faster discovery cycles, improved patient selection, advanced biomarker identification, and AI-enabled precision workflows across major pharma pipelines.
- Key restraints include data fragmentation, limited interoperability, strict validation requirements, and shortages of specialized AI talent that slow seamless deployment.
- North America leads the market with the highest share due to strong infrastructure and early adoption, while Europe maintains steady uptake through supportive regulatory frameworks and innovation hubs.
- Asia Pacific remains the fastest-growing region with expanding manufacturing bases, rising clinical trial activity, and increasing investment in AI-enabled pharmaceutical research.
Artificial Intelligence In Pharmaceutical Market Drivers
Rising Demand for Faster and More Predictive Drug Discovery Processes
The Artificial Intelligence In Pharmaceutical Market grows due to strong demand for tools that cut discovery timelines. Companies deploy AI models to screen compounds with higher precision. Research teams value platforms that reduce late-stage failures. It improves selection accuracy for viable drug candidates. Firms use data-driven insights to guide early-stage research. Predictive algorithms reduce manual screening work. Automated pattern analysis supports better molecule behavior prediction. Strong R&D pressure pushes leaders to adopt scalable AI tools.
- For instance, Exscientia reported an 80% reduction in candidate selection time in its AI-driven discovery programs.
Growing Adoption of AI to Improve Clinical Trial Efficiency and Patient Outcomes
Clinical teams rely on AI models to reduce costly trial delays. The Artificial Intelligence In Pharmaceutical Market gains momentum when firms use algorithms to improve patient selection. It improves trial quality with accurate stratification. Sponsors apply real-world evidence to adjust protocols. AI reduces monitoring errors by highlighting deviations early. Strong interest in adaptive trial design drives adoption. Predictive risk systems support better oversight. Higher trial complexity strengthens the need for advanced automation.
- For instance, Flatiron Health’s oncology datasets supported protocol optimization across more than 3,000 active clinical programs.
Expanding Use of AI for Precision Medicine and Targeted Therapy Development
AI tools support deeper understanding of disease pathways. The Artificial Intelligence In Pharmaceutical Market benefits from strong demand for targeted therapies. It improves identification of biomarkers that guide treatment choices. Companies use multi-omics data to refine disease models. Predictive engines help identify patient subgroups. Better diagnostic insights push personalized treatment plans. Research teams value algorithms that enhance therapy accuracy. Strong focus on precision medicine accelerates new development pipelines.
Increasing Integration of Automation Across Pharmaceutical Manufacturing Environments
Automation drives strong interest in AI-enabled operations. The Artificial Intelligence In Pharmaceutical Market gains support from companies seeking improved manufacturing stability. It helps optimize batch quality with real-time insights. Predictive maintenance reduces downtime. Firms apply AI to forecast supply disruptions. Quality-control teams monitor patterns to identify risks. Automated inspection improves production reliability. Growing pressure for consistent output strengthens industry uptake.
Artificial Intelligence In Pharmaceutical Market Trends
Rapid Expansion of Generative AI Models for Early Drug Design and Molecular Innovation
Generative AI shapes new capabilities across research labs. The Artificial Intelligence In Pharmaceutical Market sees rising interest in models that create novel structures. It allows firms to test designs virtually before synthesis. Teams explore pathways that were previously overlooked. Faster ideation shortens discovery programs. Generative tools support more efficient library creation. Predictive scoring filters weak candidates early. Strong gains in model accuracy push wider industry trials.
- For instance, Atomwise’s AtomNet platform evaluated over 16 billion structures to identify high-potential hits for global pharma partners.
Growing Use of Multimodal AI Platforms Integrating Genomic, Imaging, and Clinical Data
Multimodal systems gain traction across pharma pipelines. The Artificial Intelligence In Pharmaceutical Market expands when firms merge multiple data streams under one workflow. It helps research teams uncover deeper biological links. High-value insights emerge from richer datasets. Clinical teams improve classification accuracy. Genomic pairing with imaging improves diagnostic confidence. Unified dashboards give teams faster access to results. Rapid adoption supports broader cross-functional collaboration.
Increased Adoption of AI-Driven Automation Tools in Regulatory Documentation and Submission Workflows
AI supports heavy documentation workloads across regulatory units. The Artificial Intelligence In Pharmaceutical Market benefits from tools that reduce manual drafting pressure. It helps teams prepare submissions with higher consistency. Automated language models highlight errors early. Document screening improves compliance alignment. Teams cut preparation time with structured templates. Predictive engines guide data selection for required formats. Rising document volume strengthens the push toward AI-enabled automation.
Rising Industry Movement Toward AI-Augmented Decision Support Systems Across R&D and Commercial Planning
AI-driven decision systems reshape strategic planning. The Artificial Intelligence In Pharmaceutical Market advances when leaders apply predictive dashboards. It reveals gaps in R&D portfolios. Real-time scoring supports better investment choices. Commercial units use insights to refine launch plans. Cross-functional teams align on risks faster. Data-fed algorithms reduce subjective bias. Growing interest in evidence-backed forecasting enhances adoption.
- For instance, IQVIA’s AI-driven Orchestrated Analytics platform improved forecasting accuracy for leading pharma clients by double-digit percentages.
Artificial Intelligence In Pharmaceutical Market Challenges Analysis
High Data Complexity, Limited Interoperability, and Strong Need for Robust Validation Frameworks
Data fragmentation creates major hurdles for research teams. The Artificial Intelligence In Pharmaceutical Market faces issues when datasets lack standard formats. It becomes difficult to merge genomic, clinical, and molecular inputs. Firms struggle with incomplete patient profiles. Validation needs increase pressure on development teams. Strict quality checks slow deployments. Data privacy rules limit access to sensitive information. Limited interoperability across legacy systems delays full integration.
Shortage of Specialized Talent and Rising Concerns Around Model Transparency and Ethical Deployment
AI adoption requires advanced technical expertise across research and clinical units. The Artificial Intelligence In Pharmaceutical Market encounters resistance when teams cannot interpret AI outputs. It raises concerns about transparency in decision pathways. Ethical questions arise in high-impact clinical settings. Model bias risks limit trust among regulators. Skilled personnel remain in short supply. Training programs require long timelines. Talent gaps restrict wider adoption across many firms.
Artificial Intelligence In Pharmaceutical Market Opportunities
Emergence of AI-First Drug Development Models and Strong Growth in Collaborative Research Ecosystems AI-native pipelines open new commercial paths for innovators. The Artificial Intelligence In Pharmaceutical Market gains opportunities as firms shift toward agile discovery models. It supports lower-cost exploration of rare diseases. Strategic partnerships between pharma and tech firms create rapid innovation cycles. Shared datasets broaden insight depth. Faster prototyping brings more candidates into testing. Global hubs invest in AI labs. These factors expand growth across both early and advanced pipelines.
Expansion of AI Applications in Real-World Evidence, Digital Biomarkers, and Post-Market Safety Optimization Real-world evidence platforms unlock new use cases for AI. The Artificial Intelligence In Pharmaceutical Market benefits from stronger safety monitoring tools. It improves detection of emerging risks. Digital biomarkers reshape disease tracking. Wearables produce new data streams for modeling. Post-market analytics strengthen therapy management. Companies use AI to refine dosing strategies. Greater regulatory acceptance opens new routes for adoption.
Artificial Intelligence In Pharmaceutical Market Segmentation Analysis:
By Application
The Artificial Intelligence In Pharmaceutical Market advances through strong use across drug discovery, clinical trials, precision medicine, and pharmacovigilance. Drug discovery and design lead adoption due to high demand for faster molecule screening. Clinical trials gain value from predictive enrollment and protocol optimization. Precision medicine expands through growing access to genomic insights. Pharmacovigilance teams use automated signal detection to strengthen safety decisions. Manufacturing and supply chain units adopt AI to improve forecasting and quality control. Other areas such as sales analytics and lab automation widen overall scope.
- For instance, Insilico Medicine used its AI platform to generate a preclinical candidate in under 18 months, compared with traditional timelines of 4–6 years.
By Technology
Machine learning dominates due to its role in prediction, classification, and pattern recognition. Deep learning supports complex modeling for imaging, structural biology, and toxicity insights. Natural language processing extracts intelligence from research outputs, clinical notes, and regulatory documents. It improves workflow efficiency by reducing manual review time. Other technologies such as context-aware processing and querying methods support advanced decision pathways. Together, these tools shape a strong technology foundation for scalable deployment.
By Offering
Software holds the largest share due to strong demand for discovery engines, trial platforms, and analytics tools. Services expand through model development, integration support, and data management. Hardware grows with rising need for high-performance computing and GPU clusters. It supports complex simulations that require heavy processing capacity.
By Deployment
Cloud-based deployment leads due to flexibility, lower upfront cost, and faster scaling. Firms use cloud ecosystems to run large models and manage real-world data. On-premises systems retain demand among companies requiring full control of sensitive datasets. It supports stricter governance requirements.
By Drug Type
Small molecules lead adoption due to wide research pipelines and strong AI suitability for structure prediction. Large molecules gain traction with rising investment in biologics and precision therapies. It helps teams explore complex interactions across protein-based platforms.
- For instance, BioNTech applies deep-learning models to optimize mRNA and protein structures across multiple immunotherapy programs.
By Therapeutic Area
Oncology dominates due to strong biomarker discovery needs and heavy trial activity. CNS programs rely on AI to improve target understanding. Cardiovascular research applies predictive tools to refine risk models. Other therapeutic areas adopt AI to expand development accuracy and improve patient alignment.
Segmentation:
By Application
- Drug Discovery and Design
- Clinical Trials
- Precision Medicine
- Pharmacovigilance
- Manufacturing and Supply Chain
- Others (Sales Analytics, Lab Automation, Drug Repurposing)
By Technology
- Machine Learning
- Deep Learning
- Natural Language Processing
- Others (Context-Aware Processing, Querying Methods)
By Offering
- Software
- Services
- Hardware
By Deployment
- Cloud-Based
- On-Premises
By Drug Type
- Small Molecules
- Large Molecules
By Therapeutic Area
- Oncology
- CNS
- Cardiovascular
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America holds an estimated 42% share of the Artificial Intelligence In Pharmaceutical Market due to strong investments in digital R&D and early adoption of advanced analytics. The region benefits from tight integration between pharmaceutical companies and technology leaders. It gains momentum through widespread deployment of AI for molecule design, clinical trial oversight, and patient stratification. Regulatory bodies support digital transformation through clearer guidance on data use. Research ecosystems across the U.S. and Canada strengthen AI-driven innovation. Strong venture funding and active collaborations maintain the region’s leadership.
Europe accounts for nearly 29% share and demonstrates steady expansion supported by mature healthcare systems and strong academic–industry networks. The Artificial Intelligence In Pharmaceutical Market grows here through deeper adoption of predictive platforms and precision medicine programs. It gains traction as companies seek efficient trial execution and transparent AI validation frameworks. Regional funding supports ethical AI development across major drug pipelines. Demand for automation in regulatory workflows increases deployment across major markets. A strong emphasis on patient-centric research enhances the region’s position.
Asia Pacific holds roughly 21% share and ranks as the fastest-growing region due to rapid digital transformation across pharmaceutical hubs. The Artificial Intelligence In Pharmaceutical Market expands here through government-backed innovation programs and rising adoption of AI-enabled discovery tools. It sees stronger activity in China, India, and Japan where companies upgrade research infrastructure. Growing clinical trial outsourcing boosts AI-driven trial support systems. Local biotech firms collaborate with global technology companies to speed early development. Strong interest in precision medicine strengthens long-term growth.
Key Player Analysis:
- IBM Corporation
- NVIDIA Corporation
- Microsoft Corporation
- Alphabet Inc.
- Exscientia
- Atomwise, Inc.
- Deep Genomics
- PathAI
- BioXcel Therapeutics
- Cloud Pharmaceuticals, Inc.
- Biosymetrics
- Euretos
- Schrödinger, Inc.
- IQVIA
- Tempus AI
Competitive Analysis:
The Artificial Intelligence In Pharmaceutical Market features a competitive landscape driven by global technology firms, AI-native drug discovery companies, and established pharmaceutical enterprises. Leading technology players focus on scalable computing, cloud platforms, and GPU architectures that support complex simulations and molecular modeling. AI-focused biotech companies advance generative models, multimodal pipelines, and automated discovery engines that shorten development timelines. It gains strength when pharmaceutical companies form data-sharing alliances and strategic partnerships to enhance research productivity. Deep-learning innovators expand predictive capabilities for toxicity, pharmacokinetics, and structure optimization. Service providers build integrated platforms that support clinical trial intelligence, real-world evidence analytics, and regulatory document automation. Competitive differentiation centers on algorithm quality, dataset depth, model interpretability, and integration with existing R&D systems. Firms that deliver faster discovery cycles and stronger clinical insights gain a clear advantage in this dynamic market.
Recent Developments:
- In January 2026, AstraZeneca agreed to acquire Modella AI, a Boston-based company specializing in AI foundation models for oncology research. This deal, announced on January 13, aims to integrate Modella's technologies into AstraZeneca's drug development to accelerate clinical progress and biomarker identification.
- In February 2026, Merck and Mayo Clinic launched a new research collaboration focused on AI-enabled drug discovery and precision medicine. Announced on February 18, this partnership supports advanced therapeutic development.
- In January 2026, NVIDIA and Eli Lilly announced a co-innovation lab to advance AI applications in drug discovery, development, and manufacturing. The partnership, revealed around January 11, leverages NVIDIA's AI chips to revolutionize pharmaceutical processes.
- In November 2025, Insilico Medicine entered a research and licensing collaboration with Eli Lilly to utilize Insilico's Pharma.AI platform for novel drug candidates. The deal, announced on November 10, offers Insilico over $100 million in potential payments and royalties
Report Coverage:
The research report offers an in-depth analysis based on Application, Technology, Offering, Deployment, Drug Type, Therapeutic Area and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- AI-driven discovery engines will support faster identification of viable drug candidates across complex therapeutic areas.
- Integration of multimodal datasets will improve prediction accuracy for disease pathways and clinical responses.
- Partnerships between pharmaceutical and technology firms will expand, strengthening access to advanced computational models.
- Automated trial intelligence tools will reduce protocol deviations and improve patient alignment for global studies.
- AI-enabled precision medicine will gain traction, enhancing biomarker discovery and targeted therapy planning.
- Manufacturing teams will adopt predictive quality systems to improve batch reliability and operational stability.
- Regulatory units will apply AI-based documentation workflows to streamline compliance management.
- Real-world evidence platforms will support ongoing safety monitoring and therapy optimization.
- Cloud-native AI ecosystems will expand, offering scalable infrastructure for high-performance workloads.
- Cross-border research collaboration will grow, improving innovation speed within the Artificial Intelligence In Pharmaceutical Market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Artificial Intelligence In Pharmaceutical Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Artificial Intelligence In Pharmaceutical Market projected to grow between 2024 and 2032?
Which Artificial Intelligence In Pharmaceutical Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Artificial Intelligence In Pharmaceutical Market?
Who are the leading companies in the Artificial Intelligence In Pharmaceutical Market?
Which region commanded the largest share of the Artificial Intelligence In Pharmaceutical Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Artificial Intelligence In Pharmaceutical Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Artificial Intelligence In Pharmaceutical Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1750 million → 2032: USD 13528.67 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Artificial Intelligence In Pharmaceutical Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Artificial Intelligence In Pharmaceutical Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Artificial Intelligence In Pharmaceutical Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Artificial Intelligence In Pharmaceutical Market Drivers
- 3.3 Artificial Intelligence In Pharmaceutical Market Restraints & Challenges
- 3.4 Artificial Intelligence In Pharmaceutical Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Artificial Intelligence In Pharmaceutical Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Artificial Intelligence In Pharmaceutical Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Artificial Intelligence In Pharmaceutical category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Artificial Intelligence In Pharmaceutical Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Artificial Intelligence In Pharmaceutical Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Artificial Intelligence In Pharmaceutical market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Artificial Intelligence In Pharmaceutical Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Artificial Intelligence In Pharmaceutical Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Artificial Intelligence In Pharmaceutical Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Artificial Intelligence In Pharmaceutical (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Artificial Intelligence In Pharmaceutical Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Artificial Intelligence In Pharmaceutical Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Artificial Intelligence In Pharmaceutical Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Artificial Intelligence In Pharmaceutical Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Artificial Intelligence In Pharmaceutical Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Artificial Intelligence In Pharmaceutical Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Artificial Intelligence In Pharmaceutical Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Artificial Intelligence In Pharmaceutical Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Artificial Intelligence In Pharmaceutical Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
