
Market Overview:
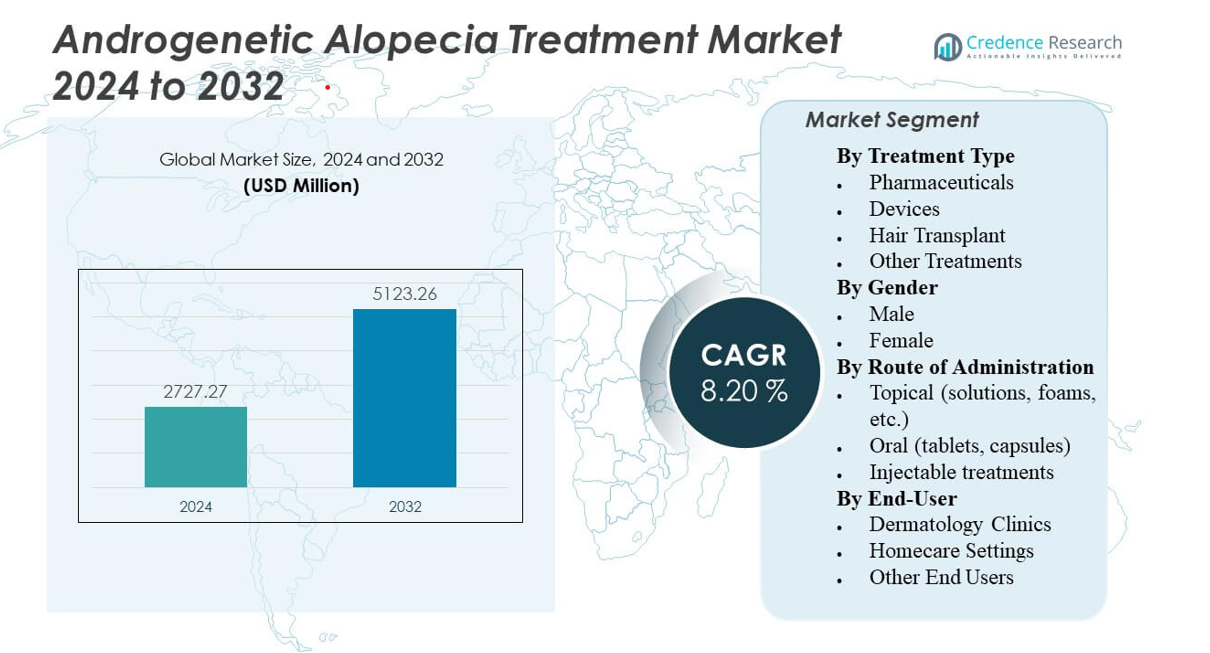
The Androgenetic Alopecia Treatment Market is projected to grow from USD 2,727.27 million in 2024 to an estimated USD 5,123.26 million by 2032, with a compound annual growth rate (CAGR) of 8.2% from 2024 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Androgenetic Alopecia Treatment Market Size 2024 | USD 2,727.27 Million |
| Androgenetic Alopecia Treatment Market, CAGR | 8.2% |
| Androgenetic Alopecia Treatment Market Size 2032 | USD 5,123.26 Million |
Growing awareness about hair restoration options, lifestyle changes, and the rising incidence of hormonal and genetic hair loss drive the market expansion. Increased adoption of FDA-approved drugs, advanced regenerative therapies, and low-level laser devices strengthens industry growth. The introduction of topical finasteride-minoxidil combinations and PRP-based solutions enhances treatment effectiveness. It continues to gain attention due to technological progress, higher cosmetic awareness, and improving clinical success rates worldwide.
North America leads the market due to high healthcare spending, strong dermatology infrastructure, and widespread use of approved pharmaceutical and device-based solutions. Europe follows, supported by research advancements and rising aesthetic preferences. The Asia Pacific region shows the fastest growth, driven by medical tourism, expanding middle-class income, and affordable treatment availability in countries such as India, China, and South Korea. Emerging regions in Latin America and the Middle East are gaining traction due to expanding clinic networks and growing consumer interest in aesthetic wellness.
Market Insights:
- The Androgenetic Alopecia Treatment Market is projected to grow from USD 2,727.27 million in 2024 to USD 5,123.26 million by 2032, driven by a CAGR of 8.2%.
- Rising adoption of approved pharmaceuticals, regenerative therapies, and laser-based solutions strengthens treatment acceptance among men and women.
- Increasing awareness of cosmetic health, along with earlier diagnosis, fuels strong demand for medical and non-invasive options.
- High treatment costs, limited reimbursement, and side-effect concerns with oral drugs remain key restraints for large patient groups.
- North America leads due to strong dermatology infrastructure and fastest adoption of advanced therapies.
- Asia Pacific shows the highest growth rate supported by medical tourism and affordable treatment availability.
- Expanding clinic networks and digital tele-consultations improve global access to personalized hair-loss treatments.
Market Drivers
Rising Prevalence of Hair Loss Due to Genetic and Hormonal Factors
The Androgenetic Alopecia Treatment Market experiences growth due to increasing cases of hereditary and hormone-driven hair loss among both genders. The condition is influenced by genetic predisposition, age, and hormonal imbalance, particularly dihydrotestosterone (DHT). Growing urban stress, poor diet, and exposure to pollutants further aggravate the issue. It continues to affect a significant population across developed and emerging economies. Demand for early diagnosis and effective treatment has increased among younger demographics. Healthcare awareness campaigns enhance early adoption of preventive therapies. Advanced diagnostic methods now enable more accurate assessment of hair loss patterns. These elements collectively strengthen market growth and treatment penetration.
- For example, according to StatPearls (NIH/NCBI), androgenetic alopecia is linked to increased scalp dihydrotestosterone (DHT) levels and higher 5-alpha-reductase activity in affected follicles, which drive progressive hair miniaturization. The condition is among the most common causes of hair loss, affecting nearly half of adult men and a significant proportion of women.
Technological Advancements and Product Innovation Driving Adoption
Continuous innovation in therapeutics supports strong expansion within the Androgenetic Alopecia Treatment Market. Manufacturers develop advanced topical, oral, and regenerative solutions to achieve higher efficacy and safety. It benefits from the introduction of stem cell therapy, exosome therapy, and microneedling-assisted drug delivery. Biotechnology firms focus on DHT blockers and protein-based growth stimulators with minimal side effects. Companies pursue patents for novel compounds targeting follicle regeneration. The shift toward non-invasive procedures attracts patients seeking cost-efficient alternatives to transplantation. Regulatory approvals for new formulations enhance trust among dermatologists. These advancements improve treatment outcomes and patient satisfaction, supporting higher market adoption rates.
- For example, Kintor Pharmaceutical’s pyrilutamide (KX-826) demonstrated statistically significant hair count improvement in its Phase II male androgenetic alopecia trial in China, achieving a 22.73 hairs/cm² increase from baseline at 24 weeks in the 0.5% BID topical group. The company has since advanced Phase III clinical trials for KX-826 in China and the United States.
Expanding Consumer Awareness and Cosmetic Consciousness Worldwide
Rising emphasis on appearance and self-confidence drives the global Androgenetic Alopecia Treatment Market. Social media influence and beauty awareness have encouraged individuals to seek professional treatments. It is observed that male and female consumers actively pursue medically proven solutions rather than temporary cosmetics. Marketing campaigns from pharmaceutical and aesthetic brands increase awareness about treatment availability. Clinics promote tailored solutions using telemedicine and AI-based hair diagnostics. The growing number of dermatology centers in urban areas improves accessibility. Rising disposable income allows more consumers to afford long-term therapy. These factors collectively promote acceptance and growth of the global treatment segment.
Growth of Medical Tourism and Expanding Healthcare Infrastructure
Medical tourism creates new growth avenues for the Androgenetic Alopecia Treatment Market, especially across Asia and Latin America. Affordable treatment costs attract international patients to countries such as India, Turkey, and Thailand. It benefits from world-class clinics offering advanced transplantation and regenerative procedures. Governments support healthcare infrastructure to promote international patient inflow. Increasing collaborations between local clinics and global aesthetic brands improve service quality. Surgeons specialize in modern transplantation methods like FUE and FUT, enhancing clinical success rates. Training programs and certifications ensure standardized practices. These developments strengthen the region’s competitiveness and boost market expansion.
Market Trends
Integration of Regenerative Medicine and Stem Cell Therapies in Hair Restoration
Recent advances in regenerative medicine influence the Androgenetic Alopecia Treatment Market by reshaping clinical approaches. Companies explore stem cell-derived exosomes and platelet-rich plasma (PRP) for natural follicle regeneration. It drives a shift from chemical-based treatments to biological restoration techniques. Clinical research demonstrates improved safety and long-term outcomes with regenerative solutions. Demand for autologous therapies grows among patients preferring personalized care. Biotech firms invest in growth factor formulations and cell-culture expansion systems. Healthcare professionals adopt hybrid approaches combining drugs with regenerative tools. These innovations redefine the therapeutic potential for sustainable hair regrowth.
Digitalization and AI-Based Diagnostic Platforms Enhancing Patient Experience
The rise of teledermatology and AI-based scalp analysis systems transforms patient engagement in the Androgenetic Alopecia Treatment Market. AI algorithms evaluate follicle density, hair pattern, and treatment response more accurately than manual observation. It enables customized therapy plans for each patient’s condition and progress. Clinics integrate 3D imaging and predictive modeling to assess treatment outcomes. Online consultation platforms expand access to dermatologists in remote regions. Companies use digital health apps to monitor adherence and track results. Partnerships between tech developers and pharmaceutical brands boost digital adoption. The integration of smart analytics enhances patient trust and retention rates.
- For example, the MEDELINK AI Scalp Analyzer (ASM 200) is a professional diagnostic device that provides high-resolution scalp imaging up to 500× magnification for clinical and trichology use. It is designed to assist specialists in evaluating scalp and hair conditions through AI-based image analysis to support treatment planning and progress tracking.
Growing Male Grooming Segment and Rising Female Participation in Hair Treatment
Gender dynamics evolve rapidly within the Androgenetic Alopecia Treatment Market as both men and women increasingly seek effective solutions. Men remain the dominant consumer group, but female demand shows strong momentum due to hormonal conditions like PCOS and post-pregnancy hair loss. It reflects a social shift toward open discussions on cosmetic treatments. Brands now design gender-specific formulations to address distinct scalp and hormonal differences. The rise of women-only dermatology centers supports this growing segment. Marketing strategies emphasize emotional well-being and confidence restoration. The expanding product range broadens the consumer base. This demographic transformation contributes to consistent long-term market growth.
- For example, Alpecin Caffeine Shampoo (C1) has been clinically tested and shown to help reduce hair loss and strengthen hair in men with hereditary hair loss. Research indicates that its topical caffeine formulation can stimulate hair roots and support hair growth, making it a recognized product in dermatological studies focused on androgenetic alopecia management.
Collaborations Between Pharmaceutical and Cosmetic Industries for Hybrid Solutions
Strategic partnerships between medical and cosmetic brands foster innovation in the Androgenetic Alopecia Treatment Market. Pharmaceutical firms collaborate with cosmetic producers to blend therapeutic efficacy with aesthetic appeal. It enables the creation of hybrid formulations like medicated serums and nutraceutical supplements. Joint R&D accelerates the approval of multifunctional products offering both treatment and prevention. Dermatology chains incorporate these dual-use solutions to increase retention. Clinical trials verify combined safety and performance, promoting regulatory acceptance. Global brands invest in co-branding campaigns targeting both medical and lifestyle consumers. This synergy reshapes the market toward holistic hair wellness.
Market Challenges Analysis
High Treatment Costs and Limited Reimbursement Policies Restrict Accessibility
Economic constraints remain a significant obstacle in the Androgenetic Alopecia Treatment Market. The cost of advanced treatments like transplantation and stem cell therapy is often beyond the reach of middle-income consumers. It affects large population segments in developing economies where insurance coverage is minimal. Many national healthcare systems categorize such treatments as cosmetic rather than medical, limiting reimbursement. Price sensitivity leads patients to opt for unregulated or unsafe alternatives. Regulatory barriers increase costs for manufacturers, further raising retail prices. Inconsistent import duties and taxation policies restrict product affordability. These financial limitations hinder uniform market growth and patient reach.
Adverse Effects and Lack of Standardization in Emerging Therapies
The expansion of the Androgenetic Alopecia Treatment Market faces challenges from side effects and lack of regulatory clarity. Minoxidil and finasteride, though effective, can cause scalp irritation or hormonal imbalance in some users. It discourages long-term adherence and lowers patient confidence. Newer regenerative and exosome-based therapies lack standardized clinical protocols. Inconsistent product quality across providers reduces reliability. Delayed regulatory approvals slow innovation and commercialization. Counterfeit drugs and unsupervised self-medication damage brand reputation. Addressing these issues requires strong quality frameworks and physician-led monitoring to protect consumer safety and trust.
Market Opportunities
Emergence of Novel Therapeutic Approaches Using Biologics and Peptide Formulations
Innovation in biologics and peptide-based drugs presents promising opportunities for the Androgenetic Alopecia Treatment Market. Research institutions collaborate with biotech firms to develop targeted therapies that stimulate dormant follicles. It paves the way for safer, long-acting formulations that replace conventional oral medications. Peptides promote vascularization and nutrient delivery to hair roots, improving efficacy. Companies explore nanocarriers for enhanced transdermal absorption. These scientific advancements drive investor confidence and attract venture capital into R&D. The rise of personalized medicine supports the introduction of genetic profiling for optimized treatment. Continuous innovation promises a future of more effective and patient-friendly solutions.
Expansion into Emerging Markets Through Local Manufacturing and Distribution Networks
The growing healthcare infrastructure in Asia, the Middle East, and Latin America opens new opportunities for the Androgenetic Alopecia Treatment Market. Local production units reduce dependency on imports and make treatments cost-effective. It enables brands to penetrate rural and semi-urban areas with affordable formulations. Governments encourage foreign direct investment and public-private partnerships to expand access. Awareness campaigns educate populations about safe hair restoration procedures. Partnerships with regional e-commerce platforms enhance product reach and visibility. Training programs for local dermatologists raise professional standards. This regional expansion strengthens long-term sustainability and diversifies the global market footprint.
Market Segmentation Analysis:
By Treatment Type
Pharmaceuticals dominate the Androgenetic Alopecia Treatment Market due to strong clinical validation and physician preference. Minoxidil and finasteride remain widely prescribed for both men and women, while Dutasteride and oral antiandrogens serve advanced cases. Devices such as low-level laser therapy (LLLT), laser caps, and combs gain traction for non-invasive use at home. Hair transplants using follicular unit extraction offer permanent results for patients seeking long-term restoration. Regenerative and stem cell therapies present emerging solutions for natural follicle regeneration. It continues to evolve through research improving efficacy and minimizing side effects.
- For example, Clinical studies on helmet-type low-level laser therapy (LLLT) devices have shown significant increases in hair density, with one randomized trial reporting an average gain of 17.2 hairs/cm² at 24 weeks compared with a 2.1 hairs/cm² decrease in the placebo group. These results confirm LLLT’s efficacy in promoting hair regrowth in androgenetic alopecia patients.
By Gender
Male patients account for the majority of the Androgenetic Alopecia Treatment Market due to higher genetic susceptibility. It shows earlier onset in men, driving early diagnosis and treatment. Female demand increases steadily due to hormonal imbalances and post-pregnancy hair loss. Pharmaceutical and topical solutions remain the preferred choice for both genders. Clinics offer gender-specific treatment plans addressing hormonal differences. Social acceptance and awareness campaigns encourage more female participation. Expanding cosmetic awareness drives equal treatment adoption across age groups.
By Route of Administration
Topical treatments lead the Androgenetic Alopecia Treatment Market, supported by ease of use and limited systemic exposure. Minoxidil-based foams and solutions remain the first line of treatment. Oral therapies such as finasteride and Dutasteride provide effective results for moderate to severe cases. Injectable procedures like PRP and mesotherapy offer regenerative benefits through professional supervision. It reflects increasing patient interest in multi-route therapies for enhanced effectiveness. Continuous research on delivery systems improves absorption and clinical performance.
- For example, a meta-analysis of seven randomized controlled trials, published in Frontiers in Medicine (2025), found that topical finasteride–minoxidil combination therapy significantly increased hair diameter by 2.26 µm compared to monotherapy (p = 0.005). These results confirm the enhanced clinical efficacy of dual-action topical treatments for androgenetic alopecia.
By End-User
Dermatology clinics dominate the Androgenetic Alopecia Treatment Market due to specialized expertise and access to advanced technologies. Hospitals and specialty centers handle complex surgical and regenerative cases. Homecare settings witness strong growth driven by the availability of OTC and laser-based products. It benefits from online platforms promoting self-care routines and personalized regimens. Expanding clinic networks and virtual consultations improve accessibility for global consumers. Partnerships between healthcare providers and product manufacturers enhance service quality and reach.
Segmentation:
By Treatment Type
- Pharmaceuticals (including Minoxidil, Finasteride, Dutasteride, Oral Antiandrogens)
- Devices (Low-Level Laser Therapy, Laser Cap, Laser Comb, Laser Helmet)
- Hair Transplant (including techniques like Follicular Unit Extraction)
- Other Treatments (such as counseling, regenerative therapies, and stem cell treatments)
By Gender
- Male
- Female
By Route of Administration
- Topical (solutions, foams, etc.)
- Oral (tablets, capsules)
- Injectable treatments
By End-User
- Dermatology Clinics
- Homecare Settings
- Other End Users (such as hospitals or specialty clinics)
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America leads the Androgenetic Alopecia Treatment Market with a market share of 37%, supported by high awareness, advanced medical infrastructure, and a strong presence of dermatology clinics. The United States dominates regional demand, driven by an aging population and growing adoption of innovative hair restoration therapies. It benefits from regulatory approvals for new drugs and devices, including laser-based and regenerative treatments. The region’s well-established pharmaceutical sector supports product innovation and commercialization. Increasing cosmetic awareness among men and women sustains growth. Canada’s healthcare reforms and accessibility to aesthetic services strengthen the region’s long-term potential.
Europe
Europe holds 29% of the global Androgenetic Alopecia Treatment Market, with countries such as Germany, the United Kingdom, France, and Italy showing strong demand for both surgical and non-surgical treatments. It benefits from advanced clinical practices, high-quality hair transplant centers, and research collaborations focusing on regenerative medicine. Growing emphasis on personal aesthetics and preventive healthcare supports market expansion. The region experiences rising popularity of low-level laser therapy devices and prescription solutions. Strict regulatory oversight ensures product safety and efficacy, promoting patient trust. Increasing spending on cosmetic procedures continues to sustain regional market stability.
Asia Pacific
Asia Pacific accounts for 24% of the Androgenetic Alopecia Treatment Market and represents the fastest-growing regional segment. Countries such as China, India, Japan, and South Korea drive growth through expanding middle-class income and rising cosmetic awareness. It benefits from a large patient base, affordable treatment options, and growing medical tourism. Government support for biotechnology and healthcare infrastructure further accelerates adoption. Clinics increasingly offer advanced transplantation and regenerative solutions at competitive costs. The region’s diverse population and increasing youth concern for appearance create sustained opportunities for future expansion across both urban and semi-urban markets.
Key Player Analysis:
- Johnson & Johnson (Rogaine)
- Merck & Co., Inc. (Propecia/Finasteride)
- Cipla Ltd.
- Sun Pharmaceutical Industries Ltd.
- Reddy’s Laboratories Ltd.
- Aurobindo Pharma
- Lexington International LLC (HairMax)
- Freedom Laser Therapy, Inc. (iRestore)
- Curallux LLC
- Apira Science Inc. (iGrow)
- Theradome Inc.
- Hims & Hers Health, Inc.
- Aclaris Therapeutics
- Biosplice Therapeutics
- Follicle Pharma
- Vitabiotics
- Kirkland Signature
Competitive Analysis:
The Androgenetic Alopecia Treatment Market is highly competitive, driven by pharmaceutical innovation, regenerative therapy development, and expanding clinical services. Key players include Johnson & Johnson, Merck & Co., Cipla Ltd., Sun Pharmaceutical Industries Ltd., and Lexington International LLC. It is characterized by strong product differentiation, with companies focusing on new formulations of minoxidil, finasteride, and stem cell-based therapies. Partnerships between biotech firms and dermatology clinics enhance treatment accessibility and technology integration. Manufacturers invest in research to develop safer, long-acting solutions with improved compliance. Marketing strategies emphasize digital engagement and awareness among consumers. Continuous product launches, patent approvals, and geographic expansion strengthen market presence and global competitiveness.
Recent Developments:
- In October 2025, Pelage Pharmaceuticals announced a significant milestone by closing a $120 million Series B funding round led by ARCH Venture Partners and Google Ventures, with participation from Main Street Advisors, Visionary Ventures, and YK Bioventures.
- In July 2025, Sun Pharmaceutical Industries Ltd. launched LEQSELVI (deuruxolitinib) 8 mg tablets in the U.S. as a new treatment for severe alopecia areata after settling a patent dispute with Incyte Corp. LEQSELVI demonstrated rapid clinical results, with nearly one-third of patients achieving near-complete hair regrowth in 24 weeks, and is expected to drive substantial growth in Sun Pharma’s U.S. dermatology segment.
Report Coverage:
The research report offers an in-depth analysis based on Treatment Type, Gender, Route of Administration and End-User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising consumer focus on appearance and self-confidence will continue driving treatment adoption across global markets.
- Expanding research in stem cell and regenerative medicine will enhance the efficacy of next-generation hair restoration therapies.
- Integration of AI-based scalp diagnostics and teleconsultation platforms will improve early detection and personalized treatment delivery.
- Growing acceptance of low-level laser devices will strengthen homecare-based treatment segments.
- Increasing medical tourism in Asia and Latin America will attract international patients seeking cost-effective hair transplant solutions.
- Strategic collaborations between biotech firms and pharmaceutical companies will accelerate innovation and product commercialization.
- Demand for combination therapies using topical, oral, and regenerative methods will expand patient outcomes and compliance.
- Rising awareness among women about hormonal hair loss management will broaden the consumer base.
- E-commerce and digital marketing channels will enhance accessibility and patient engagement.
- Global expansion of dermatology clinics and specialized hair centers will strengthen long-term market sustainability.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Androgenetic Alopecia Treatment Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Androgenetic Alopecia Treatment Market projected to grow between 2024 and 2032?
Which Androgenetic Alopecia Treatment Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Androgenetic Alopecia Treatment Market?
Who are the leading companies in the Androgenetic Alopecia Treatment Market?
Which region commanded the largest share of the Androgenetic Alopecia Treatment Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,727.27 million → 2032: USD 5,123.26 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Androgenetic Alopecia Treatment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Androgenetic Alopecia Treatment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Androgenetic Alopecia Treatment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Androgenetic Alopecia Treatment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Androgenetic Alopecia Treatment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Androgenetic Alopecia Treatment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Androgenetic Alopecia Treatment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Androgenetic Alopecia Treatment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,727.27 million → 2032: USD 5,123.26 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Androgenetic Alopecia Treatment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Androgenetic Alopecia Treatment Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Androgenetic Alopecia Treatment Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Androgenetic Alopecia Treatment Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

