
Market Overview
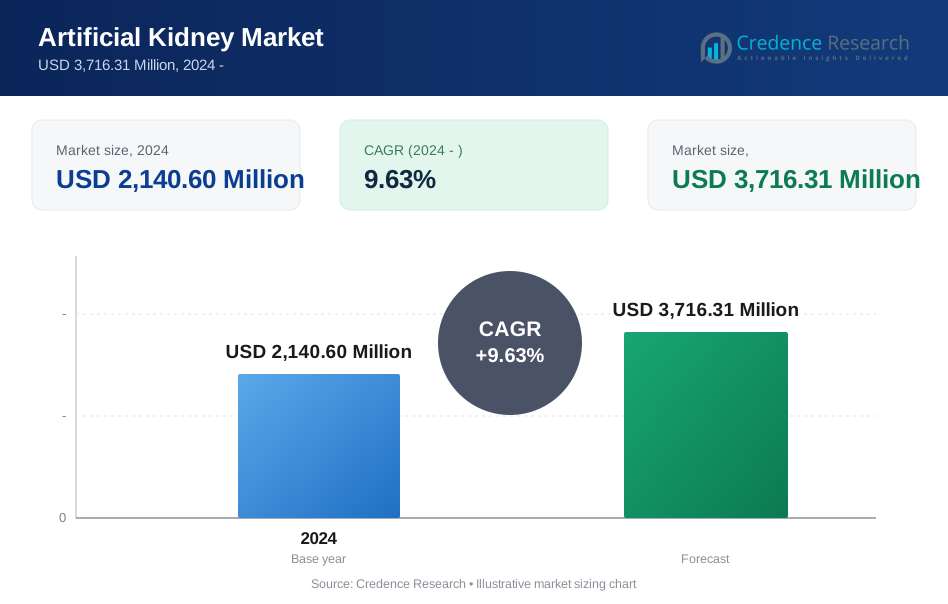
The Artificial Kidney Market is projected to grow from USD 2,140.60 Million in 2025 to an estimated USD 3,716.31 Million by 2032, with a CAGR of 9.63% from 2024 to 2032. Market growth is driven by rising chronic kidney disease burden, increasing demand for home-based renal replacement technologies and steady progress in miniaturized filtration and monitoring systems. North America leads market revenue, supported by advanced dialysis infrastructure, favorable reimbursement and strong presence of major renal care manufacturers.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period: | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Artificial Kidney Market Market Size 2024 | USD 2,140.60 Million |
| Artificial Kidney Market CAGR | 9.63% |
| Artificial Kidney Market Market Size 2032 | USD 3,716.31 Million |
Market Insights
- North America accounted for 38.2% of global Artificial Kidney Market revenue in 2024, making it the leading regional market.
- External Dialysis Systems led device type segmentation in 2024 with an estimated 68.4% share because of broad installed base and established clinical use.
- Hemodialysis remained dominant across technologies, supported by hospital and dialysis center preference for proven blood purification workflows.
- Fresenius Medical Care, Baxter, Medtronic, B. Braun and Nipro represent five major participants with broad renal care portfolios and distribution reach.
- Key market trend centers on portable and home-use artificial kidney platforms that integrate compact filtration, digital monitoring and patient mobility features.

Market Segmentation Analysis
By Device Type - External dialysis systems anchor current revenue leadership
On the basis of Device Type, the market is classified into Wearable Artificial Kidney, Implantable Kidney and External Dialysis Systems. External Dialysis Systems held the largest share of 68.4% in 2024, driven by established clinical protocols, broad reimbursement coverage and high procedural volume in chronic renal replacement therapy. Providers continue to favor these systems because they offer predictable treatment performance, trained staff familiarity and ready consumable availability. Demand remains strongest in high-burden ESRD management across hospitals and dialysis centers. Key companies operating in this segment include Fresenius Medical Care, Baxter and Nipro.
By Technology - Hemodialysis retains dominant clinical adoption
On the basis of Technology, the market is classified into Hemodialysis, Peritoneal Dialysis and Bioartificial Filtration. Hemodialysis accounted for the largest share of 64.7% in 2024 because of long-standing physician acceptance, strong infrastructure support and high suitability for intensive toxin and fluid removal. The segment benefits from routine use in center-based care, standardized consumable supply chains and broad machine compatibility. Ongoing upgrades in dialyzer efficiency and monitoring accuracy also sustain adoption. Key companies operating in this segment include Fresenius Medical Care, B. Braun and Asahi Kasei.
By Application - ESRD drives highest treatment demand
On the basis of Application, the market is classified into CKD, ESRD and AKI. ESRD captured the largest share of 58.9% in 2024, supported by recurring dialysis dependence, high treatment frequency and limited alternatives for patients awaiting transplant. This segment generates sustained equipment and consumable demand because patients require ongoing renal replacement support over long periods. Rising incidence of diabetes and hypertension continues to feed ESRD case volumes globally. Key companies operating in this segment include Baxter, Fresenius Medical Care and Rockwell Medical.
By Care Setting - Dialysis centers remain primary treatment hub
On the basis of Care Setting, the market is classified into Hospitals, Dialysis Centers and Homecare Settings. Dialysis Centers held the largest share of 46.3% in 2024 because they provide dedicated renal care workflows, recurring patient throughput and concentrated use of high-volume treatment systems. These facilities benefit from specialized staffing, optimized scheduling and strong consumables turnover, which supports equipment replacement cycles. Growth also reflects expansion of private operator networks in urban and semi-urban markets. Key companies operating in this segment include Fresenius Medical Care, Quanta and Nipro.
By Power System - External power supply supports present device base
On the basis of Power System, the market is classified into External Power Supply, Integrated Battery and Hybrid Systems. External Power Supply led with 55.8% share in 2024, reflecting the dominance of stationary dialysis platforms used in hospitals and centers. These systems offer dependable energy output, support longer treatment sessions and reduce battery-related performance constraints in high-load applications. Current installed equipment architecture still favors plug-in power designs over fully mobile configurations. Key companies operating in this segment include B. Braun, Baxter and Terumo.
By Component Type - Membranes form critical performance core
On the basis of Component Type, the market is classified into Membranes, Pumps, Sensors and Control Units. Membranes held the largest share of 33.6% in 2024 because filtration efficiency, biocompatibility and toxin clearance performance directly depend on membrane quality. Continuous product development in high-flux, selective and bioengineered membranes is improving treatment precision and patient tolerance. Recurring replacement needs also create a strong revenue stream for manufacturers. Key companies operating in this segment include Asahi Kasei, Nipro and Fresenius Medical Care.
Key Growth Drivers
Rising global kidney disease burden expands treatment pool
Rising prevalence of chronic kidney disease and end-stage renal disease continues to create sustained demand for artificial kidney technologies. Aging populations, diabetes, hypertension and obesity are increasing the number of patients who require long-term renal replacement support. Artificial kidney systems address persistent clinical need where transplant access remains limited and conventional dialysis capacity faces utilization pressure. This dynamic supports demand across wearable, external and next-generation implantable platforms. Global health estimates indicate that kidney diseases affect roughly 850 million people worldwide, underscoring the scale of unmet care demand and the need for more accessible filtration solutions.
Shift toward home-based renal care accelerates product innovation
Healthcare systems are increasingly moving renal care closer to patients, and that shift is reinforcing demand for compact artificial kidney platforms that are easy to operate, remotely monitored, and suitable for decentralized treatment outside traditional dialysis centers. Home-based therapy reduces travel time, eases scheduling pressure, and can improve day-to-day quality of life for people who need recurrent kidney replacement, which is why manufacturers are focusing on smaller footprints, simplified user interfaces, integrated alarms, and telehealth-ready data connectivity.
This direction is especially relevant in health systems trying to relieve pressure on overloaded in-center dialysis capacity while widening modality choice and supporting more patient-centered care pathways. Policy momentum is also helping, as CMS finalized payment for home dialysis for Medicare beneficiaries with acute kidney injury beginning in 2025, expanding reimbursement beyond the previous in-center limitation. A strong industry signal comes from Quanta Dialysis Technologies, whose HOME RUN trial enrolled 32 patients across 13 U.S. sites and saw more than 90 percent choose to continue using the system after the study, highlighting growing acceptance of home-compatible renal technology.
Advances in biomaterials and digital monitoring improve clinical value
Technical progress in membranes, pumps, sensors and control systems is making artificial kidney platforms more efficient and clinically differentiated. Better biocompatible materials can improve toxin clearance and fluid management while reducing treatment-related complications. At the same time, embedded sensors and software controls are allowing closer tracking of flow rate, pressure, solute removal and patient response during treatment. These capabilities help providers optimize therapy, support safer use in nontraditional settings and strengthen confidence in newer device formats. As research advances in bioartificial filtration and regenerative interfaces, market participants are finding new pathways to improve portability, precision and long-term therapeutic performance.
Key Trends & Opportunities
Trend: Portable and miniaturized systems gain commercial focus
Manufacturers are increasingly prioritizing portable artificial kidney platforms that can loosen the rigid treatment schedules associated with conventional dialysis and move renal care closer to the patient’s daily life, especially through home-based and ambulatory use models. This shift is being enabled by the miniaturization of pumps, sorbent-based dialysate regeneration, compact fluid management architecture, and lighter control electronics, all of which are helping developers reduce system size while still preserving toxin removal, ultrafiltration control, and continuous safety oversight.
The trend also reflects a broader healthcare push to manage stable patients outside high-cost center-based settings, since portable and wearable systems can improve convenience, reduce travel burden, and potentially support more continuous or flexible therapy patterns than intermittent in-center treatment. A strong proof point comes from AWAK Technologies, whose wearable peritoneal dialysis device weighs about 3 kg and uses only a few liters of dialysate per day instead of the 10 to 12 liters required by conventional PD systems, highlighting how compact design and lower water-use architecture are becoming key competitive differentiators.
Trend: Smart monitoring and connected care reshape treatment models
Artificial kidney platforms are increasingly incorporating sensors, connectivity tools and algorithm-driven controls that support real-time treatment oversight. Digital monitoring allows clinicians to track adherence, machine function and therapy parameters outside traditional dialysis settings, which improves intervention speed and supports home adoption. Remote data visibility is becoming a core purchasing criterion for providers managing distributed patient populations. Connected renal care also fits broader digital health strategies across hospitals and specialty networks. Growth in telehealth-enabled chronic disease management has strengthened demand for devices that can transmit actionable treatment data while reducing manual oversight burden.
Opportunity: Emerging markets open space for decentralized renal care
Emerging healthcare systems present meaningful opportunity for artificial kidney adoption, particularly where dialysis access remains uneven and urban centers face capacity constraints. Portable external systems and simplified home-use technologies can address infrastructure gaps more effectively than conventional large-footprint equipment. Private clinics, multispecialty hospitals and public procurement agencies are increasingly evaluating scalable renal care options that require fewer specialized resources. Companies that localize service support, training and consumable distribution are likely to improve uptake. Pricing flexibility and modular product design will be critical in capturing demand across lower-resource settings with rising CKD and ESRD burdens.
Opportunity: Bioartificial and implantable platforms offer long-term upside
Next-generation bioartificial filtration and implantable kidney concepts represent significant strategic opportunity as the market seeks alternatives to repetitive center-based dialysis. These technologies aim to improve physiologic filtration, reduce patient dependence on fixed treatment schedules and expand therapeutic options for advanced renal failure. Although commercialization timelines remain longer, continued investment from device developers, research institutions and strategic partners is building a broader innovation pipeline. Success in this area could reshape component demand toward advanced membranes, biosensors and intelligent control systems. Early movers with strong intellectual property and clinical validation pathways may secure premium positioning as the category matures.
Key Challenges
Challenge: High development complexity and regulatory burden
Artificial kidney systems combine fluid handling, blood compatibility, filtration efficiency, software control and patient safety requirements, making product development technically demanding. Companies must complete extensive verification, clinical validation and manufacturing quality steps before large-scale adoption can occur. This is especially challenging for wearable and implantable formats, where reliability expectations are higher and failure tolerance is minimal. Regulatory pathways can extend commercialization timelines and increase capital intensity for emerging developers.
Challenge: Cost, training and reimbursement variability limit adoption
Adoption barriers remain significant in markets with constrained reimbursement, uneven infrastructure and limited trained personnel. Advanced artificial kidney devices often require upfront investment in equipment, service support and patient education, which can slow procurement decisions. Home-use deployment also depends on user confidence, caregiver readiness and reliable after-sales support. In lower-income settings, consumable affordability and import dependence further complicate rollout, reducing speed of market penetration for novel systems.
Regional Analysis
North America Artificial Kidney Market Market Trends
North America accounted for 38.2% of global Artificial Kidney Market revenue in 2024. Region benefits from mature dialysis infrastructure, high diagnosed ESRD prevalence and favorable reimbursement for renal replacement therapy. Demand remains concentrated in external dialysis systems and hemodialysis technologies, though home-use and portable platforms are gaining attention as providers aim to reduce center burden. Integrated care networks and large dialysis operators support recurring procurement of membranes, pumps and control systems. Strong presence of Fresenius Medical Care, Baxter and Medtronic also reinforces commercialization, service coverage and clinical adoption across hospitals, dialysis centers and homecare channels.
Asia Pacific Artificial Kidney Market Market Trends
Asia Pacific represented 27.4% of global Artificial Kidney Market revenue in 2024. Regional growth is supported by rising diabetes and hypertension incidence, growing awareness of CKD screening and expanding dialysis capacity in China, Japan, India and Southeast Asia. Demand spans both hospital-led procurement and private dialysis network expansion, with strong interest in cost-efficient external systems and durable filtration components. Japan remains important for advanced membrane technologies and precision renal care equipment, while China supports volume demand and domestic manufacturing scale. Market competition is intensifying as global and regional suppliers target affordable treatment models and broader access.
Europe Artificial Kidney Market Market Trends
Europe held 24.1% of global Artificial Kidney Market revenue in 2024. Regional performance reflects strong chronic disease management systems, established nephrology care pathways and relatively broad access to dialysis reimbursement in major economies. Demand is stable for hemodialysis equipment, biocompatible membranes and digital control units that improve treatment consistency and patient safety. Several countries are also encouraging home dialysis expansion, which supports adoption of compact systems and remote monitoring capabilities. Competitive intensity remains high because multinational manufacturers operate alongside established regional renal technology suppliers and distribution partners.
Latin America Artificial Kidney Market Market Trends
Latin America captured 5.6% of global Artificial Kidney Market revenue in 2024. Market growth is driven by improving access to dialysis services, rising renal disease burden and gradual expansion of private nephrology clinics in Brazil, Mexico and other urban markets. External dialysis systems dominate because healthcare providers prioritize proven platforms with accessible service support and consumable compatibility. Public procurement and reimbursement constraints can pressure pricing, making affordability and maintenance reliability important purchasing criteria. Import dependence remains significant, which can affect lead times, replacement cycles and adoption of newer wearable technologies.
Middle East & Africa Artificial Kidney Market Market Trends
Middle East & Africa accounted for 4.7% of global Artificial Kidney Market revenue in 2024. Growth is shaped by increasing incidence of diabetes-linked kidney complications, investment in hospital infrastructure and gradual expansion of specialty renal centers in Gulf countries and selected African markets. Demand is concentrated in center-based dialysis systems, with hospitals remaining the main procurement channel for equipment and recurring components. Adoption of advanced artificial kidney technologies is slower because of budget constraints, uneven reimbursement and limited trained staff in several countries. Even so, premium hospitals and government-backed facilities are increasing interest in higher-performance membranes, sensors and digitally enabled systems. Regional shares are rounded and sum to approximately 100%.
Market Segmentations
Competitive Landscape
The Artificial Kidney Market features moderate to high competitive intensity, with established renal care companies competing alongside specialized innovators developing portable and bioartificial platforms. Leading players focus on product innovation in compact dialysis systems, high-performance membranes, intelligent sensors and software-enabled control units. Portfolio strategy centers on improving treatment efficiency, patient mobility and usability in homecare settings. Distribution strength remains critical, as hospitals, dialysis centers and specialty providers require dependable service networks, consumable supply and technical support. Partnerships with care providers, research institutions and technology developers are shaping clinical validation and commercialization pathways for next-generation devices. Large incumbents benefit from installed base, reimbursement familiarity and procurement relationships, while smaller companies compete through differentiated designs and niche innovation. Competitive advantage increasingly depends on regulatory execution, clinical data, patient-centric engineering and ability to scale recurring component sales alongside capital equipment deployment.
Key Player Analysis
- Fresenius Medical Care
- Baxter
- Medtronic
- B. Braun
- Nipro
- Terumo
- Asahi Kasei
- AWAK
- Quanta
- Rockwell Medical
Recent Developments
- In September 2025, a USC Stem Cell-led team reported a major advance toward building a synthetic kidney by creating highly mature kidney “assembloids” that combine filtering and urine-concentrating components in one lab-grown structure. The researchers said these were the most mature and complex kidney structures yet grown in the lab, and framed the work as both a better disease-modeling platform and a milestone toward a functional synthetic kidney for transplant candidates. The importance of this development lies in the fact that it moves artificial kidney research beyond supportive dialysis hardware and closer to biologically functional replacement tissue.
- In January 2026, UMC Utrecht began the first at-home patient testing in the Netherlands of the portable NeoKidney, a lightweight artificial kidney developed through collaboration among UMC Utrecht, the Dutch Kidney Foundation, and medtech company NextKidney. Utrecht University said the study would enroll about fifty patients to assess safety, effectiveness, ease of use, and quality-of-life impact, with the device designed for home use without the plumbing and electrical modifications required by standard home hemodialysis systems. This was a notable innovation milestone because it moved a portable artificial kidney from prototype-stage development into real-world home testing, with CE certification targeted for 2026 or 2027 if results remain positive.
- In February 2025, the University of Twente announced a new public-private collaboration to develop a biohybrid artificial kidney, supported by a €2.1 million five-year subsidy from Health Holland and backed by the Dutch Kidney Foundation. The program brings together RegMedXB, Imec, the University of Twente, Utrecht University, UMC Utrecht, and other partners to work on a continuously functioning implantable biohybrid kidney, making it one of the clearest recent collaboration-led advances in the field. The project is especially significant because it combines expertise in membrane technology, cell technology, materials science, and micro-electromechanical systems to move artificial kidney development closer to real-world clinical use.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Artificial Kidney Market in 2024?
What is driving growth in the Artificial Kidney Market?
What are the current trends in the Artificial Kidney Market?
Which segment leads the Artificial Kidney Market by device type?
Who are the top players in the Artificial Kidney Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,140.60 Million → 2032: USD 3,716.31 Million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Artificial Kidney Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Artificial Kidney Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Artificial Kidney Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Artificial Kidney Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Artificial Kidney Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Artificial Kidney Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Artificial Kidney Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Artificial Kidney Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,140.60 Million → 2032: USD 3,716.31 Million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Artificial Kidney Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Artificial Kidney Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Artificial Kidney Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Artificial Kidney Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

