
Outdoor Garden Furniture Market Overview:
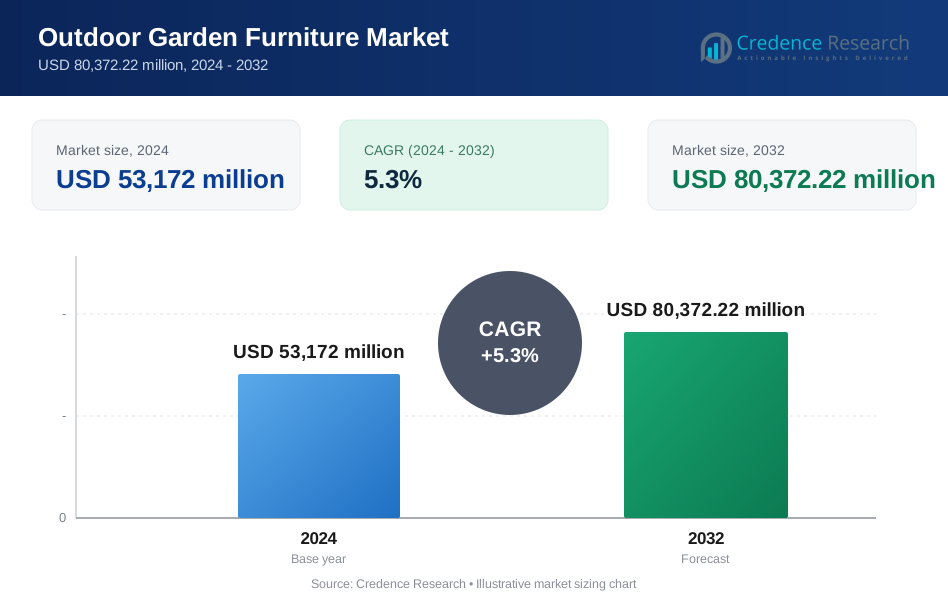
The Outdoor Garden Furniture market size was valued at USD 53,172 million in 2024 and is anticipated to reach USD 80,372.22 million by 2032, at a CAGR of 5.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Outdoor Garden Furniture Market Size 2024 | USD 53,172 million |
| Outdoor Garden Furniture Market, CAGR | 5.3% |
| Outdoor Garden Furniture Market Size 2032 | USD 80,372.22 million |
Outdoor Garden Furniture Market Insights
- Demand is driven by rising urbanization, outdoor living trends, and increased spending on home décor.
- Key trends include growing adoption of eco-friendly materials and smart, modular furniture for compact spaces.
- The market is moderately fragmented, with IKEA, Herman Miller, and Brown Jordan leading based on scale, brand strength, and distribution networks.
- North America led with 32% share in 2024, followed by Europe at 27% and Asia Pacific at 21%, while seating sets and wooden furniture remained dominant across product and material segments.

Outdoor Garden Furniture Market Segmentation Analysis:
By Product Type
Seating sets dominate the outdoor garden furniture market, accounting for over 35% of revenue share in 2024. These sets appeal to buyers seeking comfort and aesthetic appeal for outdoor lounging. Their popularity grows with increased demand for patio and backyard leisure spaces. Dining sets also hold a strong position due to their suitability for hosting outdoor meals and gatherings. Tables and chairs show steady demand among individual buyers and small households. Accessories like cushions and covers see seasonal growth, driven by maintenance and décor needs in developed markets.
- For instance, Home Depot’s outdoor dining furniture category includes table sets rated for 4 to 8 persons, with load-tested chairs supporting weights above 110 kg. Tables, chairs, and accessories maintain steady seasonal demand.
By Material
Wooden furniture leads the segment with around 40% market share, favored for its classic design and natural finish. Teak and eucalyptus are popular choices due to their weather resistance and durability. Consumers prefer wood for its upscale look in patios, decks, and garden settings. Metal furniture, especially aluminum and wrought iron, ranks second due to its strength and modern design compatibility. Plastic furniture continues to gain traction among cost-sensitive consumers seeking lightweight and low-maintenance solutions.
- For instance, Ashley Furniture offers outdoor collections featuring FSC-certified teak and highlights its natural durability, which allows properly maintained teak furniture to last for several decades outdoors.
By Sales Channel
e-Commerce leads the distribution with over 30% market share in 2024, driven by rising digital adoption and easy product comparison. Online platforms offer a wider variety, convenient delivery, and frequent discounts, attracting a broader consumer base. Furniture retail chains and brand outlets follow, benefiting from showroom experience and after-sales services. Modern trade and franchised stores capture demand in urban markets. Independent stores cater to regional preferences and custom orders, but face pressure from organized retail growth.
Key Growth Drivers
Rising Urbanization and Outdoor Living Culture
Growing urbanization, especially in emerging economies, is driving increased spending on home improvement, including outdoor spaces. As more consumers move into residential areas with balconies, terraces, and small gardens, there's a noticeable rise in demand for compact and functional garden furniture. In Western markets, outdoor living has evolved into an extension of indoor lifestyle. Homeowners invest in creating functional outdoor lounges and dining areas to enhance aesthetics and property value. This cultural shift, combined with higher disposable incomes, has led to consistent demand for stylish, weather-resistant, and multi-purpose outdoor furniture. The rise of premium housing projects with community gardens, patios, and balconies further amplifies product adoption.
- For instance, IKEA reported global retail sales of €47.6 billion in FY2023, a 6.6% increase over the previous year. While the company saw growth in sales value, it noted that overall sales volumes decreased globally due to inflation and the rising cost of living.
Expansion of Hospitality and Commercial Outdoor Spaces
The rapid growth in the hospitality sector, including cafes, restaurants, resorts, and boutique hotels, has significantly contributed to outdoor garden furniture demand. Businesses increasingly focus on enhancing customer experiences through well-furnished outdoor spaces. Alfresco dining, poolside lounges, and open-air waiting areas are now standard across many commercial establishments. These settings require durable, aesthetically pleasing, and low-maintenance furniture that withstands frequent use and weather elements. The tourism industry's post-pandemic recovery and the growing preference for open-air seating are reinforcing this trend. Consequently, B2B orders from hospitality players continue to grow, especially for modular seating sets, stackable chairs, and heavy-duty dining sets.
- For instance, EMU Group remains a primary supplier of metal outdoor furniture for the European hospitality sector, having sold millions of pieces globally since its inception. Its Rio R50 and Elodie collections are specifically engineered for commercial environments; the Rio R50 series features an ASFORM steel frame and MIG technology welding to ensure high mechanical performance and resistance to intensive stress.
Growth of Online Furniture Retail and Product Customization
The rapid evolution of e-commerce platforms has made outdoor furniture more accessible, especially in tier-2 and tier-3 cities. Online retailers offer a broad catalog of designs, material options, price ranges, and delivery models, driving consumer convenience. The rise in digital marketing, influencer-driven trends, and 3D product visualization tools also encourage online purchases. Furthermore, increasing interest in customization—whether in terms of color, size, material, or modular configurations—has allowed manufacturers to cater to diverse consumer preferences. Consumers now expect personalized and coordinated furniture sets that reflect their lifestyle. This shift supports innovation and diversification in design and material selection across product portfolios.
Key Trends and Opportunities
Sustainable and Eco-Friendly Materials Gaining Traction
Environmental concerns are reshaping buyer behavior in the garden furniture segment. Demand is growing for products made from sustainably sourced wood, recycled plastic, and environmentally friendly metals. Manufacturers are incorporating FSC-certified wood and repurposed materials to reduce environmental impact. Eco-conscious consumers prefer biodegradable coatings, water-based finishes, and furniture that can be easily dismantled for recycling. This trend is also opening opportunities for companies to differentiate by offering green product lines. Brands promoting circular economy principles such as product take-back schemes or refurbished collections stand to capture long-term value in both developed and emerging markets.
- For instance, Keter used over 410,000 metric tons of recycled plastic across its global furniture production between 2020 and 2023.
Smart Outdoor Furniture and Weather-Resistant Innovations
Innovation in weather-resistant materials is helping extend the outdoor furniture lifespan and usability. New coatings, anti-UV fabrics, rust-proof metals, and quick-dry foam are being used in high-end designs. An emerging trend is the integration of smart features like built-in lighting, solar-powered charging stations, foldable designs, and even Bluetooth speakers. These features enhance functionality and appeal to tech-savvy consumers. Demand for all-season furniture that resists fading, cracking, and mildew is particularly strong in regions with variable climates. These innovations are also helping brands expand into commercial segments that require both durability and style under heavy usage conditions.
Key Challenges
Fluctuating Raw Material Prices and Supply Chain Disruptions
The outdoor furniture industry heavily depends on raw materials like wood, aluminum, steel, and plastic. Volatility in these commodity prices significantly affects production costs. Post-pandemic global supply chain disruptions have caused delays in procurement and manufacturing, especially for imports from Asia-Pacific. Shipping costs, container shortages, and geopolitical tensions continue to pressure margins. Small and mid-sized manufacturers face greater risk due to limited bargaining power and weaker logistics infrastructure. These challenges often result in higher product prices, reduced profit margins, and longer lead times, impacting both retailers and end consumers.
Seasonal Demand and Weather Dependency
Outdoor Garden furniture is a highly seasonal product category, with peak demand typically concentrated in spring and summer. This seasonality leads to uneven revenue cycles and underutilized production capacity during off-seasons. Regions with harsh winters or unpredictable monsoons often see reduced demand for outdoor furnishings. Retailers struggle with excess inventory in the off-season, leading to discounting and reduced profitability. Manufacturers must invest in precise demand forecasting, inventory management, and adaptable product designs to remain competitive throughout the year. Expanding product lines to include weather-proof or indoor-outdoor convertible furniture may help address this limitation.
Regional Analysis
North America
North America held the largest share of the outdoor garden furniture market in 2024, accounting for over 32%. The U.S. leads the region due to high disposable income, strong home improvement culture, and rising investments in outdoor living spaces. Consumers seek premium, weather-resistant, and modular furniture to enhance patio, backyard, and balcony areas. The region also benefits from well-established retail chains and e-commerce platforms that offer a broad selection of outdoor furniture. High demand from the hospitality sector, especially resorts and restaurants, further supports regional sales growth.
Europe
Europe captured around 27% of the global market in 2024, driven by strong demand in countries like Germany, the UK, France, and Italy. The region shows a strong preference for wooden and eco-friendly furniture options, supported by stringent environmental regulations. Outdoor dining and garden aesthetics are deeply embedded in European lifestyle, particularly during spring and summer seasons. Increasing renovation activities and urban gardening trends further boost demand. Leading manufacturers in Europe also focus on weather-resistant and minimalist furniture designs, meeting both functional and aesthetic needs.
Asia Pacific
Asia Pacific accounted for nearly 21% market share in 2024 and is expected to grow rapidly due to urbanization and rising middle-class spending. China, India, and Southeast Asian countries are key growth drivers. A growing number of residential projects with balconies and gardens has boosted product adoption. Consumers are shifting toward modern designs with affordable price points. Rising tourism, restaurant expansions, and luxury real estate growth also contribute to B2B demand. The region benefits from local manufacturing strength and evolving online retail platforms, especially in India and China.
Latin America
Latin America held close to 9% market share in 2024, supported by expanding hospitality sectors and rising urban population. Brazil and Mexico lead the market with growing interest in outdoor lounging and dining experiences. While premium furniture adoption remains limited, demand for cost-effective plastic and metal-based furniture is increasing. The popularity of open-air living and events in warmer climates supports seasonal sales. Growth in DIY culture and improving e-commerce access also open new retail opportunities for brands targeting this region.
Middle East & Africa
The Middle East & Africa region contributed about 6% of the global market share in 2024. The Middle East, led by the UAE and Saudi Arabia, is experiencing increased demand for outdoor luxury furniture in residential compounds, hotels, and resorts. High investment in tourism infrastructure and villa-style living boosts demand. In Africa, market growth remains modest but is improving with rising urban development and better retail infrastructure. Consumers prefer durable and weather-resistant products due to harsh sunlight and temperature fluctuations across several areas in this region.
Outdoor Garden Furniture Market Segmentations:
By Product Type
- Tables
- Chairs
- Dining Sets
- Seating Sets
- Accessories
By Material
- Plastic
- Metal
- Wooden
By Sales Channel
- Independent Stores
- Franchised Stores
- Modern Trade
- Furniture Retail Chains
- Brand Outlets
- e-Commerce
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The outdoor garden furniture market remains moderately fragmented, with a mix of global brands and regional players competing on design, material innovation, and distribution reach. Leading companies such as Herman Miller Inc., Trex Company Inc., IKEA, and Brown Jordan focus on product durability, weather resistance, and sustainable materials to attract eco-conscious buyers. Kettal Group and Roda Srl emphasize premium aesthetics and luxury outdoor living collections, targeting high-income residential and hospitality buyers. E-commerce has emerged as a major battleground, prompting brands to invest in digital catalogs and direct-to-consumer strategies. Strategic partnerships with resort chains and home improvement retailers further enhance brand visibility. Price competition is intense in the mid-range segment, while the premium segment remains relatively insulated due to brand loyalty and customization demands. Companies are also investing in modular furniture designs and quick-assembly models to meet evolving consumer preferences. Innovation, product lifecycle durability, and brand positioning remain key factors shaping competitive advantage.
Key Player Analysis
- Kettal Group
- Brown Jordan
- IKEA
- Tuuci
- Roda Srl
- Century Furniture
- Trex Company Inc.
- Herman Miller Inc.
Recent Developments
- In April 2025, Tuuci unveiled multiple new outdoor furniture pieces, including the Canyon Crue collection and Ocean Master MAX Bolero parasol, at Salone del Mobile 2025.
- In 2025, Kettal showcased its latest outdoor furniture designs at Salone del Mobile in Milan, highlighting new collections focused on modern outdoor seating and modular sofas.
- In 2024, IKEA launched its new outdoor furniture and décor collection for spring and summer, featuring updated sofas, dining sets, and planters.
- In July 2022, the Spain-based outdoor furniture manufacturer Andreu World launched its first showroom in Germany, located in Hanau. The showroom, which spans 100 square meters, was designed to be a meeting and workspace for design professionals.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Material, Sales Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for premium and customizable outdoor furniture will continue to grow in residential sectors.
- Modular seating and multifunctional furniture designs will gain popularity among urban homeowners.
- E-commerce platforms will expand their market share through better logistics and virtual visualization tools.
- Sustainability will drive innovation in materials such as recycled plastic, FSC-certified wood, and powder-coated metals.
- The hospitality industry will boost demand for stylish and weather-resistant furniture in outdoor spaces.
- Asia Pacific will emerge as the fastest-growing region due to urbanization and rising middle-class income.
- Integration of smart features like solar lighting and wireless charging will enhance product value.
- Companies will focus on supply chain localization to reduce delays and production costs.
- Retailers will invest in seasonal product launches and bundled offers to drive year-round sales.
- Competitive pressure will increase in mid-range segments, prompting design differentiation and pricing strategies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Outdoor Garden Furniture market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Outdoor Garden Furniture market projected to grow between 2024 and 2032?
Which Outdoor Garden Furniture market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Outdoor Garden Furniture market?
Who are the leading companies in the Outdoor Garden Furniture market?
Which region commanded the largest share of the Outdoor Garden Furniture market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Outdoor Garden Furniture Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Outdoor Garden Furniture Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 53,172 million → 2032: USD 80,372.22 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Outdoor Garden Furniture Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Outdoor Garden Furniture Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Outdoor Garden Furniture Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Outdoor Garden Furniture Market Drivers
- 3.3 Outdoor Garden Furniture Market Restraints & Challenges
- 3.4 Outdoor Garden Furniture Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Outdoor Garden Furniture Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Outdoor Garden Furniture Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Outdoor Garden Furniture category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Outdoor Garden Furniture Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Outdoor Garden Furniture Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Outdoor Garden Furniture market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Outdoor Garden Furniture Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Outdoor Garden Furniture Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Outdoor Garden Furniture Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Outdoor Garden Furniture (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Outdoor Garden Furniture Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Outdoor Garden Furniture Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Outdoor Garden Furniture Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Outdoor Garden Furniture Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Outdoor Garden Furniture Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Outdoor Garden Furniture Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Outdoor Garden Furniture Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Outdoor Garden Furniture Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Outdoor Garden Furniture Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
