
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Asia Pacific Distributed Acoustic Sensing Market Size 2024 | USD 190.20 million |
| Asia Pacific Distributed Acoustic Sensing Market, CAGR | 13.4% |
| Asia Pacific Distributed Acoustic Sensing Market Size 2032 | USD 520.21 million |
Market Overview:
The Asia Pacific Distributed Acoustic Sensing Market is projected to grow from USD 190.20 million in 2024 to an estimated USD 520.21 million by 2032, with a compound annual growth rate (CAGR) of 13.4% from 2024 to 2032.
Several factors are propelling the growth of the DAS market in the Asia Pacific region. Foremost among these is the escalating demand for real-time monitoring and security solutions across various industries, including oil and gas, energy, transportation, and security. The oil and gas sector, in particular, is leveraging DAS technology for enhanced real-time monitoring of pipelines and wellbores, thereby improving safety and operational efficiency. Additionally, the region's rapid industrialization and urbanization are driving the need for advanced infrastructure monitoring solutions, further boosting the adoption of DAS technologies. Governments across the region are prioritizing smart infrastructure policies, which include investment in fiber optic sensing networks. The integration of DAS with AI and IoT platforms is further enhancing its value proposition, making it indispensable for predictive maintenance and anomaly detection.
Within the Asia Pacific region, countries such as China, India, and Japan are leading the adoption of DAS technologies. China’s extensive pipeline infrastructure and significant investments in smart city initiatives have made it a key market for DAS applications. India’s growing energy demands and focus on infrastructure development are also contributing to the increased deployment of DAS systems. Japan’s emphasis on technological innovation and infrastructure safety aligns with the capabilities of DAS, facilitating its integration into various sectors. Southeast Asian nations are also beginning to invest in DAS as they modernize transport and utility networks. The regional diversity in application use cases is fostering innovation and enabling tailored DAS solutions across different economic and regulatory environments.
Market Insights:
- The Asia Pacific DAS market is projected to grow from USD 190.20 million in 2024 to USD 520.21 million by 2032, driven by the increasing need for real-time monitoring across industries.
- The Global Distributed Acoustic Sensing Market is projected to grow from USD 639.45 million in 2024 to an estimated USD 1596.46 million by 2032, with a compound annual growth rate (CAGR) of 12.12% from 2024 to 2032.
- Key drivers include the demand for enhanced security solutions in oil and gas, transportation, and infrastructure, alongside government investments in smart infrastructure policies.
- The oil and gas industry is a significant contributor, leveraging DAS for pipeline monitoring, wellbore surveillance, and operational efficiency.
- High initial installation costs and complex data interpretation remain major market restraints, limiting broader adoption in some sectors.
- China, India, and Japan are the leaders in DAS adoption, driven by investments in energy infrastructure, smart cities, and technological innovation.
- Southeast Asian nations are beginning to invest in DAS as part of their infrastructure modernization, particularly in transportation and utility networks.
- Regional governments' emphasis on fiber optic sensing networks and AI integration is expected to enhance DAS's predictive maintenance and anomaly detection capabilities.
Report scope
This report segments the Asia Pacific Distributed Acoustic Sensing Market as follow;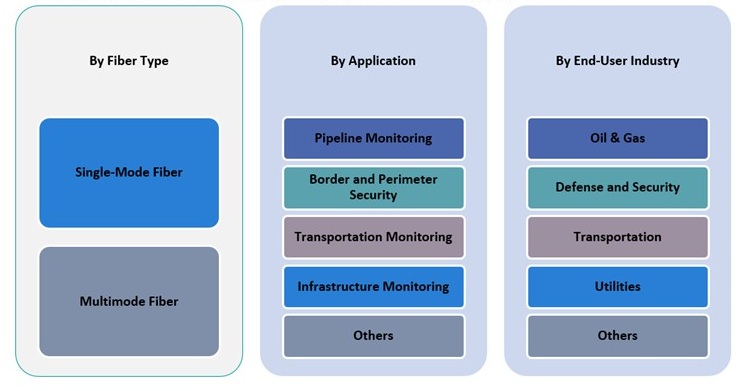
Market Drivers:
Rising Demand for Enhanced Security and Surveillance
The Asia Pacific region is witnessing an increasing demand for sophisticated security and surveillance technologies, which significantly drives the adoption of distributed acoustic sensing (DAS) systems. As threats to critical infrastructure and public safety continue to evolve, governments and enterprises are deploying DAS solutions to ensure continuous, real-time monitoring of sensitive assets. These systems offer high-resolution detection capabilities over extended distances, enabling operators to identify and respond to anomalies swiftly. The ability of DAS to convert standard fiber optic cables into intelligent sensors provides a cost-effective yet highly reliable method for securing perimeters, transportation networks, and utility infrastructures.
Growth in Oil and Gas Infrastructure Monitoring
Another critical driver of the Asia Pacific DAS market is the expansion of oil and gas exploration and distribution activities. Countries such as China, India, and Indonesia are investing heavily in upstream and midstream oil and gas infrastructure to meet growing energy demands. DAS technology is increasingly deployed for pipeline monitoring, wellbore diagnostics, and leak detection in these operations, providing continuous and accurate data in real time. For instance, Halliburton’s RezConnect DAS system is employed for real-time monitoring in oil wells to optimize production and enhance safety. By reducing operational risks and enhancing safety protocols, DAS systems are helping operators optimize asset performance and comply with stringent regulatory requirements. The technology's ability to detect minute acoustic changes across long distances makes it particularly valuable in remote and hard-to-access areas.
Acceleration of Urbanization and Smart Infrastructure Projects
The rapid pace of urbanization across Asia Pacific has led to an upsurge in smart infrastructure initiatives, further accelerating the adoption of DAS systems. Governments are prioritizing the integration of advanced monitoring technologies within their smart city blueprints to improve public services and infrastructure resilience. Distributed acoustic sensing plays a vital role in ensuring the structural integrity of bridges, tunnels, and transportation systems by delivering continuous, real-time feedback on stress levels and potential faults. The technology’s compatibility with existing fiber optic networks allows for seamless deployment, making it a preferred choice for infrastructure developers aiming to build intelligent and sustainable urban environments.
Technological Integration and Digital Transformation Initiatives
Technological advancements and the increasing push for digital transformation across industries are also fueling the growth of the distributed acoustic sensing market in the region. Industries are progressively adopting DAS in combination with artificial intelligence, machine learning, and Internet of Things (IoT) platforms to achieve predictive analytics and automated system responses. For example, Schlumberger’s Optiq DAS system leverages AI-driven analytics to detect anomalies in pipeline networks, enabling proactive maintenance. This integration significantly enhances operational efficiency by enabling early anomaly detection and real-time decision-making. As businesses strive for automation and data-driven optimization, DAS is emerging as a key enabler of intelligent sensing infrastructure, aligning well with the broader digital goals of Asia Pacific economies.
Market Trends:
Increased Adoption in Transportation and Railways
One of the emerging trends in the Asia Pacific distributed acoustic sensing market is the growing use of DAS technology in the transportation and railway sectors. For instance, governments and transportation authorities are increasingly deploying DAS along railway tracks and highways to detect train movements, monitor traffic flow, and identify anomalies such as rail fractures or unauthorized intrusions. This trend is particularly prominent in countries such as Japan and South Korea, where safety and precision in public transportation are critical. DAS enables real-time acoustic monitoring over long distances without requiring power sources or sensors along the track, making it ideal for linear infrastructure management.
Expansion of Utility Monitoring and Environmental Applications
The utility sector is expanding its use of DAS for monitoring power lines, water pipelines, and geothermal networks. As energy distribution systems become more complex and stretched across urban and remote regions, utility providers in the Asia Pacific region are utilizing DAS to ensure continuous oversight and reduce downtime. For example, DAS systems have been deployed to monitor pipeline integrity by detecting leaks or damages in real time, enhancing operational safety. In parallel, environmental monitoring is gaining traction, with DAS being applied to detect landslides, monitor seismic activity, and track permafrost shifts in mountainous regions. These applications are increasingly relevant in climate-sensitive areas such as the Himalayas and Southeast Asian coastlines, where environmental risks are intensifying and require continuous observation
Rising Investments in Telecom Infrastructure and 5G Networks
The rollout of 5G infrastructure across Asia Pacific has led to increased investments in fiber optic networks, which directly support the expansion of distributed acoustic sensing capabilities. Telecom providers are beginning to leverage DAS not only for physical infrastructure monitoring but also to gain insights into external disturbances that may impact network performance. Countries such as China and Australia are leading this trend by embedding DAS technology within their fiber backbone to enhance predictive maintenance and detect faults before they escalate into major disruptions. This convergence of telecom infrastructure and acoustic sensing is opening new avenues for innovation and operational efficiency.
Integration with Cloud-Based Platforms and Edge Computing
Another significant trend is the integration of DAS systems with cloud-based platforms and edge computing technologies. As industries seek scalable and flexible data processing solutions, the ability to analyze DAS-generated data at the edge or in the cloud offers substantial advantages in terms of speed and responsiveness. Cloud integration allows for centralized data access, while edge computing supports localized decision-making and real-time alerts. This dual approach is gaining popularity in large-scale industrial operations such as offshore energy projects and border security, where latency and data volume are critical considerations. The trend reflects the region’s broader digital evolution, pushing for smarter and more responsive sensing networks.
Market Challenges Analysis:
High Installation and Deployment Costs
One of the primary restraints affecting the Asia Pacific distributed acoustic sensing (DAS) market is the high cost associated with installation and deployment. For instance, DAS systems require advanced optical fibers, interrogator units, and specialized software for data visualization, which collectively contribute to high upfront expenses. Companies such as Halliburton have highlighted that the integration of DAS into existing oilfield operations involves significant investment in hardware and system calibration, making it less accessible to smaller enterprises. Many industries, particularly small and medium enterprises, face budgetary constraints that limit their ability to adopt this technology at scale. Furthermore, retrofitting existing infrastructure with DAS capabilities may require extensive modifications, adding to the overall expenditure and delaying implementation timelines.
Complexity of Data Interpretation and Technical Limitations
Another notable challenge lies in the complexity of interpreting the vast amounts of data generated by DAS systems. Accurate analysis requires advanced algorithms and skilled personnel to differentiate between critical signals and background noise. In regions where technical expertise and data science capabilities are still developing, this presents a significant barrier to adoption. Additionally, environmental factors such as temperature fluctuations, signal attenuation, and mechanical stress can impact signal quality and accuracy, leading to inconsistent performance in certain field applications. These technical limitations can affect the reliability of DAS in complex operational environments.
Regulatory Hurdles and Infrastructure Incompatibility
Regulatory challenges also pose a constraint in several Asia Pacific countries, where telecommunications and infrastructure policies may restrict the deployment of fiber optic-based sensing systems. Varying national standards and approval processes can delay project implementation, particularly in cross-border applications or government-monitored sectors. Moreover, in rural or underdeveloped regions, the lack of supportive infrastructure such as power supply and communication networks can hinder the feasibility of DAS deployment. Overcoming these challenges requires coordinated efforts among technology providers, policymakers, and industry stakeholders to align standards and facilitate smoother adoption across the region.
Market Opportunities:
The Asia Pacific distributed acoustic sensing (DAS) market presents substantial opportunities as industries increasingly seek advanced, real-time monitoring solutions to enhance safety, efficiency, and operational intelligence. With the region undergoing rapid industrial transformation, there is a growing demand for intelligent sensing technologies across sectors such as oil and gas, transportation, utilities, and telecommunications. DAS systems, which utilize existing fiber optic infrastructure, offer a scalable and cost-effective alternative to conventional monitoring tools, enabling continuous data acquisition over large areas. As governments invest in smart infrastructure and energy security, the potential for widespread DAS deployment is expanding, especially in large-scale pipeline and perimeter surveillance applications.
Emerging economies within Asia Pacific, including India, Indonesia, Vietnam, and the Philippines, offer untapped market potential due to ongoing investments in infrastructure development and urbanization. These nations are gradually embracing digital transformation strategies that align with the capabilities of DAS, particularly in supporting smart city frameworks and enhancing critical infrastructure resilience. Additionally, the integration of DAS with cloud computing, artificial intelligence, and IoT platforms is creating new avenues for innovation, enabling predictive analytics and real-time automation across industrial processes. As industries prioritize risk mitigation and operational continuity, the growing awareness and availability of DAS technology provide a favorable environment for market expansion. This presents a compelling opportunity for technology providers, system integrators, and telecom operators to establish strategic partnerships and extend their footprint across diverse applications in the Asia Pacific region.
Market Segmentation Analysis:
The Asia Pacific distributed acoustic sensing (DAS) market is segmented by fiber type, application, and end-user industry, each playing a distinct role in shaping the market dynamics.
By fiber type, single-mode fiber dominates the market due to its long-distance sensing capabilities and high sensitivity, making it ideal for extensive infrastructure such as pipelines and perimeter monitoring. Multimode fiber, while less prevalent, is gaining traction in short-range applications where cost efficiency and ease of integration are prioritized, particularly in localized infrastructure monitoring.
By application, pipeline monitoring holds a substantial market share, driven by the region’s expanding oil and gas networks and the critical need for early leak detection and operational safety. Transportation monitoring is another key segment, where DAS is increasingly used to track railway operations and road conditions. Border and perimeter security applications are growing steadily as governments enhance surveillance and threat detection capabilities. Infrastructure monitoring is gaining momentum as countries invest in smart city projects, while the “others” category captures niche uses such as seismic activity detection and underwater cable protection.
By end-user industry, the oil and gas sector remains the leading adopter of DAS solutions, leveraging them for real-time data acquisition and asset integrity management. The defense and security sector follows closely, applying DAS for strategic surveillance and intrusion detection. Transportation and utilities are also expanding their use of DAS to enhance operational efficiency and ensure service reliability. The market’s diversification across these segments underscores the technology’s adaptability and rising relevance across Asia Pacific industries.
Segmentation:
By Fiber Type:
- Single-Mode Fiber
- Multimode Fiber
By Application:
- Pipeline Monitoring
- Transportation Monitoring
- Border and Perimeter Security
- Infrastructure Monitoring
- Others
By End-User Industry:
- Oil & Gas
- Defense and Security
- Transportation
- Utilities
- Others
Regional Analysis:
The Asia Pacific distributed acoustic sensing (DAS) market is experiencing rapid growth, driven by increasing demand for real-time monitoring solutions across various industries. In 2023, the region accounted for approximately 21.6% of the global distributed fiber optic sensor market revenue, highlighting its significant role in the global landscape.
China stands out as a major contributor to the DAS market in Asia Pacific, owing to its extensive pipeline infrastructure and substantial investments in smart city initiatives. The country's focus on enhancing energy security and infrastructure monitoring has led to widespread adoption of DAS technologies. India is also emerging as a key market, with growing energy demands and infrastructure development projects driving the deployment of DAS systems. The government's emphasis on improving pipeline safety and urban infrastructure monitoring aligns with the capabilities of DAS technology.
Japan's DAS market is characterized by its commitment to technological innovation and infrastructure safety. The country leverages DAS for monitoring critical infrastructure, including bridges and tunnels, to ensure structural integrity and public safety. Additionally, Japan's susceptibility to natural disasters has prompted the integration of DAS for seismic monitoring and early warning systems.
Other countries in the region, such as South Korea, Australia, and Southeast Asian nations, are also recognizing the benefits of DAS technology. These countries are investing in DAS for applications ranging from transportation monitoring to border security, contributing to the overall growth of the market in Asia Pacific.
The Asia Pacific DAS market's expansion is further supported by advancements in fiber optic sensing technologies and increasing awareness of the benefits of real-time monitoring. As industries continue to prioritize safety, efficiency, and infrastructure resilience, the demand for DAS solutions is expected to rise, solidifying Asia Pacific's position as a key growth region in the global DAS market.
Key Player Analysis:
- AP Sensing GmbH
- Bandweaver Technologies
- Silixa Ltd.
- Omnisens SA
- Fotech Solutions Ltd.
- OptaSense (QinetiQ Group)
- Schlumberger Limited\
- Baker Hughes Company
- OFS Fitel LL
- Hifi Engineering Inc.
Competitive Analysis:
The Asia Pacific distributed acoustic sensing (DAS) market is characterized by a competitive landscape featuring both global leaders and regional innovators. Prominent multinational corporations such as Baker Hughes, Halliburton, and Schlumberger have established a strong presence in the region, leveraging their extensive experience in the oil and gas sector to offer advanced DAS solutions tailored for pipeline monitoring, wellbore surveillance, and hydraulic fracturing optimization. These companies continue to invest in research and development to enhance the performance and reliability of their DAS systems, thereby maintaining their competitive edge. In addition to these global players, regional companies like Bandweaver (China) and Future Fibre Technologies (Australia) contribute to the market's dynamism by addressing localized needs and regulatory requirements. These firms focus on applications such as perimeter security and infrastructure monitoring, offering cost-effective and adaptable DAS solutions. The competitive environment is further intensified by strategic initiatives, including mergers, acquisitions, and partnerships, aimed at expanding product portfolios and market reach. As the demand for real-time monitoring and security solutions grows across various industries, the Asia Pacific DAS market is poised for continued innovation and expansion
Recent Developments:
- In July 2024, VIAVI Solutions Inc.introduced the NITRO® Fiber Sensing solution, a cutting-edge real-time asset monitoring and analytics system designed for critical infrastructure. This innovative solution integrates Distributed Acoustic Sensing (DAS), Distributed Temperature Sensing (DTS), and Simultaneous Temperature and Strain Sensing (DTSS) technologies. It enables operators to monitor fiber optic cables for temperature, strain, and acoustic vibrations, providing precise alerts to detect and prevent external threats such as human interference or environmental hazards.
- In September 2023, researchers from the University of New Mexicoand Sandia National Laboratories developed a novel method to monitor local sea ice in Alaska using Distributed Acoustic Sensing (DAS) technology. By leveraging a telecommunications fiber optic cable combined with machine learning algorithms, the team analyzed ground vibrations caused by ocean waves to detect sea ice coverage and strength.
- In December 2023, Luna Innovations Inc. acquired Silixa Ltd., a UK-based leader in distributed fiber optic sensing solutions. This strategic acquisition enhanced Luna’s capabilities in distributed acoustic sensing (DAS), distributed temperature sensing (DTS), and distributed strain sensing (DSS), enabling improved performance for applications in energy, natural environments, mining, and defense.
Market Concentration & Characteristics:
The Asia Pacific distributed acoustic sensing (DAS) market exhibits a moderately concentrated structure, with a few key players commanding significant market shares. Notable companies such as Baker Hughes and Halliburton Energy Services, Inc. each hold over 8% of the global market share, reflecting their strong presence and influence in the DAS sector. These industry leaders leverage their extensive experience in the oil and gas sector to deliver advanced DAS solutions tailored for applications like pipeline monitoring and wellbore surveillance. In addition to these global entities, regional players like Bandweaver and Future Fibre Technologies contribute to the market's dynamism by addressing localized needs and regulatory requirements. The DAS market in Asia Pacific is characterized by continuous innovation, with companies investing heavily in research and development to enhance system sensitivity, data analytics, and integration with emerging technologies such as artificial intelligence and machine learning. This innovation drive is complemented by strategic partnerships and mergers aimed at expanding product portfolios and market reach. The market's growth is further propelled by the increasing demand for real-time monitoring and security solutions across various industries, including oil and gas, transportation, and infrastructure. As industries prioritize safety and operational efficiency, the adoption of DAS technology is expected to rise, reinforcing the market's competitive and innovative landscape.
Report Coverage:
The research report offers an in-depth analysis based on Fiber Type, Application and End-User Industry. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Asia Pacific DAS market will experience robust growth driven by the region's infrastructure modernization and smart city development initiatives.
- Demand for real-time monitoring solutions across oil and gas, transportation, and utilities will continue to fuel adoption.
- Integration of DAS with AI, IoT, and cloud platforms will enhance functionality and support predictive analytics.
- Expansion of 5G and fiber optic networks will create new deployment opportunities for telecom-based sensing applications.
- Increasing focus on energy security and environmental monitoring will drive government investments in DAS technologies.
- Advancements in multimode fiber technology may reduce costs and expand use in short-range, high-density environments.
- Rising concerns over perimeter and border security will accelerate deployment in defense and critical infrastructure sectors.
- Growth in regional players offering localized, cost-effective solutions will intensify competitive dynamics.
- Ongoing regulatory support and standardization efforts will streamline adoption across emerging economies.
- The market will shift toward scalable, modular DAS systems to accommodate evolving industry-specific needs.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Oil and Gas Infrastructure Monitoring
Asia Pacific countries are investing heavily in oil and gas exploration and distribution, driving demand for DAS systems to monitor pipelines and wellbores for leaks and operational efficiency. The technology's ability to provide real-time, long-distance monitoring is critical for safety and regulatory compliance in these sectors.
Smart Infrastructure and Urbanization Initiatives
Rapid urbanization and government-backed smart city projects across the region are fueling the adoption of DAS for infrastructure monitoring. DAS enables continuous, real-time feedback on the structural health of bridges, tunnels, and transportation systems, supporting resilient and intelligent urban development.
Integration with AI, IoT, and Cloud Platforms
The convergence of DAS with artificial intelligence, IoT, and cloud computing is enhancing predictive maintenance and anomaly detection capabilities. This integration allows industries to automate responses and optimize operations, making DAS a key enabler of digital transformation in Asia Pacific.
Rising Security and Surveillance Needs
Increasing threats to critical infrastructure and public safety are prompting governments and enterprises to deploy DAS for perimeter, border, and transportation security. The technology's high-resolution detection over long distances provides a cost-effective and reliable solution for real-time surveillance.
Telecom and 5G Network Expansion
The rollout of 5G and expansion of fiber optic networks in Asia Pacific are creating new opportunities for DAS deployment, particularly in telecom infrastructure monitoring. Telecom operators are leveraging DAS to detect external disturbances and ensure network reliability, further driving market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Asia Pacific Distributed Acoustic Sensing Market?
What factors are driving the growth of the Asia Pacific Distributed Acoustic Sensing Market?
What are the key segments within the Asia Pacific Distributed Acoustic Sensing Market?
What are some challenges faced by the Asia Pacific Distributed Acoustic Sensing Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Country
- 1.2.1 China
- 1.2.2 India
- 1.2.3 Japan
- 1.2.4 South Korea
- 1.2.5 Australia
- 1.2.6 Southeast Asia
- 1.2.7 Rest of Asia Pacific
- 1.3 By Fiber Type
- 1.3.1 Single-Mode Fiber
- 1.3.2 Multimode Fiber
- 1.4 By Application
- 1.4.1 Pipeline Monitoring
- 1.4.2 Transportation Monitoring
- 1.4.3 Border and Perimeter Security
- 1.4.4 Infrastructure Monitoring
- 1.4.5 Others
- 1.5 By End-User Industry
- 1.5.1 Oil & Gas
- 1.5.2 Defense and Security
- 1.5.3 Transportation
- 1.5.4 Utilities
- 1.5.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 190.20 million → 2032: USD 520.21 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Asia Pacific Distributed Acoustic Sensing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Asia Pacific Distributed Acoustic Sensing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Asia Pacific Distributed Acoustic Sensing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Asia Pacific Distributed Acoustic Sensing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Asia Pacific Distributed Acoustic Sensing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Asia Pacific Distributed Acoustic Sensing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Asia Pacific Distributed Acoustic Sensing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Asia Pacific Distributed Acoustic Sensing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 190.20 million → 2032: USD 520.21 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Asia Pacific Distributed Acoustic Sensing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Country - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 China
- 12.3.7.2 India
- 12.3.7.3 Japan
- 12.3.7.4 South Korea
- 12.3.7.5 Australia
- 12.3.7.6 Southeast Asia
- 12.3.7.7 Rest of Asia Pacific
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Fiber Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Single-Mode Fiber
- 12.4.7.2 Multimode Fiber
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Pipeline Monitoring
- 12.5.7.2 Transportation Monitoring
- 12.5.7.3 Border and Perimeter Security
- 12.5.7.4 Infrastructure Monitoring
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By End-User Industry - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Oil & Gas
- 12.6.7.2 Defense and Security
- 12.6.7.3 Transportation
- 12.6.7.4 Utilities
- 12.6.7.5 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Asia Pacific Distributed Acoustic Sensing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Asia Pacific Distributed Acoustic Sensing Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Country-Level Shares, 2024
- 14.2 Country Market Size Comparison, 2024
- 14.3 Country Market Forecasts, 2024-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 Asia Pacific Distributed Acoustic Sensing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Asia Pacific Distributed Acoustic Sensing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 AP Sensing GmbH
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Bandweaver Technologies
- 18.4 Silixa Ltd.
- 18.5 Omnisens SA
- 18.6 Fotech Solutions Ltd.
- 18.7 OptaSense (QinetiQ Group)
- 18.8 Schlumberger Limited
- 18.9 Baker Hughes Company
- 18.10 OFS Fitel LLC
- 18.11 Hifi Engineering Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

