
Market Overview:
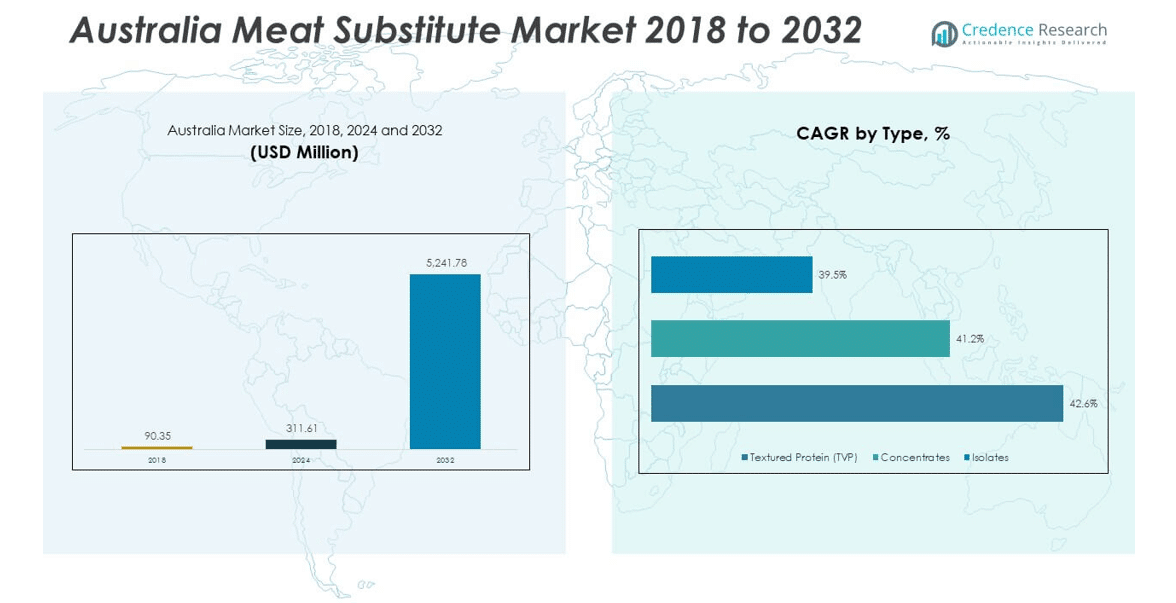
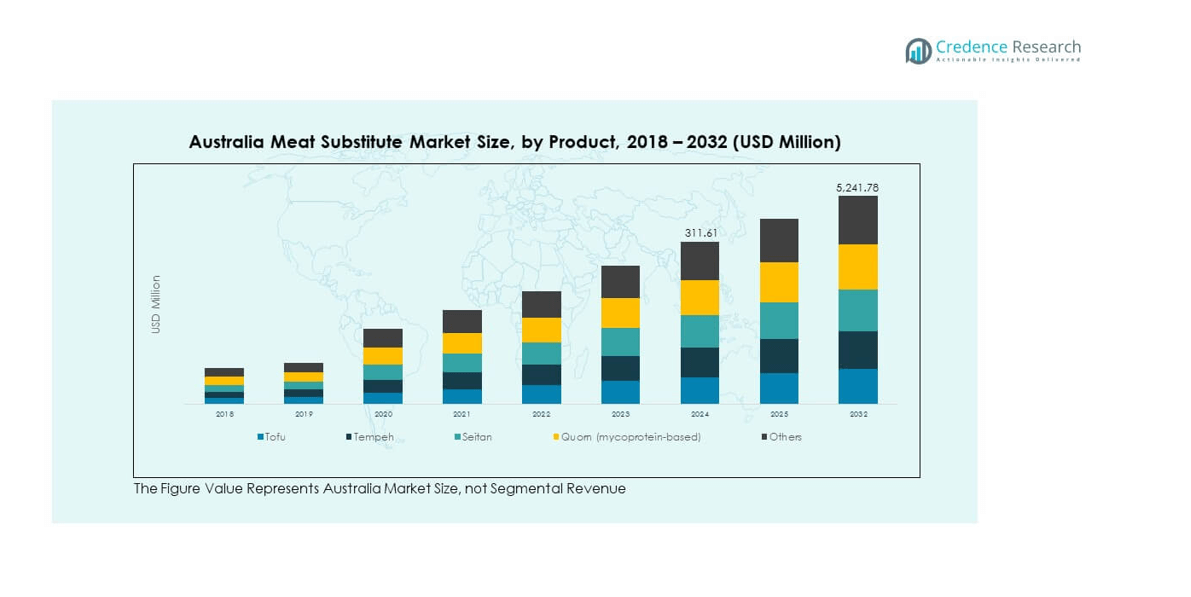
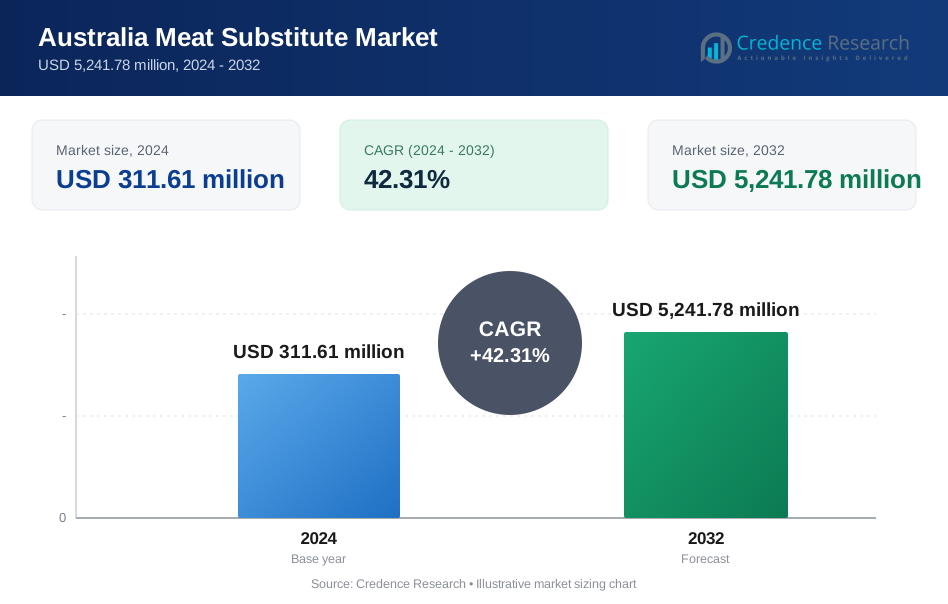
The Australia Meat Substitute Market size was valued at USD 90.35 million in 2018 to USD 311.61 million in 2024 and is anticipated to reach USD 5,241.78 million by 2032, at a CAGR of 42.31% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Australia Meat Substitute Market Size 2024 | USD 311.61 million |
| Australia Meat Substitute Market, CAGR | 42.31% |
| Australia Meat Substitute Market Size 2032 | USD 5,241.78 million |
Rising consumer demand for sustainable and healthier diets drives strong adoption of meat substitutes in Australia. The market is supported by growing awareness of animal welfare, environmental concerns, and the rising number of flexitarian and vegan consumers. Food manufacturers invest in product innovation, focusing on better taste, texture, and nutritional value to match traditional meat. Expanding retail availability and the influence of international plant-based food trends are further accelerating acceptance across urban households and younger demographics.
Geographically, demand for meat substitutes is concentrated in metropolitan regions like Sydney, Melbourne, and Brisbane, where consumer awareness and disposable incomes are higher. Emerging adoption is visible in semi-urban and regional areas, supported by expanding distribution networks and increasing access to plant-based options. The influence of global food brands and local startups is broadening reach, while cultural openness to dietary diversity strengthens future growth across the country.
Market Insights:
- The Australia Meat Substitute Market was valued at USD 90.35 million in 2018, reached USD 311.61 million in 2024, and is projected to hit USD 5,241.78 million by 2032, growing at a CAGR of 42.31%.
- Eastern Australia accounted for 48% of the market in 2024 due to strong urban demand, while Southern Australia held 28% share supported by retail penetration, and Western Australia contributed 15% share led by Perth’s urban consumers.
- Northern Australia, with 9% share, is the fastest-growing region, driven by tourism, rising foodservice adoption, and online retail expansion.
- By product, tofu and tempeh together contributed nearly 35% of the 2024 market, supported by established consumer familiarity and consistent household use.
- Quorn (mycoprotein-based) and seitan represented close to 30% share in 2024, highlighting their rising acceptance as innovative and protein-rich alternatives.
Market Drivers:
Rising Health Consciousness and Dietary Shifts
Consumers in Australia are increasingly adopting healthier diets with reduced meat intake. The growing awareness of cholesterol, obesity, and cardiovascular risks is influencing food preferences. Plant-based proteins are being accepted as alternatives that support wellness goals. Health-conscious millennials and Gen Z are driving this transition with strong purchasing power. The Australia Meat Substitute Market benefits from government campaigns encouraging balanced nutrition. Food brands are leveraging health claims like high protein and low fat to attract attention. It strengthens the market’s appeal to long-term dietary planners.
- For instance, The growing awareness of cholesterol, obesity, and cardiovascular risks is influencing food preferences, and government investment of $1.5 million from 2023–2025 for clear protein labelling reflects official support for informed consumer choices in plant-based alternatives.
Environmental Concerns and Sustainability Awareness
Sustainability plays a vital role in shaping consumer decisions in Australia. Rising awareness of climate change and livestock’s carbon footprint is increasing interest in plant-based products. Urban populations with strong environmental consciousness are leading this shift. The Australia Meat Substitute Market gains momentum as sustainable lifestyles become mainstream. Local producers highlight eco-friendly production methods to build trust. Supermarkets now dedicate spaces to sustainable foods, making substitutes visible to wider audiences. It aligns consumer choices with national sustainability goals.
Innovation in Product Development and Taste
Taste and texture improvements are expanding the acceptance of meat substitutes. Early products struggled with replicating meat’s sensory appeal, but innovation has resolved this. Advanced technologies now create closer meat-like experiences in flavor and bite. The Australia Meat Substitute Market benefits as companies invest in research and development. Brands are partnering with chefs to design appealing recipes that satisfy local taste preferences. Such efforts increase consumer repeat purchases and brand loyalty. It also enhances the perception of substitutes as mainstream food options.
Expanding Retail Networks and Accessibility
Wider product availability across retail and foodservice channels supports market growth. Large supermarkets, online platforms, and specialty stores are offering extensive plant-based ranges. Quick-service restaurants in Australia are also integrating meat substitutes into menus. The Australia Meat Substitute Market benefits from convenience-driven demand across urban and semi-urban areas. Growing e-commerce penetration ensures accessibility to diverse demographics. Food delivery platforms provide further reach for substitute-based meals. It cements substitutes as everyday dining choices, driving consistent demand across the nation.
Market Trends:
Premiumisation and Diversification of Product Portfolios
Brands are shifting toward premium product offerings with gourmet features and added nutrition. Consumers in Australia are willing to pay more for superior taste and texture. The Australia Meat Substitute Market is evolving with a mix of premium plant-based burgers, sausages, and seafood alternatives. Companies introduce fortified options with vitamins and minerals to appeal to health-driven consumers. Premiumisation strengthens brand positioning in competitive spaces. It also encourages repeat consumption by delivering consistent satisfaction. Such diversification expands the perception of substitutes beyond basic meat alternatives.
- For instance, a product audit found that nutrition-related claims-particularly high protein content-were present on 60% of plant-based meat product packaging, emphasizing a focus on enhanced formulation and premium positioning.
Integration of Technology in Food Innovation
Technology adoption is accelerating product innovation in the market. Food-tech companies use precision fermentation and cellular agriculture to develop advanced substitutes. The Australia Meat Substitute Market experiences transformation with these cutting-edge technologies. Startups and established brands collaborate with labs to achieve scalable solutions. AI-driven analysis of consumer preferences aids in customizing products. This integration improves market readiness for global competition. It elevates substitutes into a modern food-tech category that aligns with Australia’s innovation ecosystem.
- For instance, in July 2025, Australia’s food safety regulator officially approved its first-ever cultivated meat product, marking a major technological achievement and broadening innovation pipelines for the sector.
Influence of Global Food Trends and Cultural Adoption
Global plant-based food trends strongly impact Australian consumption patterns. International brands expand operations in the region, influencing local food culture. The Australia Meat Substitute Market grows as diverse cuisines adopt substitutes into recipes. Cultural acceptance of Asian and Mediterranean diets enriches product integration. Migrant populations contribute to broader taste preferences in plant-based foods. Global celebrity endorsements amplify awareness and inspire younger audiences. It ensures continued demand across mainstream and niche dining experiences.
Rising Popularity of Flexitarian Lifestyles
Flexitarianism is gaining significant ground in Australia’s food culture. Consumers are reducing meat intake without committing to strict vegan diets. The Australia Meat Substitute Market is thriving as flexitarians form the largest consumer base. Flexitarian lifestyles balance traditional meals with plant-based alternatives. This trend supports high-frequency purchases across supermarkets and restaurants. Marketing campaigns highlight flexibility and choice to align with consumer mindsets. It makes substitutes appealing for both daily consumption and occasional indulgence.
Market Challenges Analysis:
High Costs and Price Sensitivity of Consumers
The relatively high cost of meat substitutes compared to traditional protein sources creates challenges. Consumers in Australia, particularly in price-sensitive demographics, hesitate to adopt substitutes regularly. The Australia Meat Substitute Market faces pressure to balance affordability with innovation. Production costs linked to advanced ingredients and technology remain a barrier. Brands struggle to scale while keeping prices competitive. Promotional discounts are often required to encourage first-time trials. It highlights the need for cost-efficient processes and sustainable price models.
Consumer Perception and Resistance to Change
Not all consumers are convinced about the taste and authenticity of substitutes. Resistance from traditional meat consumers affects adoption levels across certain groups. The Australia Meat Substitute Market must overcome skepticism with education and product sampling. Misconceptions about nutritional adequacy persist, creating hesitation among families and older demographics. Cultural attachment to traditional meat-based meals limits wider acceptance. Marketing strategies must address myths and showcase scientific backing. It remains a challenge to shift entrenched eating habits toward substitutes.
Market Opportunities:
Expansion into Foodservice and Quick-Service Channels
The growing influence of quick-service restaurants offers opportunities for substitutes to scale. Brands collaborate with major fast-food chains to introduce plant-based menu items. The Australia Meat Substitute Market benefits from consumer trial at familiar outlets. Partnerships with cafes and catering services extend reach to new demographics. Foodservice integration creates consistent exposure, driving higher acceptance levels. It also positions substitutes as convenient choices for busy urban lifestyles. It encourages mass-market adoption through regular and accessible consumption points.
Growth of Local Startups and Niche Segments
Local startups in Australia are leveraging niche positioning to attract targeted consumers. Specialized products like plant-based seafood and culturally inspired recipes gain attention. The Australia Meat Substitute Market benefits from innovation led by small agile firms. Startups experiment with local ingredients to differentiate offerings. Niche segments expand the category beyond mainstream substitutes. It fosters a competitive landscape that drives continuous product diversification. It opens pathways for long-term growth supported by regional creativity and consumer alignment.
Market Segmentation Analysis:
By Type
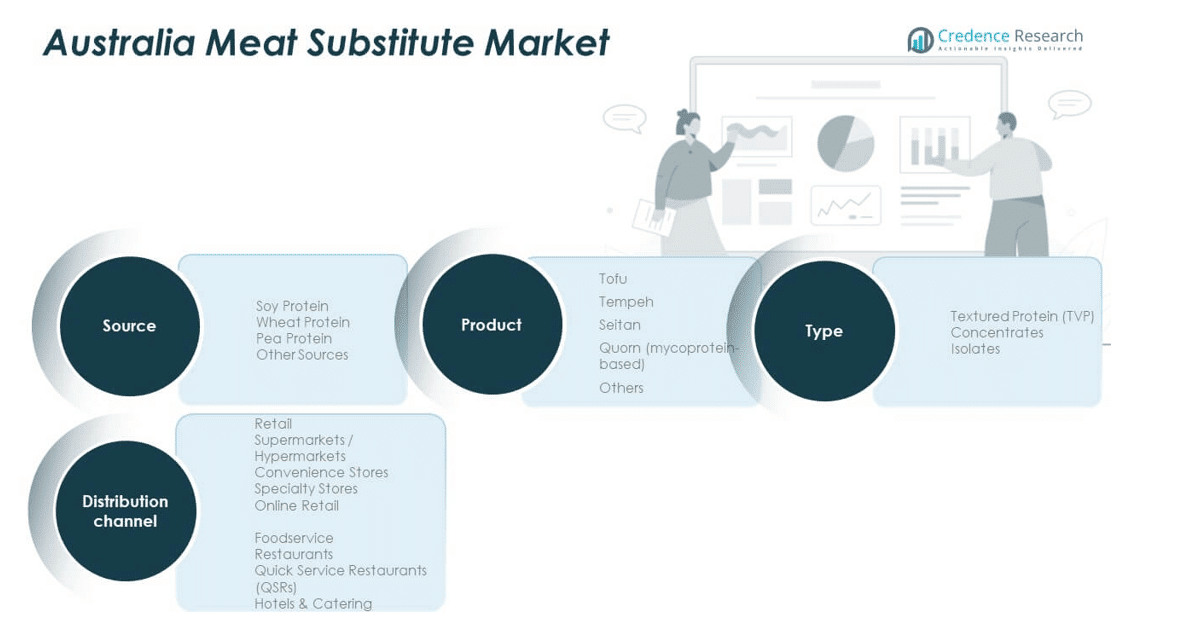
The Australia Meat Substitute Market is segmented into textured protein (TVP), concentrates, and isolates. TVP holds a strong share due to its affordability and versatility in processed foods. Isolates dominate premium applications, providing high protein and neutral flavor for innovative products. Concentrates serve as cost-effective options across mainstream consumption, supporting growth in mass-market categories. It reflects the balance between affordability and innovation in driving demand.
By Source
Soy protein leads the market because of its wide availability and established use in plant-based products. Wheat protein contributes significantly in bakery-inspired substitutes with elastic texture benefits. Pea protein is gaining traction for its allergen-friendly profile and nutritional quality. Other sources, including rice and chickpea, expand variety for consumers seeking novel alternatives. It strengthens consumer choice across multiple dietary preferences.
- For instance, Wheat protein, valued for its texture-enhancing properties, figures prominently in bakery and prepared foods, while pea protein is gaining recognition for being allergen-friendly and nutritious with growing prevalence in fitness and supplement products.
By Product
Tofu and tempeh remain traditional categories with consistent demand across households. Seitan continues to attract consumers looking for dense, protein-rich meat alternatives. Quorn, based on mycoprotein, shows increasing popularity in Australia for its unique positioning. Other products, including plant-based seafood, are emerging with innovation-driven appeal. It highlights strong diversification in consumer options.
By Distribution Channel
Retail dominates sales, with supermarkets and hypermarkets acting as primary distribution points. Convenience stores and specialty stores expand regional penetration, while online retail accelerates growth through accessibility. Foodservice adoption grows rapidly, led by restaurants and quick service restaurants introducing plant-based menu options. Hotels and catering services integrate substitutes to align with consumer dietary preferences. It secures substitutes a mainstream presence across retail and dining ecosystems.
Segmentation:
By Type
- Textured Protein (TVP)
- Concentrates
- Isolates
By Source
- Soy Protein
- Wheat Protein
- Pea Protein
- Other Sources
By Product
- Tofu
- Tempeh
- Seitan
- Quorn (Mycoprotein-Based)
- Others
By Distribution Channel
- Retail
- Supermarkets / Hypermarkets
- Convenience Stores
- Specialty Stores
- Online Retail
- Foodservice
- Restaurants
- Quick Service Restaurants (QSRs)
- Hotels & Catering
Regional Analysis:
Eastern Australia – Leading Market Share
Eastern Australia dominates the Australia Meat Substitute Market with nearly 48% share, driven by large metropolitan hubs like Sydney, Melbourne, and Brisbane. These cities host a high concentration of health-conscious consumers and early adopters of plant-based diets. Rising disposable incomes and growing awareness of sustainability boost product acceptance in this region. Supermarkets and specialty stores allocate more shelf space to meat substitutes, strengthening availability. Foodservice operators also integrate substitutes into menus, reflecting strong urban demand. It establishes Eastern Australia as the core growth engine for the market.
Southern and Western Australia – Growing Adoption
Southern Australia accounts for around 28% share, led by Adelaide’s increasing consumer interest in healthier food choices. The region shows rising retail penetration, with specialty stores and local startups offering diverse substitute options. Western Australia holds 15% market share, driven by demand in Perth and surrounding urban centers. Strong influence of global food trends and cultural diversity in these areas accelerates product experimentation. Consumers are gradually shifting from niche purchases to mainstream adoption. It highlights expanding opportunities in both southern and western regions.
Northern Australia – Emerging Opportunities
Northern Australia represents nearly 9% of the Australia Meat Substitute Market, with adoption at an early stage compared to other regions. Limited distribution networks and smaller urban populations currently restrain growth. Rising tourism in cities like Darwin, however, encourages hotels and restaurants to include meat substitutes in their offerings. Online platforms are helping bridge accessibility gaps, making substitutes available to wider demographics. The increasing presence of national foodservice chains expands exposure across the north. It creates future opportunities for sustained market penetration in the region.
Key Player Analysis:
- v2food
- Fable Food Co.
- Nexba (plant-based category expansion)
- Funky Fields (Australia presence, though Danish origin)
- Unreal Co.
- Made With Plants
- Veef (Cale & Daughters)
- Delicious
- Harvest B
- PlantAsia Foods
Competitive Analysis:
The Australia Meat Substitute Market is highly competitive, with both local and international players driving innovation. It is shaped by companies such as v2food, Fable Food Co., Unreal Co., Made With Plants, and Veef, which focus on localized offerings to capture consumer trust. Global entrants like Funky Fields and Quorn expand variety and influence through established branding. Partnerships with retailers and quick-service restaurants strengthen market penetration, while startups emphasize niche categories like plant-based seafood and culturally inspired recipes. Intense competition is pushing continuous improvements in taste, nutrition, and pricing strategies. It encourages companies to differentiate through sustainability, marketing campaigns, and diversified product portfolios that meet evolving consumer demand.
Recent Developments:
- Made With Plants, under parent company Cale & Daughters, continues to supply vegan cheese and meat alternatives to Woolworths and Coles. In September 2025, PlantAsia Foods launched new high-protein plant-based burgers, further diversifying the ready-to-eat meat substitute range in Australian supermarkets.
- In August 2025, v2food completed the acquisition of US-based Daring Foods to expand its global reach, particularly in the US market. In parallel, v2food entered a strategic partnership with Japan’s Ajinomoto for developing next-generation, clean protein products with a focus on taste, nutrition, and affordability.
- In June 2024, Nexba launched the Nexba Better Soda and PACE rapid hydration drink (created in partnership with Australian cricket captain Pat Cummins), both of which are zero-sugar and positioned under a clean-label plant-based promise.
Report Coverage:
The research report offers an in-depth analysis based on type, source, product, and distribution channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising health-conscious lifestyles will continue to boost demand for meat substitutes in Australia.
- Retail chains will expand shelf space dedicated to plant-based protein products.
- Foodservice adoption will grow as restaurants and QSRs integrate substitutes into menus.
- Local startups will diversify offerings with culturally tailored products and niche categories.
- Innovation in taste and texture will increase consumer acceptance and repeat purchases.
- Online channels will strengthen as digital retail expands across metropolitan and semi-urban areas.
- Sustainability goals will encourage brands to adopt eco-friendly production and packaging practices.
- Collaborations between food-tech companies and retailers will accelerate new product launches.
- Premium product positioning will attract consumers seeking high-quality nutrition and gourmet experiences.
- Regional penetration in Northern and Western Australia will expand as distribution networks strengthen.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Health Consciousness and Dietary Shifts
Australian consumers are increasingly seeking healthier diets with reduced meat intake, driven by concerns over cholesterol, obesity, and cardiovascular risks. This shift is especially pronounced among millennials and Gen Z, who are adopting plant-based proteins as part of wellness-focused lifestyles.
Environmental Concerns and Sustainability Awareness
Growing awareness of climate change and the environmental impact of livestock farming is motivating consumers to choose plant-based meat substitutes. Urban populations, in particular, are prioritizing sustainable food choices, and brands are leveraging eco-friendly production methods to build trust.
Innovation in Product Development and Taste
Advancements in food technology have significantly improved the taste and texture of meat substitutes, making them more appealing to mainstream consumers. Companies are investing in R&D and collaborating with chefs to create products that closely mimic traditional meat, driving repeat purchases.
Expanding Retail Networks and Accessibility
The increasing availability of meat substitutes across supermarkets, specialty stores, online platforms, and foodservice channels is making these products more accessible to a wider demographic. This expanded distribution is accelerating adoption in both urban and regional areas.
Influence of Global Food Trends and Flexitarian Lifestyles
International plant-based food trends and the rise of flexitarian diets are shaping Australian consumption patterns. The influx of global brands and the growing number of consumers seeking to reduce, but not eliminate, meat intake are broadening the market’s appeal and driving sustained growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Australia Meat Substitute Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Australia Meat Substitute Market projected to grow between 2024 and 2032?
Which Australia Meat Substitute Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Australia Meat Substitute Market?
Who are the leading companies in the Australia Meat Substitute Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Textured Protein (TVP)
- 1.2.2 Concentrates
- 1.2.3 Isolates
- 1.3 By Source
- 1.3.1 Soy Protein
- 1.3.2 Wheat Protein
- 1.3.3 Pea Protein
- 1.3.4 Other Sources
- 1.4 By Product
- 1.4.1 Tofu
- 1.4.2 Tempeh
- 1.4.3 Seitan
- 1.4.4 Quorn (Mycoprotein-Based)
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 311.61 million → 2032: USD 5,241.78 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Meat Substitute Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Meat Substitute Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Australia Meat Substitute Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Australia Meat Substitute Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Meat Substitute Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Meat Substitute Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Meat Substitute Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Meat Substitute Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 311.61 million → 2032: USD 5,241.78 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Meat Substitute Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Textured Protein (TVP)
- 12.3.7.2 Concentrates
- 12.3.7.3 Isolates
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Source - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Soy Protein
- 12.4.7.2 Wheat Protein
- 12.4.7.3 Pea Protein
- 12.4.7.4 Other Sources
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Tofu
- 12.5.7.2 Tempeh
- 12.5.7.3 Seitan
- 12.5.7.4 Quorn (Mycoprotein-Based)
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Meat Substitute Geographic Market Outlook, 2024-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 Australia Meat Substitute Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Australia Meat Substitute Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 v2food
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Fable Food Co.
- 17.4 Nexba
- 17.5 Funky Fields
- 17.6 Unreal Co.
- 17.7 Made With Plants
- 17.8 Veef (Cale & Daughters)
- 17.9 Delicious
- 17.10 Harvest B
- 17.11 PlantAsia Foods
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

