
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Australia Robotic Laser Cutting Market Size 2023 | USD 56.13 Million |
| Australia Robotic Laser Cutting Market, CAGR | 12.56% |
| Australia Robotic Laser Cutting Market Size 2032 | USD 164.26 Million |
Market Overview
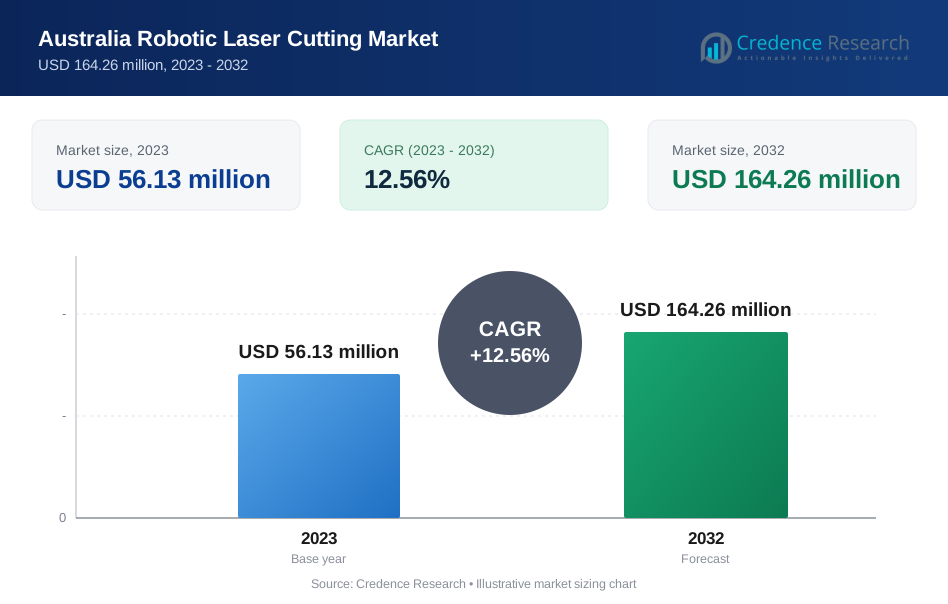
The Australia robotic laser cutting market is projected to grow from USD 56.13 million in 2023 to an estimated USD 164.26 million by 2032, with a compound annual growth rate (CAGR) of 12.56% from 2024 to 2032. This substantial growth reflects the increasing adoption of advanced manufacturing technologies and automation across various industries in the country.
Key drivers fueling the growth of the Australia robotic laser cutting market include the rising demand for precision and efficiency in manufacturing processes and the ongoing trend towards Industry 4.0. Additionally, the need to reduce production costs and improve product quality is prompting manufacturers to invest in robotic laser cutting technologies. Innovations in laser technology and the integration of artificial intelligence in robotic systems are further enhancing market growth.
Geographically, the market is experiencing robust growth across major regions in Australia, including New South Wales, Victoria, and Queensland. These regions are witnessing increased investments in manufacturing and infrastructure development, which in turn is driving the demand for robotic laser cutting systems. Key players in the market, such as TRUMPF, Mitsubishi Electric, and FANUC, are focusing on strategic partnerships and product innovations to strengthen their market presence and cater to the evolving needs of Australian manufacturers.
Market Drivers
Increasing Adoption of Automation in Manufacturing
The relentless pursuit of efficiency and productivity in manufacturing processes is a primary driver for the adoption of robotic laser cutting technologies in Australia. For instance, it’s estimated that 46 percent of current work activities in Australia could be automated by 2030. Manufacturers across various sectors, including automotive, aerospace, and electronics, are increasingly integrating automation to streamline operations and enhance output quality. Robotic laser cutting systems offer unparalleled precision and speed, significantly reducing production time and minimizing human error. The adoption of these systems aligns with the broader trend of Industry 4.0, which emphasizes the integration of digital technologies into manufacturing. By leveraging robotic laser cutting, manufacturers can achieve consistent and high-quality results, which are crucial in maintaining competitive advantage in a global market. Additionally, the capability of these systems to handle complex geometries and materials with high precision makes them indispensable in industries requiring meticulous detail and high standards of accuracy.
Technological Advancements and Innovations
Continuous advancements in laser technology and robotics are significantly contributing to the growth of the Australia robotic laser cutting market. Innovations such as fiber lasers, which offer higher efficiency and lower maintenance compared to traditional CO2 lasers, are becoming increasingly prevalent. These advancements enhance the performance and capabilities of robotic laser cutting systems, making them more versatile and efficient. Moreover, the integration of artificial intelligence (AI) and machine learning (ML) into robotic systems is revolutionizing the way laser cutting is performed. AI and ML algorithms enable predictive maintenance, optimize cutting paths, and improve overall system efficiency. For example, advanced sensors and cameras enable real-time monitoring and adjustment, ensuring that the cutting process remains accurate even if there are minor variations in the material or environment. Such technological innovations not only enhance the operational capabilities of robotic laser cutting systems but also reduce downtime and operational costs, thereby making them more attractive to manufacturers.
Growing Demand for Customized and High-Precision Products
In today's market, there is a growing demand for customized products and components with high precision. This demand spans various industries, including consumer electronics, medical devices, and automotive parts. For instance, the average American family spends upwards of $1,700 on clothes per year, and more and more of those consumers are buying their clothing online. Robotic laser cutting systems are uniquely positioned to meet these needs due to their ability to deliver precise cuts with minimal tolerances and their flexibility in handling different materials and thicknesses. Manufacturers are increasingly recognizing the benefits of robotic laser cutting in producing bespoke products that meet specific customer requirements. The precision offered by these systems ensures that components fit perfectly within larger assemblies, reducing the need for additional processing and adjustments. This capability is particularly crucial in sectors like aerospace and medical devices, where precision and accuracy are paramount.
Economic and Operational Efficiency
The economic benefits associated with robotic laser cutting systems are a significant driver for their adoption. These systems reduce labor costs by automating the cutting process, allowing manufacturers to allocate human resources to more strategic and value-added tasks. Furthermore, robotic laser cutting systems operate with high speed and precision, reducing material waste and optimizing the use of raw materials. Operational efficiency is another critical factor. Robotic laser cutting systems can operate continuously with minimal supervision, significantly increasing production throughput. This efficiency translates into higher output and faster turnaround times, which are essential in meeting market demand and maintaining competitive edge. Additionally, the ability to program and reprogram these systems for different cutting tasks enhances their versatility and adaptability, allowing manufacturers to respond swiftly to changing market conditions and customer needs.
Market Trends
Integration of Advanced Technologies
The integration of advanced technologies is a prominent trend shaping the Australia robotic laser cutting market. One of the most significant advancements is the incorporation of artificial intelligence (AI) and machine learning (ML) into robotic laser cutting systems. For instance, AI algorithms can analyze data from sensors, predict potential issues, and adjust the cutting parameters accordingly. These technologies enable predictive maintenance, optimize cutting paths, and enhance overall system efficiency. By leveraging AI and ML, manufacturers can achieve higher precision and productivity, reduce downtime, and lower operational costs. Moreover, the use of Internet of Things (IoT) sensors and real-time data analytics is becoming more prevalent, allowing for continuous monitoring and optimization of the laser cutting process. This trend not only improves the quality and consistency of cuts but also enables manufacturers to implement more sophisticated and efficient production strategies. Additionally, the shift towards fiber laser technology is gaining momentum. Fiber lasers offer numerous advantages over traditional CO2 lasers, including higher efficiency, lower maintenance requirements, and the ability to cut a broader range of materials. This transition is driven by the need for more versatile and reliable cutting solutions that can meet the demands of various industries. The adoption of these advanced technologies is propelling the Australia robotic laser cutting market forward, making it more competitive and capable of meeting the evolving needs of modern manufacturing.
Growing Focus on Sustainability
Sustainability is becoming an increasingly important consideration in the Australia robotic laser cutting market. Manufacturers are under pressure to reduce their environmental footprint and adopt more eco-friendly practices. Robotic laser cutting systems contribute to sustainability efforts by minimizing material waste and optimizing energy consumption. These systems enable precise cutting, which reduces the amount of scrap material generated during the manufacturing process. For instance, the Robotics Australia Group is building a sustainable robotics industry, nurturing a comprehensive robotics ecosystem. Furthermore, the high efficiency of modern laser technologies, such as fiber lasers, translates into lower energy usage compared to traditional cutting methods. The focus on sustainability extends to the materials used in the manufacturing process. There is a growing trend towards using recyclable and eco-friendly materials that can be efficiently processed with robotic laser cutting systems. This shift not only aligns with environmental regulations and corporate social responsibility goals but also enhances the overall efficiency and cost-effectiveness of production. By embracing sustainable practices and technologies, the Australia robotic laser cutting market is positioning itself to meet the demands of environmentally conscious consumers and stakeholders, ensuring long-term growth and competitiveness.
Market Restraints and Challenges
High Initial Investment Costs
One of the primary restraints in the Australia robotic laser cutting market is the high initial investment costs associated with purchasing and integrating advanced robotic laser cutting systems. These systems require significant capital outlay, not only for the equipment itself but also for the necessary infrastructure modifications, such as enhanced power supply, cooling systems, and safety measures. Small and medium-sized enterprises (SMEs) often find it challenging to justify these costs, particularly if their production volumes do not warrant such a substantial investment. Additionally, the cost of training personnel to operate and maintain these sophisticated systems can further strain financial resources. While the long-term operational savings and efficiency gains can offset these initial costs, the upfront financial burden remains a significant barrier to adoption for many potential users in the market.
Technical Complexity and Maintenance Challenges
The technical complexity of robotic laser cutting systems poses another major challenge in the Australia market. These systems are highly sophisticated, integrating advanced technologies such as artificial intelligence, machine learning, and IoT. Operating and maintaining such systems requires specialized skills and knowledge, which can be a hurdle for many manufacturers. There is often a steep learning curve associated with mastering the programming and operation of these systems, necessitating extensive training and expertise. Moreover, maintenance of robotic laser cutting systems can be challenging due to their intricate components and the need for regular calibration and servicing to ensure optimal performance. Downtime resulting from maintenance issues or technical malfunctions can disrupt production schedules and negatively impact productivity. The availability of skilled technicians and the cost of ongoing maintenance can also pose significant challenges, particularly for SMEs. As the market evolves, addressing these technical and maintenance challenges through enhanced training programs and support services will be crucial to facilitating broader adoption and maximizing the benefits of robotic laser cutting technologies.
Market Segmentation Analysis
By Type
CO2 laser cutting machines, fiber laser cutting machines, and YAG cutting machines each play distinct roles in the Australian robotic laser cutting market. CO2 laser cutting machines are widely utilized for their ability to cut a range of materials including metals, plastics, wood, and glass, making them suitable for heavy-duty tasks in automotive and metal fabrication industries. However, they require regular maintenance and incur higher operational costs. Fiber laser cutting machines are gaining popularity due to their superior efficiency, lower maintenance needs, and versatility. They use fiber optics for high precision and fast cutting speeds, particularly excelling in cutting metals such as stainless steel, aluminum, and copper, which benefits automotive and aerospace applications. YAG (Yttrium Aluminum Garnet) cutting machines, though less common, are favored for applications requiring high precision and fine detailing, often used in electronics and medical device manufacturing, despite their smaller market share.
By Application
In the Australia robotic laser cutting market, CO2 laser cutting machines are extensively used due to their capability to cut a wide range of materials, including metals, plastics, wood, and glass, making them suitable for heavy-duty applications in sectors like automotive and metal fabrication. However, they require frequent maintenance and entail higher operational costs compared to other types. Fiber laser cutting machines are increasingly popular for their superior efficiency, lower maintenance needs, and versatility. Utilizing fiber optics, these machines offer enhanced precision and faster cutting speeds, making them ideal for metals such as stainless steel and aluminum, and are favored in industries like automotive and aerospace. YAG (Yttrium Aluminum Garnet) cutting machines, though less common, are preferred for applications requiring high precision and intricate detailing, such as in electronics and medical device manufacturing. Despite their specialized use, YAG machines hold a relatively small market share.
Segments
Based on Treatment Type
- Alcohol Addiction Treatment
- Tobacco/Nicotine Addiction Treatment
- Opioid Addiction Treatment
- Other Substances Addiction Treatment
Based on Drug Type
- Bupropion
- Varenicline
- Acamprosate
- Disulfiram
- Naltrexone
- Methadone
- Buprenorphine
- Nicotine Replacement Products
- Others
Based on Treatment Center
- Outpatient Treatment Centers
- Residential Treatment Centers
- Inpatient Treatment Centers
Based on Distribution Channel
- Hospitals Pharmacies
- Medical Stores
- Others
Based on Region
- New South Wales
- Victoria
- Queensland
Regional Analysis
New South Wales (35%):
New South Wales (NSW) holds the largest market share in the Australia robotic laser cutting market, accounting for approximately 35% of the total market. This dominance is primarily due to the region's robust manufacturing sector, which includes a high concentration of automotive, aerospace, and metal fabrication industries. Sydney, the economic hub of NSW, attracts substantial investments in advanced manufacturing technologies, including robotic laser cutting systems. The state government's supportive policies and incentives for technological innovation further bolster the market growth in this region. Additionally, the presence of major manufacturing facilities and a skilled workforce enhances the adoption of robotic laser cutting technologies.
Victoria (28%):
Victoria is the second-largest contributor to the Australia robotic laser cutting market, holding a market share of around 28%. The state's industrial landscape is characterized by a strong presence of automotive manufacturing and metalworking industries, which are significant users of robotic laser cutting systems. Melbourne, the capital of Victoria, is a key center for manufacturing excellence and innovation. The state's strategic focus on advanced manufacturing and its initiatives to foster research and development in laser cutting technologies are pivotal in driving market growth. Victoria's commitment to maintaining its competitive edge in manufacturing ensures continued investments in cutting-edge technologies.
Key players
- ABB Ltd.
- AMADA Co. Ltd.
- BLM S.P.A.
- Daihen Corp.
- FANUC Corp.
- HGLaser Engineering Co. Ltd.
- Jenoptik AG
- KUKA AG
- Laser Photonics
- Staubli International AG
- Suresh Indu Lasers Pvt Ltd.
- VP Synergic Weld Solutions Pvt Ltd.
- Yaskawa Electric Corp.
Competitive Analysis
The Australia robotic laser cutting market is highly competitive, featuring prominent global and regional players. Companies like ABB Ltd., FANUC Corp., and KUKA AG lead the market with their extensive portfolios of advanced robotic solutions and strong customer support networks. AMADA Co. Ltd. and BLM S.P.A. are notable for their innovative laser cutting technologies and strong presence in the metal fabrication industry. HGLaser Engineering Co. Ltd. and Laser Photonics emphasize technological advancements and cost-effective solutions, catering to various industrial needs. Jenoptik AG and Daihen Corp. focus on integrating cutting-edge laser technologies and automation. Local players like Suresh Indu Lasers Pvt Ltd. and VP Synergic Weld Solutions Pvt Ltd. contribute to the market by offering customized and region-specific solutions. Staubli International AG and Yaskawa Electric Corp. further enhance market competition with their high-precision robotic systems and extensive global reach. The competitive landscape is characterized by continuous innovation, strategic partnerships, and a focus on meeting diverse customer requirements.
Recent Developments
In August 2022, Bystronic Inc. formed a partnership with Nano Lock Security to create specialized security solutions for sheet and tube metal cutting, bending, and automation systems. This collaboration aims to address critical challenges in downstream industries, driving market growth and increasing demand for advanced laser cutting technologies. By integrating enhanced security measures, this partnership ensures the protection and efficiency of cutting and automation systems, thereby providing significant value to manufacturers and enhancing the overall industry standards.
In April 2022, Mazak Optonics Corp. introduced the Optiplex 3015 Neo 15kw, a state-of-the-art 2D fiber laser-cutting system. This system is acclaimed for its precise control over beam shape and diameter, enabling versatile cutting capabilities for various materials and configurations. The Optiplex 3015 Neo enhances cutting speed and quality, making it suitable for a wide range of applications. This innovation reflects Mazak's commitment to advancing laser cutting technology and meeting diverse industrial needs with superior performance.
In May 2022, Monport Tech Inc. launched the Monport laser, known for its excellent customer service, affordability, and high-quality output. This laser engraving machine, tested thoroughly before its market release, has proven its reliability and efficiency by successfully engraving various valuable materials. Monport Tech's dedication to quality and customer satisfaction is evident in this product, which is poised to meet the needs of a wide range of engraving applications.
In May 2021, Yamazaki Mazak Corporation unveiled the FG-220, a precision cutting machine designed to accurately process structural materials, including round, square, rectangular, and open profiles. The FG-220 offers several advantages, such as reduced setup time, faster lead times, decreased dependency on operators, and minimized floor space requirements. This innovation underscores Mazak's focus on enhancing efficiency and precision in cutting operations, catering to the needs of various industrial sectors.
In March 2023, ABB announced its enhanced commitment to the US market, one of its largest customer bases for robotics. The company commenced construction on the expansion of its North American robotics headquarters and manufacturing facility in Auburn Hills, Michigan. This expansion aims to bolster ABB's production capabilities and support the growing demand for advanced robotics solutions across various industries in the region.
In July 2023, ABB Robotics launched four new models and 22 variants in its robot range. These new robots offer up to 20% energy savings, payload capacities ranging from 150kg to 310kg, and reach capabilities from 2.5m to 3.2m. The introduction of these models helps customers enhance resilience across industries such as automotive, general manufacturing, foundry, food and beverage, and logistics. ABB's innovative robots provide improved efficiency and versatility, meeting the evolving needs of modern manufacturing environments.
Market Concentration and Characteristics
The Australia robotic laser cutting market exhibits a moderate level of concentration, characterized by a mix of established global players and emerging local firms. Major international companies like ABB Ltd., FANUC Corp., and KUKA AG dominate the market with their advanced technologies and extensive distribution networks. These players leverage their significant resources and innovation capabilities to maintain a competitive edge. Concurrently, local companies such as Suresh Indu Lasers Pvt Ltd. and VP Synergic Weld Solutions Pvt Ltd. contribute to market dynamics by offering tailored solutions and competitive pricing. The market is characterized by a focus on technological advancements, such as high-precision laser cutting and automation integration, driving continuous innovation and improving operational efficiency across various industrial applications.
Report Coverage
The research report offers an in-depth analysis based on Treatment Type, Drug Type, Treatment Center, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Australian robotic laser cutting market will continue to evolve with advancements in laser technology, improving precision, speed, and versatility across diverse materials.
- As industries seek to enhance productivity and reduce costs, the adoption of robotic laser cutting systems is expected to rise, particularly in the automotive and aerospace sectors.
- The integration of robotic laser cutting systems with Industry 4.0 technologies, including IoT and AI, will enable smarter manufacturing processes and real-time data analytics.
- Innovations in laser technology and automation will drive significant improvements in cutting efficiency, reducing waste and operational downtime for manufacturers.
- The scope of applications for robotic laser cutting will broaden, with increased use in sectors such as medical device manufacturing and electronics, beyond traditional industries.
- Growing emphasis on sustainability will lead to the development of eco-friendly robotic laser cutting systems, reducing energy consumption and environmental impact.
- Future systems will offer greater customization and flexibility, allowing manufacturers to adapt to changing market demands and produce a wider range of products.
- Increased investment in local manufacturing capabilities will bolster the growth of the robotic laser cutting market in Australia, fostering innovation and job creation.
- The market will experience intensified competition as both global and local players innovate and offer diverse solutions to meet the evolving needs of different industries.
- Government initiatives and policies aimed at promoting advanced manufacturing technologies will further support the growth and adoption of robotic laser cutting systems in Australia.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth rate of the Australia robotic laser cutting market?
What are the primary drivers of growth in the Australia robotic laser cutting market?
Which regions in Australia are contributing most to the market growth?
What challenges are faced by the Australia robotic laser cutting market?
How is the market addressing sustainability concerns?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Australia Robotic Laser Cutting Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Selected Country & Subnational Markets Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Australia Robotic Laser Cutting Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 56.13 million → 2032: USD 164.26 million)
- 2.1.2 Volume & Revenue – National Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Australia Robotic Laser Cutting Segmentation Snapshot
- 2.2.1 Market Split by Subnational Area – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Australia Robotic Laser Cutting Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Australia Robotic Laser Cutting Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage Across Domestic Markets
- 3.2 Australia Robotic Laser Cutting Drivers
- 3.3 Australia Robotic Laser Cutting Restraints & Challenges
- 3.4 Australia Robotic Laser Cutting Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Australia Robotic Laser Cutting Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Australia Robotic Laser Cutting Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 National & Subnational Regulatory Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Australia Robotic Laser Cutting category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Australia Robotic Laser Cutting Attractiveness Analysis
- 4.1.1 By Subnational Area – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Subnational Area – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Subnational Area – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Domestic Market Opportunity Scorecards
- 4.5.1 Priority Domestic Market 1
- 4.5.2 Priority Domestic Market 2
- 4.5.3 Priority Domestic Market 3
- 4.5.4 Priority Domestic Market 4
Note: Domestic market scorecards cover relevant states, provinces, territories, cities, or economic zones within the selected country. Numbered entries are populated with market names suited to the national administrative structure and research scope. Geographic share tables use one consistent, nonoverlapping set of areas.
Chapter 5. Australia Robotic Laser Cutting Cross-Border Trade & Market Access Analysis
- 5.1 National Trade & International Partner Overview
- 5.1.1 Export Value by Destination Country (2023)
- 5.1.2 Export Volume by Destination Country (2023) (Where Applicable)
- 5.1.3 Import Value by Source Country (2023)
- 5.1.4 Import Volume by Source Country (2023) (Where Applicable)
- 5.1.5 National & Partner-Country Trade Balances (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Destination Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 National Participation in Regional Trade & Economic Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter covers international trade relevant to Australia Robotic Laser Cutting in the selected country. Exports are analyzed by destination and imports by source. Domestic interregional flows are excluded from international trade totals. Goods, services, and digital offerings use applicable classifications; volume and route analyses apply only where meaningful.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Australia Robotic Laser Cutting Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Multinational, National & Local Player Dynamics
- 6.2 Australia Robotic Laser Cutting Share Analysis – 2023
- 6.2.1 National Revenue Share by Company
- 6.2.2 National Volume Share by Company (Volume Where Applicable)
- 6.2.3 Company Revenue Share by Subnational Area
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 National Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Australia Robotic Laser Cutting Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Revenue Exposure Across Domestic Markets
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Australia Robotic Laser Cutting (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Australia Robotic Laser Cutting
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Australia Robotic Laser Cutting – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Subnational Market Analysis – Country Overview
- 8.1 Domestic Geographic Market Overview
- 8.1.1 Subnational Volume Share (Where Applicable)
- 8.1.2 Subnational Revenue Share
- 8.1.3 Market Volume by Subnational Area (Where Applicable)
- 8.1.4 Market Revenue by Subnational Area
- 8.1.5 Subnational Forecasts Through 2032
- 8.2 Cross-Area Segment Analysis Within the Country
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. Australia Robotic Laser Cutting – Priority Domestic Market 1
Chapter 10. Australia Robotic Laser Cutting – Priority Domestic Market 2
Chapter 11. Australia Robotic Laser Cutting – Priority Domestic Market 3
Chapter 12. Australia Robotic Laser Cutting – Priority Domestic Market 4
Chapter 13. Australia Robotic Laser Cutting Company Profiles
- 13.1 [Company 01]
- 13.1.1 Company Overview
- 13.1.2 Key Management Personnel
- 13.1.3 Products & Services Portfolio
- 13.1.4 Financial Performance
- 13.1.5 Domestic Market Focus & Local Operating Presence
- 13.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 14. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 15. Research Methodology
- 15.1 Research Framework & Philosophy
- 15.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 15.3 Data Modeling – National Market Sizing & Subnational Allocation
- 15.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 15.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 15.6 Quality Control – Four-Layer Validation Framework
- 15.7 Limitations & Standard Assumptions
- 15.8 Disclaimer
