
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Australia Digital Oilfield Solutions Market Size 2024 | USD 233.63 million |
| Australia Digital Oilfield Solutions Market, CAGR | 7.54% |
| Australia Digital Oilfield Solutions Market Size 2032 | USD 417.79 million |
Market Overview
The Australia Digital Oilfield Solutions Market is projected to grow from USD 233.63 million in 2024 to an estimated USD 417.79 million by 2032, reflecting a compound annual growth rate (CAGR) of 7.54% from 2025 to 2032. This growth is driven by the increasing adoption of digital technologies aimed at enhancing operational efficiency and optimizing production processes in the oil and gas sector.
Key drivers of this market include the need to boost production from mature oilfields and the integration of advanced technologies such as the Internet of Things (IoT), artificial intelligence, and big data analytics. These technologies facilitate real-time monitoring, predictive maintenance, and data-driven decision-making, contributing to improved efficiency and reduced operational costs.
Geographically, Australia presents significant opportunities for digital oilfield solutions, with major players such as Chevron Corporation, Santos Ltd., Exxon Mobil Corporation, SLB, Origin Energy Limited, Baker Hughes Company, Shell PLC, BP PLC, and Beach Energy Limited actively operating in the region. The adoption of digital solutions is expected to be particularly pronounced in offshore operations, where complex environments benefit from enhanced monitoring and optimization capabilities.
Market Insights
- The Australian Digital Oilfield Solutions Market is projected to grow from USD 233.63 million in 2024 to USD 417.79 million by 2032, with a CAGR of 7.54% from 2025 to 2032.
- The Global Digital Oilfield Solutions Market is projected to grow from USD31,374.00 million in 2024 to USD 54,897.18 million by 2032, with a CAGR of 7.24% from 2025 to 2032.
- The increasing adoption of IoT, AI, and big data analytics is transforming oilfield operations, leading to better operational efficiency and predictive maintenance.
- Digital solutions are enabling oil and gas companies to optimize production, reduce costs, and enhance real-time monitoring across various operations.
- High initial investment costs and concerns around data security and privacy pose significant challenges to the widespread adoption of digital solutions in the industry.
- Offshore oilfields in regions like Western Australia are driving market growth, as digital technologies enhance monitoring and optimize operations in complex environments.
- Western Australia leads in market share due to its offshore oilfields, followed by Queensland, with its growing focus on onshore oilfield optimization.
- Environmental sustainability is a key focus, with digital solutions enabling better emissions monitoring, energy optimization, and compliance with strict environmental regulations.
Market Drivers
Enhancement of Safety and Risk Management
Safety is a paramount concern in the oil and gas industry, especially in remote and offshore operations where the risks are higher. Digital oilfield solutions are integral to improving safety protocols and minimizing risks. Through the implementation of advanced monitoring systems and real-time data analytics, companies can track equipment conditions and identify potential safety hazards, thus reducing the likelihood of accidents and improving safety outcomes. For example, digital solutions can monitor pressure levels, temperature fluctuations, and equipment wear, all of which can indicate the risk of equipment failure or unsafe working conditions. By providing early warning systems and automated alerts, these solutions enable operators to take swift corrective action, preventing accidents before they occur. Furthermore, digital systems ensure compliance with safety regulations and industry standards, thereby mitigating legal and financial risks. In Australia’s vast oilfield landscape, where resources are spread across remote areas, digital solutions improve safety management while ensuring the smooth functioning of operations.
Regulatory Pressure for Environmental Sustainability
Environmental concerns and regulatory pressures are driving the oil and gas industry to adopt more sustainable practices. Australia’s oil and gas sector is increasingly focused on reducing its environmental footprint, and digital oilfield solutions play a crucial role in this transformation. By improving efficiency, digital solutions help reduce waste, optimize resource usage, and minimize environmental impacts. For instance, digital solutions allow for real-time monitoring of emissions and waste, enabling operators to quickly detect and address environmental issues. These technologies also help optimize energy consumption in drilling and production processes, further reducing the environmental impact of operations. Additionally, by ensuring that operations are running at optimal efficiency, digital oilfield solutions contribute to more sustainable resource extraction. With growing pressure from regulatory bodies and stakeholders to adopt environmentally friendly practices, the Australian oil and gas industry is increasingly relying on digital solutions to meet sustainability goals while staying compliant with evolving environmental regulations.
Technological Advancements in Digital Solutions
The rapid advancement of digital technologies such as the Internet of Things (IoT), big data analytics, cloud computing, and artificial intelligence (AI) plays a significant role in driving the growth of the Australia Digital Oilfield Solutions Market. These technologies enable the automation and optimization of various processes within the oil and gas industry, such as predictive maintenance, production optimization, and real-time monitoring. By integrating these digital tools, oilfield operators can enhance their operational efficiency, reduce downtime, and increase overall production capabilities. For instance, Saudi Aramco has utilized thousands of IoT sensors at their Khurais oil field to monitor and forecast oil well behavior, resulting in significant reductions in power consumption and maintenance costs, as well as decreased inspection times. Similarly, Shell has reported a 40% reduction in equipment failures by using AI-powered predictive maintenance systems that analyze sensor data to predict potential breakdowns days in advance. These examples highlight how IoT improves communication between devices and systems within an oilfield, while AI-powered tools forecast potential failures, enabling preventive actions to minimize unplanned downtime. The continuous evolution of these technologies and their application to oilfield operations ensures that the Australian market will continue to adopt and integrate these innovations for improved results.
Increased Demand for Operational Efficiency and Cost Reduction
In a highly competitive and price-sensitive market, the oil and gas industry in Australia faces immense pressure to increase operational efficiency and reduce costs. The need for sustainable and cost-effective solutions is driving the adoption of digital oilfield technologies. By implementing these advanced digital solutions, oil and gas operators can streamline their operations, reduce energy consumption, and optimize resource allocation, leading to significant cost savings. Digital oilfield solutions enable enhanced monitoring and control of processes, from drilling and production to distribution. For instance, companies can optimize drilling operations in real-time by leveraging immediate sensor feedback to avoid issues like drill bit wear or unexpected geological formations that slow operations. Additionally, BP saves $10 million annually by using AI-driven predictive maintenance systems that detect potential equipment failures early, preventing costly downtimes. Automation further reduces human error while improving accuracy and productivity. By analyzing vast amounts of data, digital solutions also help identify opportunities for further optimization. This focus on improving operational efficiency while reducing costs is essential for the survival of oilfield operators in Australia’s increasingly challenging market environment.
Market Trend
Cloud-Based Solutions for Data Management and Collaboration
Cloud technology is becoming increasingly important in the Australian digital oilfield solutions market due to its ability to enhance data management, storage, and collaboration among various stakeholders. Cloud-based platforms allow oil and gas companies to securely store vast amounts of operational data in a centralized location, making it easily accessible to authorized personnel at any time and from any location. The use of cloud-based systems facilitates better collaboration among different teams, such as field operations, data scientists, engineers, and management, enabling more efficient sharing of information and insights. Cloud platforms also support the integration of diverse digital tools and applications, which can be used to analyze data, manage assets, and perform complex simulations in real time. This centralized approach enhances decision-making by providing a more holistic view of operations, improving overall management and coordination. Moreover, cloud solutions allow for better scalability and flexibility, enabling oil and gas companies to adapt to changing market demands and operational requirements without significant investment in on-premise infrastructure. The increased use of cloud technology also supports remote operations, which is critical in the context of Australia’s vast and often remote oil and gas fields.
Focus on Sustainability and Environmental Impact Reduction
Sustainability and environmental concerns are playing an increasingly important role in shaping the Australian digital oilfield solutions market. As environmental regulations become stricter and pressure from stakeholders for sustainable practices grows, oil and gas companies are turning to digital solutions to help reduce their environmental impact. Digital oilfield technologies, such as real-time emissions monitoring systems, are enabling companies to track and reduce their carbon footprint. These systems provide insights into gas emissions and other environmental factors, allowing operators to identify potential leaks, inefficiencies, and non-compliance issues in real time. Additionally, the data collected can be used to optimize energy usage, thereby reducing waste and improving resource efficiency. Furthermore, digital solutions help minimize the environmental impact of drilling and production activities by optimizing processes and reducing the need for manual intervention. For example, automation systems ensure that drilling operations are carried out in a controlled and efficient manner, which reduces the likelihood of spills, accidents, and other environmental hazards. The integration of sustainable practices with digital solutions is increasingly seen as an essential component of responsible oilfield management, aligning with both regulatory requirements and the growing expectations of investors and consumers for environmentally conscious practices.
Integration of Advanced Technologies for Real-Time Monitoring and Optimization
One of the most significant trends in the Australian digital oilfield solutions market is the increasing integration of advanced technologies such as the Internet of Things (IoT), artificial intelligence (AI), machine learning (ML), and big data analytics into oilfield operations. These technologies are enhancing the ability to monitor and optimize oil and gas production in real time. IoT plays a critical role in connecting various devices, sensors, and equipment across oilfields, allowing for continuous monitoring and the collection of vast amounts of data. For instance, oil and gas companies can collect and analyze data from over 1,000 sensors across a single oilfield using IoT sensors and AI algorithms. This enables real-time monitoring, allowing operators to predict potential equipment failures, optimize well performance, and reduce downtime by up to 30 days annually. The analyzed data provides actionable insights, helping operators make informed decisions quickly. Real-time monitoring tools also provide visibility into operations, enabling operators to respond promptly to changing conditions while improving efficiency. These technologies not only enhance operational performance but also offer precise control over drilling, production, and post-production processes. With data-driven decision-making becoming increasingly important, these digital solutions are integral to improving productivity, reducing operational costs, and extending the lifespan of oilfield assets in Australia.
Automation of Processes to Improve Efficiency and Safety
Automation is another significant trend transforming the Australian digital oilfield solutions market. By incorporating automation into various stages of oil and gas production, companies are reducing manual interventions, lowering human error risks, and increasing safety levels in remote or hazardous environments. Automated systems such as robotic process automation (RPA) and advanced control systems enable more precise operations of oilfield equipment. For example, RPA can automate over 500 transactions per month in joint venture accounting processes, significantly reducing manual errors while allowing personnel to focus on higher-value tasks. Additionally, automation helps optimize drilling activities, manage production operations, and maintain equipment with minimal human intervention. AI-powered predictive maintenance systems further enhance efficiency by continuously monitoring equipment and detecting anomalies in real time. For instance, these systems can schedule maintenance for over 200 pieces of equipment annually, minimizing unplanned downtime and preventing costly breakdowns. This trend not only streamlines operations but also enhances safety by reducing human exposure to hazardous conditions in offshore or remote oilfields. The ability to improve decision-making while reducing operational risks makes automation a dominant force driving efficiency in Australia’s digital oilfield solutions market.
Market Challenges
High Initial Investment and Implementation Costs
One of the key challenges facing the Australian digital oilfield solutions market is the high initial investment and implementation costs associated with adopting advanced digital technologies. While these solutions offer long-term operational efficiency and cost savings, the upfront costs required for hardware, software, and system integration can be significant, particularly for smaller operators or those with limited capital. Additionally, training personnel to operate and manage these advanced technologies requires time and resources, further adding to the overall investment. For many companies, particularly those operating in remote or offshore regions, the economic feasibility of adopting digital oilfield solutions can be hindered by these high initial costs. Smaller operators may struggle to justify the expenditure without immediate returns on investment, which can delay the widespread adoption of digital technologies in the sector. For instance, BP's adoption of real-time drilling optimization tools in the Permian Basin demonstrated how digital solutions can reduce well construction costs significantly over time. However, smaller operators often lack the financial flexibility to make such investments upfront. Overcoming these cost-related barriers requires careful planning and a clear understanding of the long-term benefits digital solutions provide in terms of operational efficiency, safety, and sustainability.
Data Security and Privacy Concerns
As digital oilfield solutions rely heavily on data collection, storage, and real-time monitoring, concerns around data security and privacy remain a significant challenge. The Australian oil and gas industry is increasingly vulnerable to cyber-attacks and data breaches, which could compromise sensitive operational data, intellectual property, and safety protocols. With the integration of cloud computing, IoT, and AI, oilfield operators must ensure robust cybersecurity measures to protect critical infrastructure from potential cyber threats. Data privacy concerns are also heightened with the increasing volume of information generated by digital solutions. The management and storage of such vast amounts of data raise concerns about compliance with local and international data privacy regulations. Oil and gas companies must invest in secure systems and work closely with cybersecurity experts to mitigate risks and ensure that all digital solutions are compliant with data protection standards. Addressing these challenges is critical for fostering trust in digital technologies and ensuring the long-term success of digital oilfield operations in Australia.
Market Opportunities
Growth in Remote and Offshore Oilfield Operations
A significant market opportunity for the Australian digital oilfield solutions market lies in the expansion of remote and offshore oilfield operations. Australia's vast geography, including its extensive offshore oilfields, presents unique challenges that can be effectively addressed through digital solutions. Technologies such as real-time monitoring, predictive maintenance, and automated drilling systems are essential in remote operations, where accessibility and environmental conditions make traditional methods difficult and costly. By leveraging digital technologies, operators can optimize performance, reduce downtime, and enhance safety, which is crucial in harsh and isolated environments. As oil and gas companies seek to enhance operational efficiency and minimize risks in these remote areas, the demand for advanced digital oilfield solutions is expected to grow.
Increasing Focus on Environmental Sustainability
The growing emphasis on environmental sustainability presents a major opportunity in the Australian digital oilfield solutions market. Digital technologies play a critical role in reducing the environmental impact of oilfield operations by enabling more efficient resource use, monitoring emissions, and optimizing energy consumption. With heightened regulatory pressures and a broader industry focus on reducing carbon footprints, operators are turning to digital solutions to achieve sustainability goals. For instance, real-time monitoring systems can track environmental parameters such as gas leaks and emissions, while optimization algorithms can minimize energy waste. This focus on sustainability is not only driven by regulatory requirements but also by the increasing demand from consumers, investors, and stakeholders for environmentally responsible practices in the oil and gas sector, positioning digital oilfield solutions as a key enabler of sustainable operations.
Market Segmentation Analysis
By Solution
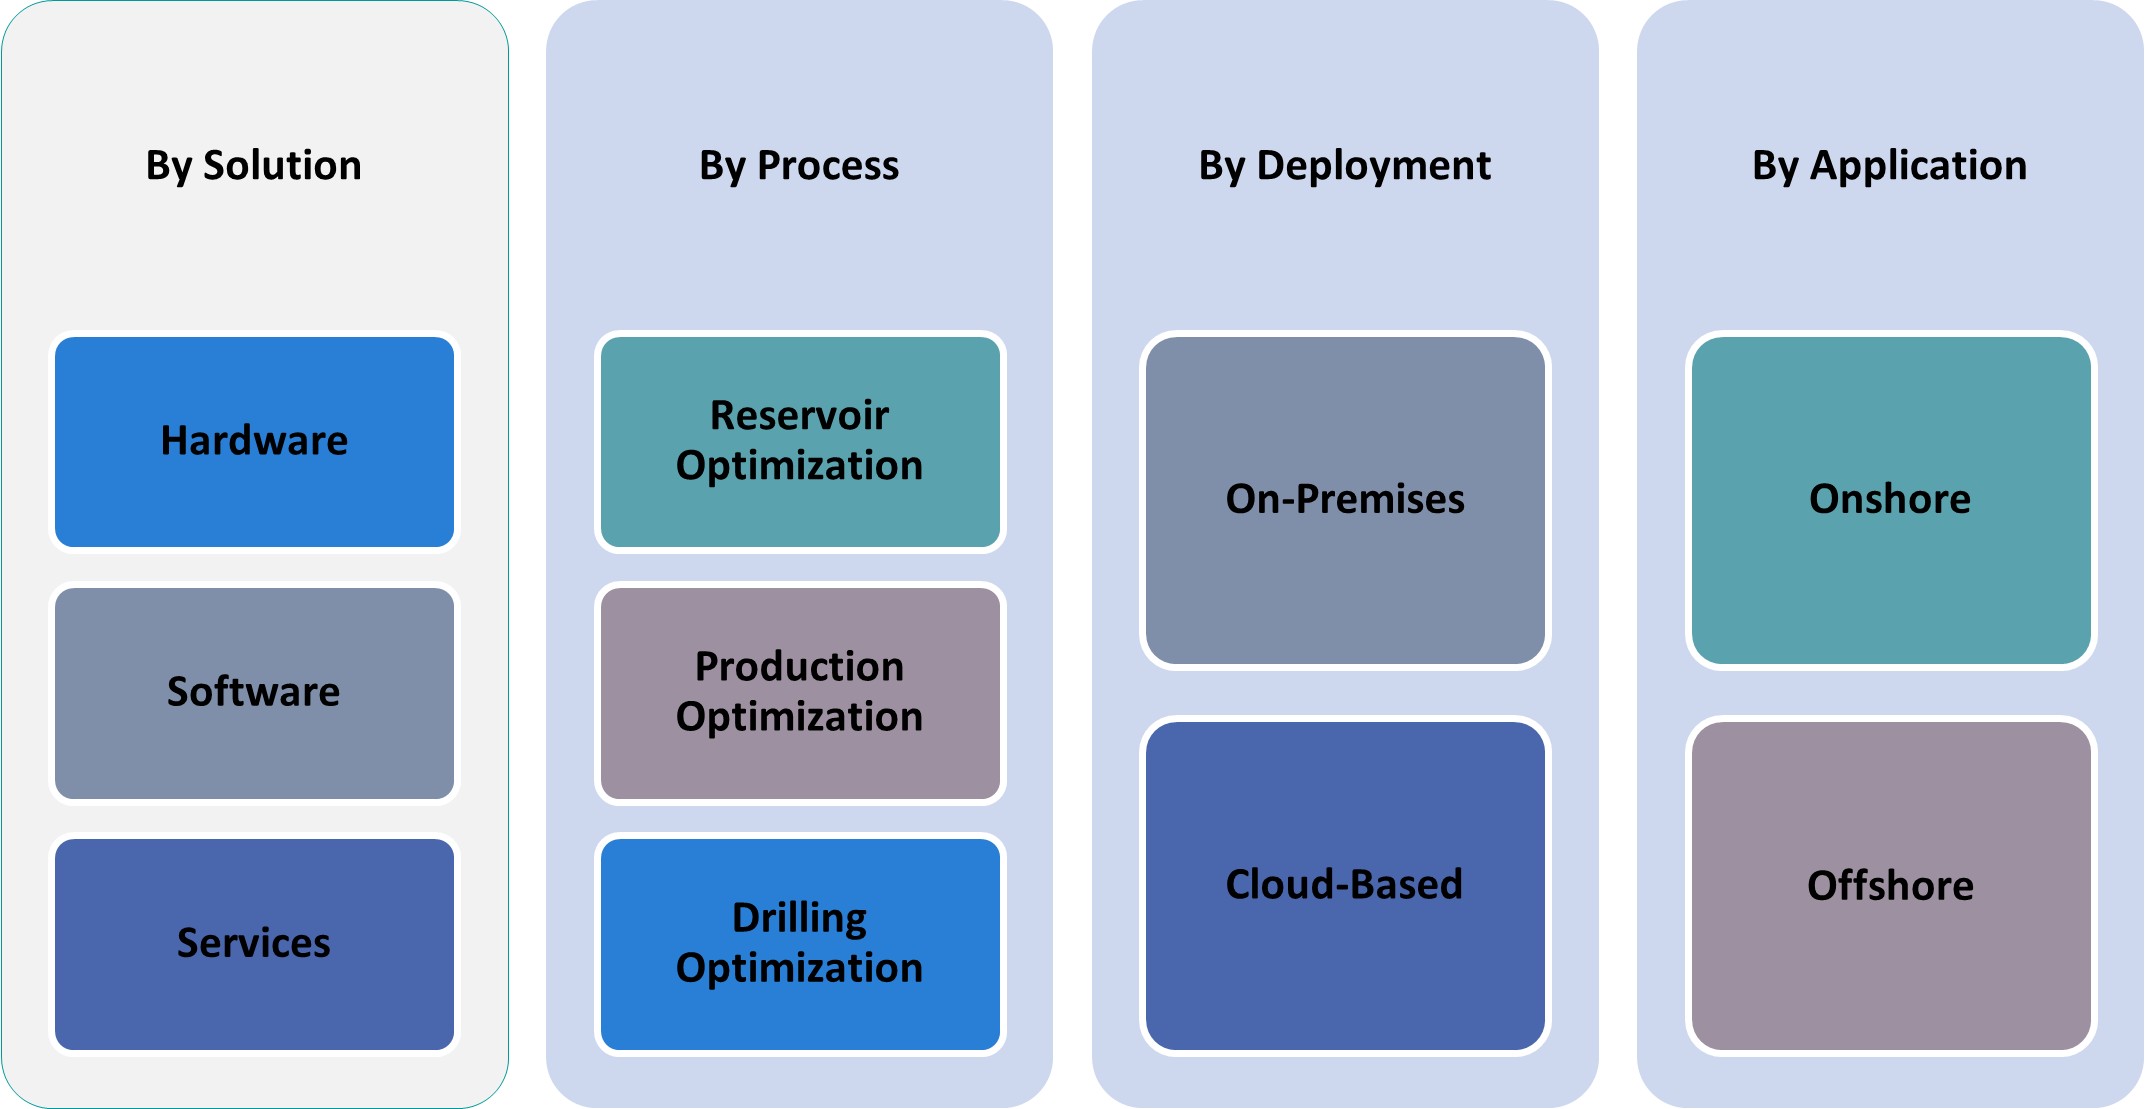
The market is divided into three primary segments based on the solution type: Hardware, Software, and Services. Hardware includes the physical infrastructure and equipment essential for the implementation of digital oilfield solutions, such as sensors, data acquisition systems, control systems, and automation tools. The hardware segment plays a vital role in the physical monitoring and management of oilfield operations. Software solutions are central to data management, analysis, and decision-making processes in digital oilfield operations. This segment includes advanced analytics, AI-driven software, cloud-based platforms, and data management systems that support predictive maintenance, production optimization, and overall operational efficiency. Services encompasses consulting, installation, maintenance, and support services. These services ensure seamless integration of digital solutions within existing infrastructure and operations while offering ongoing support to maximize operational effectiveness.
By Application
The Australian market is also segmented based on the application of digital oilfield solutions, which are primarily classified into Onshore and Offshore. Onshore oilfields represent the majority of oil production in Australia, where digital oilfield solutions are used for optimizing drilling, production, and resource management processes. These solutions help address challenges such as asset management, environmental sustainability, and operational efficiency. Offshore oilfields, which involve complex and often hazardous environments, benefit greatly from digital solutions that enable real-time monitoring, predictive maintenance, and automation. These solutions enhance safety and efficiency, which are paramount in offshore operations.
Segments
Based on Solution
- Hardware
- Software
- Services
Based on Application
- Onshore
- Offshore
Based on Process
- Reservoir Optimization
- Production Optimization
- Drilling Optimization
Based on Deployment
- On-Premises
- Cloud-Based
Based on Region
- Western Australia
- Queensland
- New South Wales
- Victoria
- South Australia
Regional Analysis
Western Australia (45%)
Western Australia is home to the majority of the country’s offshore oilfields, such as the North West Shelf and the Browse Basin. This region plays a critical role in Australia’s oil production and is a key driver for the growth of digital oilfield solutions. With its complex offshore environment, the adoption of digital technologies such as real-time monitoring, predictive maintenance, and automation has become crucial to optimizing production and ensuring safety. Western Australia holds a significant market share of approximately 45% of the Australian Digital Oilfield Solutions Market. The increasing demand for efficient operations in harsh offshore environments and the push toward reducing environmental impact are key factors contributing to the adoption of advanced digital technologies in this region.
Queensland (30%)
Queensland is one of the major onshore oil-producing regions in Australia, with significant reserves in the Surat Basin and Bowen Basin. The region has seen steady growth in the adoption of digital oilfield solutions to enhance productivity, optimize reservoir management, and improve operational safety. The Queensland market represents around 30% of the total market share. Operators in this region are increasingly leveraging digital solutions such as AI-driven analytics and IoT-enabled sensors to streamline drilling and production processes. Additionally, Queensland’s focus on reducing the environmental impact of oilfield operations is fueling the demand for digital solutions that help optimize energy consumption and emissions monitoring.
Key players
- Schlumberger Limited
- Baker Hughes Company
- Halliburton Company
- Weatherford International plc
- Siemens AG
- ABB Ltd.
- Honeywell International Inc.
- Yokogawa Electric Corporation
- Tata Consultancy Services (TCS)
- Infosys Limited
Competitive Analysis
The Australian Digital Oilfield Solutions Market is highly competitive, with key players offering a wide range of advanced technologies and solutions. Schlumberger, Baker Hughes, and Halliburton dominate the market, leveraging their extensive experience and global reach to deliver innovative digital solutions for reservoir optimization, production enhancement, and predictive maintenance. Companies like Weatherford and Siemens are also significant contributors, focusing on automation, real-time monitoring, and cloud-based services to improve operational efficiency. ABB Ltd. and Honeywell stand out in providing integrated control systems and AI-driven solutions. Emerging players such as Tata Consultancy Services (TCS) and Infosys bring digital transformation capabilities, emphasizing software solutions and analytics. With a broad portfolio of services, each player tailors its offerings to the unique challenges of onshore and offshore oilfield operations, fostering healthy competition and continuous innovation in the market.
Recent Developments
- In March 2025, Schneider Electric unveiled the One Digital Grid Platform, an AI-powered platform designed to enhance grid resiliency and efficiency. This platform is set to be available later in 2025. The company announced a $700 million investment plan in the U.S. to enhance energy infrastructure and AI capabilities.
- In April 2025, ABB India delivered integrated automation and digital solutions for IndianOil's cross-country pipeline network, enhancing efficiency and safety through real-time monitoring and robust cybersecurity.
- In March 2025, Kongsberg Digital participated in the IPTC 2025, focusing on digital transformation in the oil and gas sector.
- In January 2025, SAP S/4HANA Cloud was highlighted as a key enabler for a smarter, more efficient energy ecosystem in the oil and gas industry.
- In April 2025, Schlumberger (SLB) announced a partnership with Shell to deploy Petrel™ subsurface software across Shell's global assets. This collaboration aims to enhance digital capabilities and operational efficiencies through advanced AI-driven seismic interpretation workflows. This development underscores SLB's ongoing commitment to advancing subsurface digital technology and fostering strategic partnerships in the energy sector.
Market Concentration and Characteristics
The Australian Digital Oilfield Solutions Market is moderately concentrated, with a few key players such as Schlumberger, Baker Hughes, and Halliburton holding significant market share due to their extensive technological capabilities, global presence, and comprehensive service offerings. However, the market also features a growing number of regional players and emerging technology providers, such as Tata Consultancy Services and Infosys, who bring specialized expertise in software solutions, AI, and data analytics. The market is characterized by high competition in delivering integrated solutions that optimize drilling, production, and reservoir management. Players focus on offering cutting-edge technologies, such as automation, predictive maintenance, and real-time monitoring, to enhance efficiency and safety across onshore and offshore oilfields. The market's competitiveness is further driven by the increasing demand for sustainable, cost-effective solutions and regulatory pressures on reducing environmental impact, encouraging innovation and collaboration.
Report Coverage
The research report offers an in-depth analysis based on Solution, Application, Process, Deployment and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The integration of IoT technologies will continue to grow, enhancing real-time monitoring and data analytics capabilities for oilfield operations. This will lead to improved efficiency and reduced downtime across both onshore and offshore fields.
- Cloud computing will see wider adoption for data storage, management, and collaboration, offering flexibility and scalability to Australian oil and gas companies. Cloud platforms will enable remote access, fostering better decision-making and operational coordination.
- As operational efficiency becomes more crucial, predictive maintenance using AI and machine learning will gain momentum. This technology will help prevent unplanned downtime, optimizing production and reducing maintenance costs.
- Automation will be a key driver in enhancing operational safety and efficiency. Automated systems for drilling and production will minimize human intervention, reduce errors, and streamline operations in remote and offshore locations.
- Environmental sustainability will remain a primary concern, with more digital solutions focused on reducing emissions and optimizing energy consumption. Regulatory pressures will drive further adoption of technologies that ensure compliance and minimize environmental impact.
- Big data analytics will play an increasingly important role in optimizing production and resource management. Advanced analytics will offer deeper insights into operational performance, enabling data-driven decisions to maximize production and reduce costs.
- Offshore oilfields will see more investments in digital oilfield technologies to address challenges such as remote operations and harsh environmental conditions. Enhanced monitoring and automation will drive efficiency in offshore production.
- Collaborations between digital technology providers and oil and gas operators will increase. Partnerships will focus on delivering integrated solutions, combining hardware, software, and services to address industry challenges comprehensively.
- As digital technologies become more prevalent, the need for robust cybersecurity solutions will intensify. Protecting critical infrastructure and data from cyber threats will be a primary focus for industry stakeholders.
- Smaller oilfield operators will increasingly adopt digital solutions to remain competitive. With decreasing costs of technology and more accessible platforms, digital transformation will become feasible for operators of all sizes, enhancing industry-wide operational efficiency.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Enhancement of Safety and Risk Management
Digital oilfield solutions enable real-time monitoring and advanced analytics, allowing operators to identify and mitigate safety hazards quickly. This is especially critical in Australia's remote and offshore oilfields, where minimizing risk and ensuring compliance with safety regulations are top priorities.
Regulatory Pressure for Environmental Sustainability
Stricter environmental regulations and stakeholder expectations are pushing Australian oil and gas companies to adopt digital solutions that monitor emissions, optimize energy use, and ensure compliance. These technologies help operators reduce their environmental footprint and meet sustainability goals.
Technological Advancements in Digital Solutions
Rapid progress in IoT, AI, big data analytics, and cloud computing is making digital oilfield solutions more powerful and accessible. These technologies drive automation, predictive maintenance, and real-time optimization, directly improving operational efficiency and reducing downtime.
Increased Demand for Operational Efficiency and Cost Reduction
With competitive pressures and volatile oil prices, Australian operators are turning to digital solutions to streamline operations, reduce energy consumption, and optimize resource allocation. This leads to significant cost savings and improved productivity across both onshore and offshore fields.
Growth in Remote and Offshore Oilfield Operations
Australia's vast geography and significant offshore reserves create a strong need for digital solutions that can optimize performance and safety in challenging, remote environments. Digital technologies are essential for efficient, safe, and cost-effective operations in these regions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Australia Digital Oilfield Solutions Market in 2023 and 2032?
What are the key drivers of growth in the Australian digital oilfield solutions market?
How do digital oilfield solutions impact the oil and gas industry?
Who are the major players in the Australian digital oilfield solutions market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Process
- 1.2.1 Reservoir Optimization
- 1.2.2 Production Optimization
- 1.2.3 Drilling Optimization
- 1.3 By Solution
- 1.3.1 Hardware
- 1.3.2 Software
- 1.3.3 Services
- 1.4 By Deployment
- 1.4.1 On-Premises
- 1.4.2 Cloud-Based
- 1.5 By Application
- 1.5.1 Onshore
- 1.5.2 Offshore
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 233.63 million → 2032: USD 417.79 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australian Digital Oilfield Solutions Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australian Digital Oilfield Solutions Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Australian Digital Oilfield Solutions Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Australian Digital Oilfield Solutions Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australian Digital Oilfield Solutions Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australian Digital Oilfield Solutions Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australian Digital Oilfield Solutions Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australian Digital Oilfield Solutions Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 233.63 million → 2032: USD 417.79 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australian Digital Oilfield Solutions Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Process - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Reservoir Optimization
- 12.3.7.2 Production Optimization
- 12.3.7.3 Drilling Optimization
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Solution - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hardware
- 12.4.7.2 Software
- 12.4.7.3 Services
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Deployment - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 On-Premises
- 12.5.7.2 Cloud-Based
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Onshore
- 12.6.7.2 Offshore
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Australian Digital Oilfield Solutions End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australian Digital Oilfield Solutions Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australian Digital Oilfield Solutions Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Australian Digital Oilfield Solutions Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Schlumberger Limited
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Baker Hughes Company
- 18.4 Halliburton Company
- 18.5 Weatherford International plc
- 18.6 Siemens AG
- 18.7 ABB Ltd.
- 18.8 Honeywell International Inc.
- 18.9 Yokogawa Electric Corporation
- 18.10 Tata Consultancy Services (TCS)
- 18.11 Infosys Limited
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

