
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Australia Book Paper Market Size 2024 | USD 120.10 million |
| Australia Book Paper Market, CAGR | 5.05% |
| Australia Book Paper Market Size 2032 | USD 178.06 million |
Market Overview:
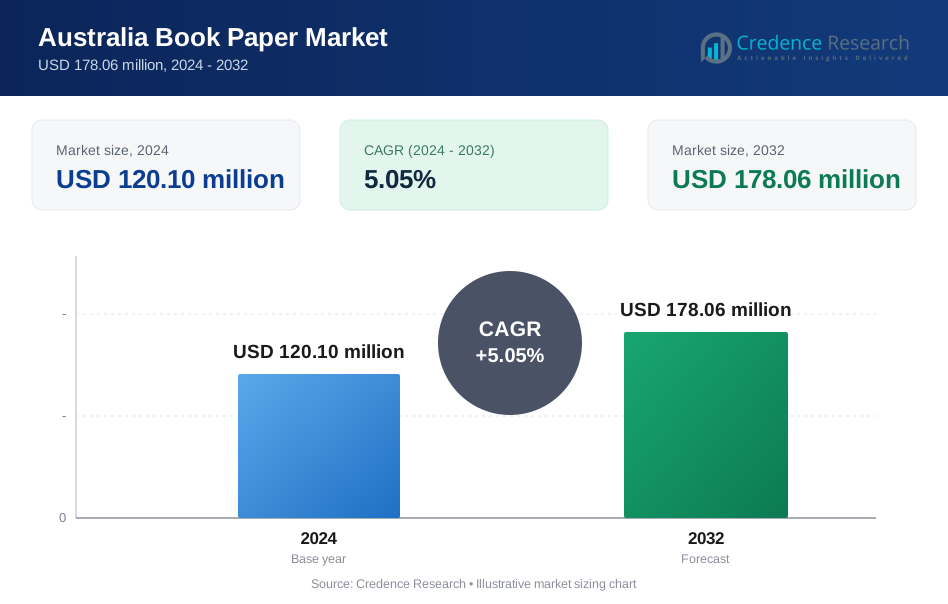
The Australia Book Paper Market is projected to grow from USD 120.10 million in 2024 to an estimated USD 178.06 million by 2032, with a compound annual growth rate (CAGR) of 5.05% from 2024 to 2032.
Several factors contribute to the expansion of the book paper market in Australia. The rise of independent and self-publishing platforms has democratized the publishing process, allowing a broader range of voices to reach the market. Additionally, there is a growing consumer preference for physical books, particularly in genres like mystery, which was the largest revenue-generating segment in 2024. The educational sector also continues to be a significant driver, with consistent demand for textbooks and academic materials. Furthermore, initiatives to support local production, such as the Australian government's $24 million pledge to the Boyer Paper Mill in Tasmania, aim to bolster domestic paper manufacturing capabilities. Rising environmental awareness is also encouraging the adoption of sustainably sourced paper, adding a new dimension to market growth.
Regionally, the book paper market's growth is influenced by both domestic and international dynamics. Domestically, Australia's commitment to supporting its paper production infrastructure, as evidenced by investments in facilities like the Boyer Paper Mill, ensures a stable supply chain for publishers. Internationally, Australia's position in the global books market, accounting for 2.0% of revenue in 2024, reflects its active participation in the broader publishing ecosystem. Urban centers like Sydney and Melbourne serve as key hubs for publishing activity, further strengthening regional demand for quality book paper. The interplay between domestic initiatives and global market trends will continue to shape the regional landscape of the book paper industry.
Market Insights:
- The Australia Book Paper Market is projected to grow from USD 120.10 million in 2024 to USD 178.06 million by 2032, registering a CAGR of 5.05%, reflecting steady growth driven by education, consumer trends, and publishing diversity.
- The Global Book Paper Market is projected to grow from USD 10,203.76 million in 2024 to USD 14,364.15 million by 2032, with a CAGR of 4.37%, driven by increasing demand for printed educational materials and books worldwide.
- The rise of self-publishing and independent authors is expanding the market base, increasing the volume of printed content and diversifying demand for different paper grades and sizes.
- Consumer preference for physical books, especially in mystery, fiction, and children’s categories, continues to support stable demand for high-quality book paper despite growing digital content alternatives.
- Government support, including the $24 million investment in Tasmania’s Boyer Paper Mill, is boosting domestic manufacturing capacity and reducing dependency on imported paper.
- The educational sector remains a dominant driver, with recurring demand from schools, universities, and training institutes ensuring consistent consumption of standard and premium paper types.
- Environmental sustainability is shaping market dynamics, as publishers and producers adopt eco-friendly practices to meet regulatory standards and consumer expectations.
- Regionally, New South Wales and Victoria account for a combined 65% of the market share, driven by dense populations, robust publishing activity, and well-established educational institutions.
Report Scope
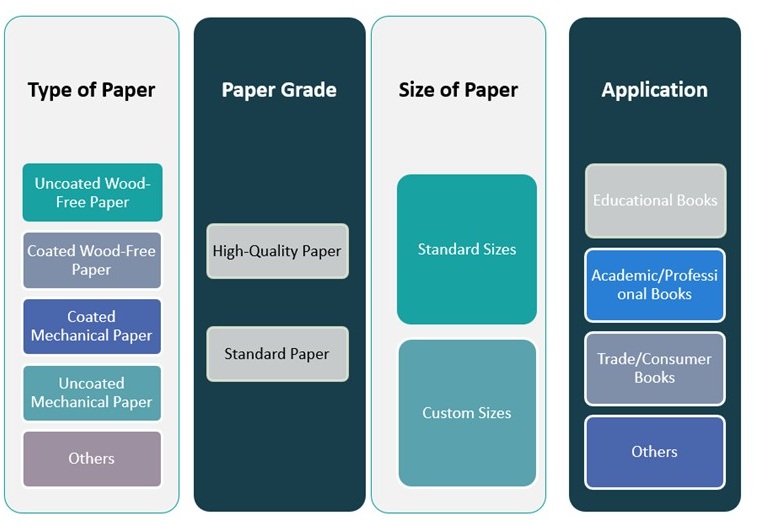
This report segments the Australia Book Paper Market as follow
Market Drivers:
Educational Sector Demand
The Australian education sector plays a foundational role in driving the demand for book paper.
For instance, the Australian Publishers Association (APA), representing more than 200 publishers responsible for over 90% of the country’s $2 billion annual book industry turnover, reports that approximately 20,000 new Australian (print and electronic) books are published each year, with many tens of thousands of international titles released in Australian editions or imported. The continued requirement for physical textbooks, workbooks, and academic reference materials sustains consistent consumption across primary, secondary, and tertiary levels. Government funding for education, combined with curriculum reforms and new syllabus rollouts, leads to recurring printing cycles and large-volume paper requirements. Furthermore, while digital adoption is growing, many institutions still emphasize the value of printed learning materials for comprehension and accessibility, reinforcing the need for durable, high-quality book paper.
Preference for Physical Books
Despite the global shift toward digital formats, a substantial portion of Australian readers continues to prefer physical books, especially in genres such as fiction, biographies, and children’s literature. The tactile experience of print, combined with the aesthetic appeal of physical libraries and collections, sustains strong consumer interest in printed publications. This trend is further supported by the growing popularity of independent bookstores and literary events across major cities, which foster a culture of reading and book ownership. For instance, Bricks-and-mortar bookstores remain popular, with 71% of respondents purchasing from physical stores sometimes or often, compared to 52% for online suppliers. As a result, publishers maintain robust print runs that directly translate into ongoing demand for quality paper.
Rise of Independent and Self-Publishing
Australia has seen a surge in independent authors and self-publishing ventures, enabled by accessible online platforms and print-on-demand services. This evolution has broadened the publishing ecosystem beyond traditional houses, bringing new voices and niche genres into the market. As more creators bypass conventional publishing routes, the frequency and volume of printed publications increase, especially in localized or regional editions that cater to specific audiences. This shift has created a stable and diversified source of demand for book paper, fueling industry resilience amid broader media transitions.
Government Support and Sustainable Production
Government initiatives to strengthen domestic paper production and reduce reliance on imports have also emerged as a critical driver. The federal government’s recent funding to upgrade Tasmania’s Boyer Paper Mill reflects a strategic commitment to bolstering local manufacturing capacity and ensuring long-term supply chain stability. In parallel, environmental regulations and growing public interest in sustainable practices are encouraging paper manufacturers to adopt eco-friendly sourcing and production methods. This alignment of policy, industry goals, and consumer expectations is helping the book paper market evolve in a direction that is both economically and environmentally sustainable, ensuring continued relevance in the years ahead.
Market Trends:
Growth of Print Subscription Models
A notable trend within the Australian book paper market is the growing popularity of print-based subscription services. Book boxes and curated subscription models have gained traction, particularly among younger demographics and niche readers who appreciate tangible literary experiences. These services often include new releases, collector editions, and themed content that promote physical book consumption. As publishers and independent sellers leverage this model to strengthen reader engagement and build recurring revenue, the demand for high-quality, aesthetically pleasing paper stock continues to rise.
Expansion of Children’s Book Segment
The children's literature segment is witnessing steady growth, reinforcing demand for durable and colorful paper varieties. Parents, educators, and libraries consistently prioritize printed materials for early literacy development, emphasizing the importance of tactile interaction and visual appeal. In 2023, children’s books accounted for over 23% of total printed book sales in Australia, indicating their substantial contribution to the overall market. Publishers are responding with innovative formats such as board books, pop-ups, and textured designs, all of which require specialized paper types that enhance user experience and product longevity.
Increased Focus on Domestic Paper Manufacturing
Rising global supply chain disruptions and import cost volatility have encouraged a renewed focus on domestic paper manufacturing. Australian mills are gradually modernizing operations to meet the evolving quality standards of the publishing industry, while also aligning with environmental benchmarks. A notable example is the $137 million AusWaste Recycling facility under construction in Queensland, which will process 220,000 tonnes of waste paper and cardboard annually into pulp for paper mills, supported by $40 million in government funding and $97 million from industry stakeholders. Investments in localized production, including recycled and FSC-certified paper lines, are enhancing the country’s self-reliance and responsiveness to market needs. This shift also supports Australian publishers in maintaining delivery timelines and controlling costs, especially in the face of unpredictable international logistics.
Integration of Sustainable Printing Practices
Sustainability continues to shape industry practices across the book printing value chain. Publishers are increasingly adopting eco-conscious printing methods, such as soy-based inks and waterless printing technologies, which align with consumer expectations for environmentally responsible products. For instance, companies like MVP Print use Forest Stewardship Council (FSC) certified paper and 100% recycled materials for book production, demonstrating a commitment to green printing. In parallel, demand is rising for paper made from renewable or recycled sources, as buyers become more selective about product origins. These trends are not only fostering innovation in book paper production but also positioning Australian publishers to compete more effectively in both domestic and export markets by showcasing their commitment to sustainability and ethical sourcing.
Market Challenges Analysis:
Digital Substitution and Changing Reading Habits
One of the primary restraints impacting the Australia book paper market is the steady rise of digital content consumption. E-books, audiobooks, and online reading platforms continue to gain popularity, particularly among younger audiences and tech-savvy consumers who prioritize convenience and portability. Educational institutions and public libraries are also expanding digital access, reducing dependency on printed materials. As digital adoption accelerates, the shift in consumer preference poses a structural challenge to sustained demand for traditional book paper formats.
Volatility in Raw Material Prices
Fluctuations in the cost of raw materials, particularly wood pulp, significantly affect the production economics of book paper. Global supply constraints, geopolitical uncertainties, and environmental regulations in pulp-producing countries often lead to unpredictable price movements. Australian paper manufacturers, especially those reliant on imported inputs, face margin pressures and difficulties in maintaining competitive pricing. These price instabilities can hinder long-term planning and discourage large-scale investment in paper production infrastructure.
Supply Chain Disruptions and Import Dependence
Australia’s reliance on imported paper products and pulp presents an ongoing logistical and operational challenge. Shipping delays, container shortages, and global trade disruptions—especially experienced during recent geopolitical tensions and the COVID-19 pandemic—have exposed vulnerabilities in the supply chain. This import dependence not only threatens availability but also increases costs for publishers and printers who rely on consistent paper quality and volume for production schedules.
Environmental Compliance and Production Costs
While the push for sustainability is creating opportunities, it also introduces compliance challenges for paper manufacturers. Meeting stringent environmental standards, such as emissions control and waste management, requires significant capital investment in cleaner technologies and sustainable sourcing. For example, the introduction of a carbon price without equivalent measures for imports could accelerate the closure of local production facilities, especially if operating units fall below 87% capacity utilization, rendering them unprofitable. Smaller manufacturers may struggle with the financial burden of transitioning to eco-friendly operations, affecting their competitiveness and market presence in an increasingly regulated landscape.
Market Opportunities:
The Australian book paper market is poised for growth, driven by the resurgence of independent bookstores and a sustained preference for physical books. Despite the rise of digital media, many Australian readers continue to favor printed books, particularly in genres like mystery, which was the largest revenue-generating segment in 2024. This enduring demand presents opportunities for publishers and paper manufacturers to cater to a market that values the tactile experience of reading. Additionally, the rise of self-publishing platforms has democratized the publishing process, allowing a broader range of voices to reach the market.
Furthermore, government initiatives to bolster domestic paper production, such as the $24 million pledge to the Boyer Paper Mill in Tasmania, aim to enhance local manufacturing capabilities. This investment not only supports the local economy but also ensures a stable supply chain for publishers. Moreover, the educational sector continues to be a significant driver, with consistent demand for textbooks and academic materials. As Australia places a strong emphasis on education, the need for high-quality educational materials remains robust, offering a steady market for book paper suppliers.
Market Segmentation Analysis:
The Australia book paper market is segmented based on type, grade, size, and application, reflecting diverse consumer and institutional demands.
By paper types, uncoated wood-free paper holds a prominent share due to its widespread use in educational and trade books, offering good print quality and durability. Coated wood-free paper is favored for high-end publications such as illustrated academic texts and premium consumer books. Coated mechanical and uncoated mechanical papers, while less dominant, serve cost-sensitive applications where volume and affordability are prioritized. The "Others" category includes specialty and recycled paper, which is gaining traction amid rising environmental consciousness.
By paper grade, the market is divided into high-quality and standard paper. High-quality paper is predominantly used in academic, professional, and coffee-table books, where print precision and longevity are crucial. Standard paper remains the choice for mass-market publishing, including educational and trade segments, due to its cost-effectiveness and adequate performance.
By size of paper is also an essential differentiator, with standard sizes dominating institutional use, ensuring compatibility with printing equipment and streamlined production. However, custom sizes are increasingly in demand for special editions, independent publishing, and promotional books.
By application, educational books represent a significant portion of paper consumption, driven by continuous demand from schools and universities. Academic and professional books require premium paper and stable supply cycles. Trade and consumer books contribute significantly to volume, supported by sustained interest in fiction, biographies, and children’s literature. The "Others" category includes religious texts, manuals, and niche publications, rounding out the market’s diverse demand profile.
Segmentation:
By Type of Paper:
- Uncoated Wood-Free Paper
- Coated Wood-Free Paper
- Coated Mechanical Paper
- Uncoated Mechanical Paper
- Others
By Paper Grade
- High-Quality Paper
- Standard Paper
By Size of Paper:
- Standard Sizes
- Custom Sizes
By Application:
- Educational Books.
- Academic/Professional Books
- Trade/Consumer Books
- Others
Regional Analysis:
The Australian book paper market exhibits regional variations influenced by demographic distribution, educational infrastructure, and publishing activities. New South Wales (NSW) leads the market, accounting for approximately 35% of the national share. This dominance is attributed to Sydney's status as a cultural and educational hub, hosting numerous universities, publishing houses, and a significant population of readers and students. The concentration of academic institutions and literary events in NSW drives consistent demand for various types of book paper.
Victoria follows, contributing around 30% to the market. Melbourne's rich literary culture, supported by a vibrant network of bookstores, libraries, and educational institutions, underpins this substantial share. The state's emphasis on arts and education fosters a steady requirement for high-quality paper, particularly for academic and trade publications. Additionally, government initiatives promoting local publishing have bolstered the region's market position.
Queensland holds approximately 15% of the market share. The state's growing population and expanding educational sector, especially in cities like Brisbane and the Gold Coast, contribute to increasing demand for educational and professional books. Efforts to enhance literacy and learning outcomes further stimulate the need for diverse paper types suitable for various publishing needs.
Western Australia and South Australia collectively represent about 12% of the market. While these regions have smaller populations, targeted investments in education and regional publishing initiatives support their contributions. Local publishers and community-driven literary programs play a role in sustaining demand for book paper, particularly for region-specific content.
The remaining 8% is distributed among Tasmania, the Australian Capital Territory, and the Northern Territory. Although these areas have limited market shares due to smaller populations, they maintain consistent demand through educational institutions and localized publishing efforts. Notably, Tasmania's Boyer Paper Mill, supported by government funding, enhances the state's role in domestic paper production, ensuring supply chain stability for the broader market.
Key Player Analysis:
- Holmen Board and Paper
- Visy
- Opal Australian Paper
- Spicers Paper
- Sappi
Competitive Analysis:
The Australia book paper market features a mix of domestic manufacturers, international suppliers, and regional distributors competing across quality, sustainability, and supply chain reliability. Major players such as Opal Australian Paper dominate local production, leveraging vertically integrated operations and strong government backing to ensure consistent output. Global companies like Nippon Paper Group and Sappi Limited also maintain a presence through imports and partnerships, supplying premium and specialty grades. Competition is increasingly shaped by environmental standards, with firms investing in recycled materials and sustainable sourcing to align with evolving consumer preferences. Moreover, digital disruption is pushing traditional paper suppliers to diversify offerings and cater to niche markets such as self-publishing and educational segments. The market remains moderately consolidated, with key players focusing on innovation, pricing strategies, and long-term contracts with publishers and educational institutions to retain competitive advantage and secure market share in a gradually transforming print environment.
Recent Developments:
- In December 2024, Holmen announced a significant restructuring by merging its board and paper operations into a new business area called Holmen Board & Paper. This move is part of a broader strategy to focus on four main business lines: forestry, power generation, wood processing, and process industry. The consolidation is expected to enhance Holmen’s strategic capabilities and streamline its operations in the board and paper sector, with Lars Lundin appointed to lead the new division.
Market Concentration & Characteristics:
The Australian book paper market exhibits moderate concentration, with a few dominant players influencing production and distribution. Opal Australian Paper stands as a significant domestic manufacturer, while international suppliers like Nippon Paper Group and Sappi Limited contribute to the market through imports and partnerships. This structure allows for competitive dynamics, yet the presence of key players ensures a level of stability in supply and pricing. A notable characteristic of this market is its resilience amidst digital transformation. Despite the rise of e-books and digital media, there remains a consistent demand for physical books, particularly in educational and professional segments. The market also reflects a growing emphasis on sustainability, with manufacturers adopting eco-friendly practices and sourcing. Additionally, government initiatives, such as investments in local paper mills, aim to bolster domestic production and reduce reliance on imports. These factors collectively shape a market that balances traditional demand with modern challenges and opportunities.
Report Coverage:
The research report offers an in-depth analysis based on type of paper, paper grade, size of paper, and application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Australia book paper market is expected to witness steady growth driven by consistent demand in the education and professional sectors.
- Rising investments in domestic paper production will strengthen supply chain resilience and reduce import dependency.
- Environmental sustainability will become a key differentiator, prompting increased adoption of recycled and FSC-certified paper.
- Digital disruption will pressure traditional publishers, but niche segments like self-publishing and children’s books will support print demand.
- Technological advancements in printing and paper processing will enhance efficiency and product quality.
- Regional initiatives and government support will encourage innovation and growth in smaller publishing hubs.
- Evolving consumer preferences toward premium and tactile reading experiences will sustain the demand for high-quality paper.
- Growth of independent bookstores and subscription-based print models will open new distribution channels.
- Fluctuations in raw material pricing and logistics may impact market stability in the short term.
- Strategic partnerships between publishers and local paper manufacturers will foster long-term market competitiveness.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Australia Book Paper Market?
What factors are driving the growth of the Australia Book Paper Market?
What are some challenges faced by the Australia Book Paper Market?
Who are the major players in the Australia Book Paper Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Australia Book Paper Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Australia Book Paper Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 120.10 million → 2032: USD 178.06 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Australia Book Paper Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Australia Book Paper Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Australia Book Paper Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Australia Book Paper Market Drivers
- 3.3 Australia Book Paper Market Restraints & Challenges
- 3.4 Australia Book Paper Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Australia Book Paper Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Australia Book Paper Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Australia Book Paper category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Australia Book Paper Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Australia Book Paper Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Australia Book Paper market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Australia Book Paper Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Australia Book Paper Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Australia Book Paper Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Australia Book Paper (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Australia Book Paper Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Australia Book Paper Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Australia Book Paper Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Australia Book Paper Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Australia Book Paper Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Australia Book Paper Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Australia Book Paper Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Australia Book Paper Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Australia Book Paper Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
