
Cakes and pastries set the pace in the freezer aisle
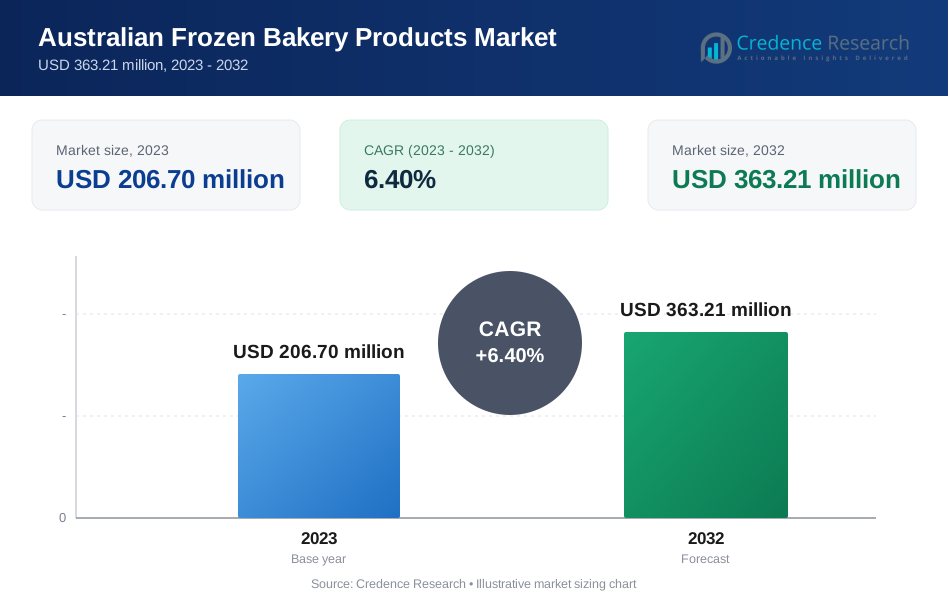
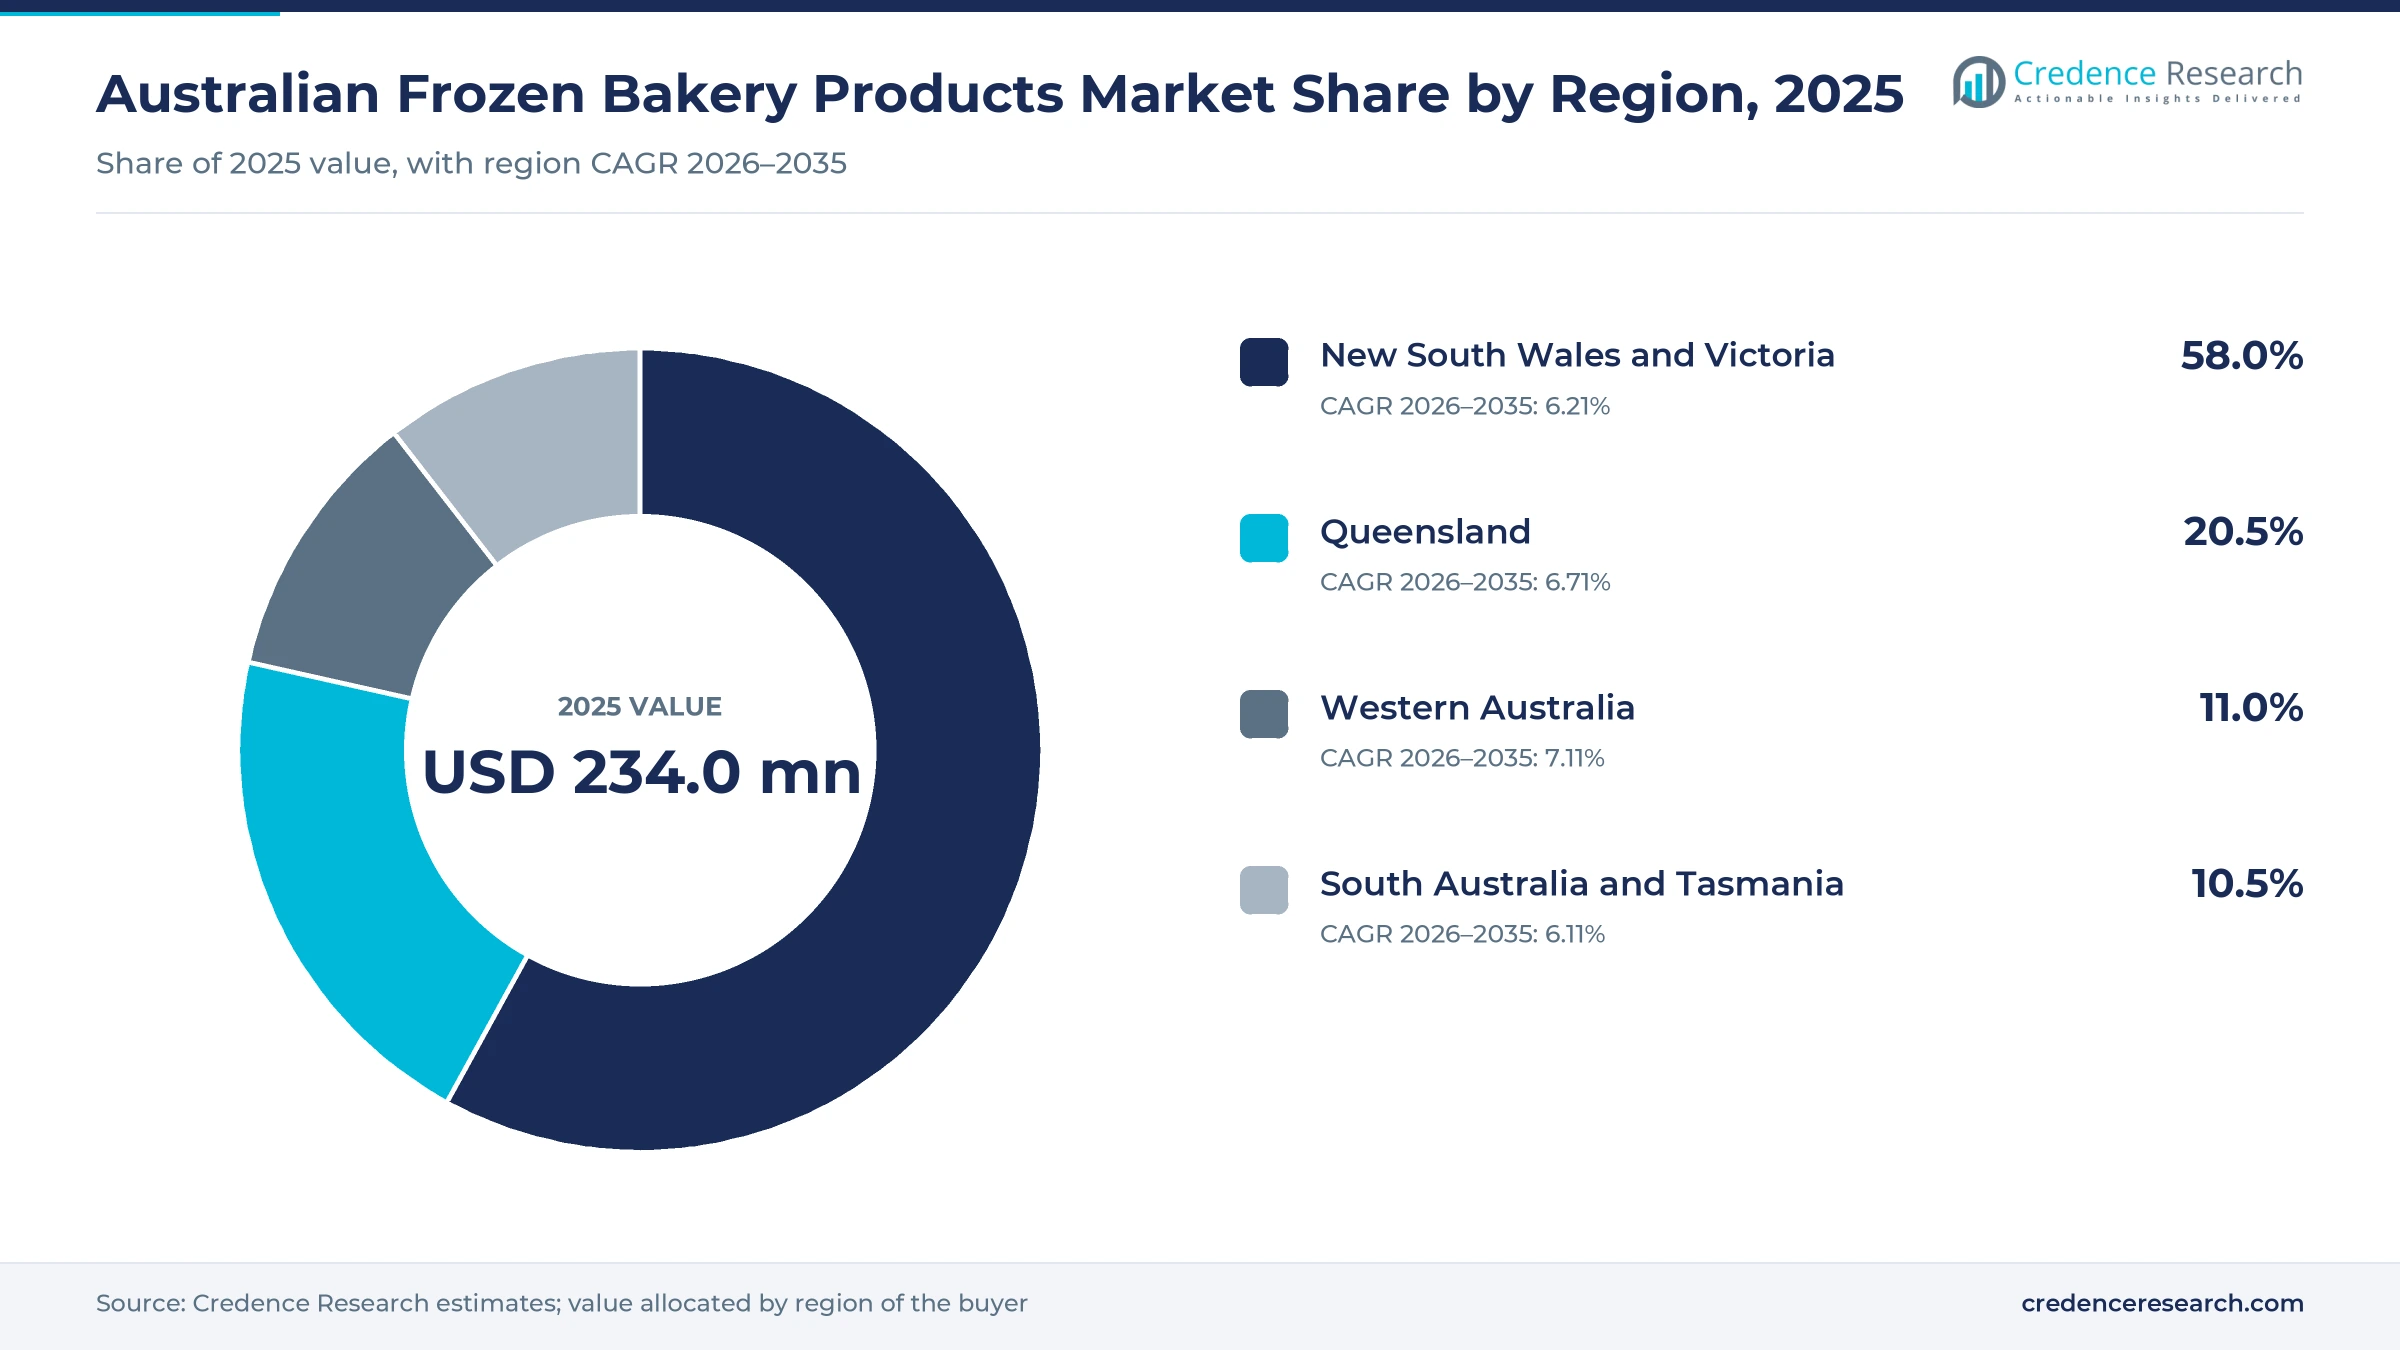
The Australian frozen bakery products market was valued at USD 234.0 million in 2025 and is projected to increase from USD 249.0 million in 2026 to USD 435.2 million by 2035, registering a CAGR of 6.40% during 2026–2035. Demand comes from supermarket freezers, cafes, hospitals, airlines and in-store bakeries that want finished quality without overnight baking shifts. New South Wales and Victoria held the largest regional share, 58.0% in 2025, because that zone holds about 58% of the national population. Western Australia is the fastest-growing region at 7.11% a year, helped by the country's quickest population growth and new bakery capacity in Perth. The commercial picture also changed in January 2024, when Sara Lee's frozen dessert business left administration under new private owners, and later when ARYZTA opened its first Western Australian bakery south of Perth.
What counts as a frozen bakery product in Australia?
Bakery products are foods made from flour or dough and baked, such as bread, cakes, pastry, croissants and pizza bases. This report counts the versions sold frozen, whether raw dough, par-baked or fully baked, at first-sale value to retailers and foodservice buyers. Buyers include supermarkets, independent grocers, cafes, caterers, hospitals and airlines, and most purchase through national distributors or direct supply contracts.
Fresh ambient bread, biscuits, ice cream, frozen ready meals and filled savory meat pies are excluded, although some of the same companies make them. Frozen dessert cakes, sweet pies and cheesecakes are included, which is where this market overlaps with wider frozen dessert spending. The value chain runs from flour and butter suppliers through plants in Australia and overseas to cold storage and the final bake-off.
Australian Frozen Bakery Products Market Insights
- The market grows from USD 234.0 million in 2025 to USD 435.2 million by 2035, a compound rate of 6.40% during 2026–2035, with most new value coming from foodservice and morning goods.
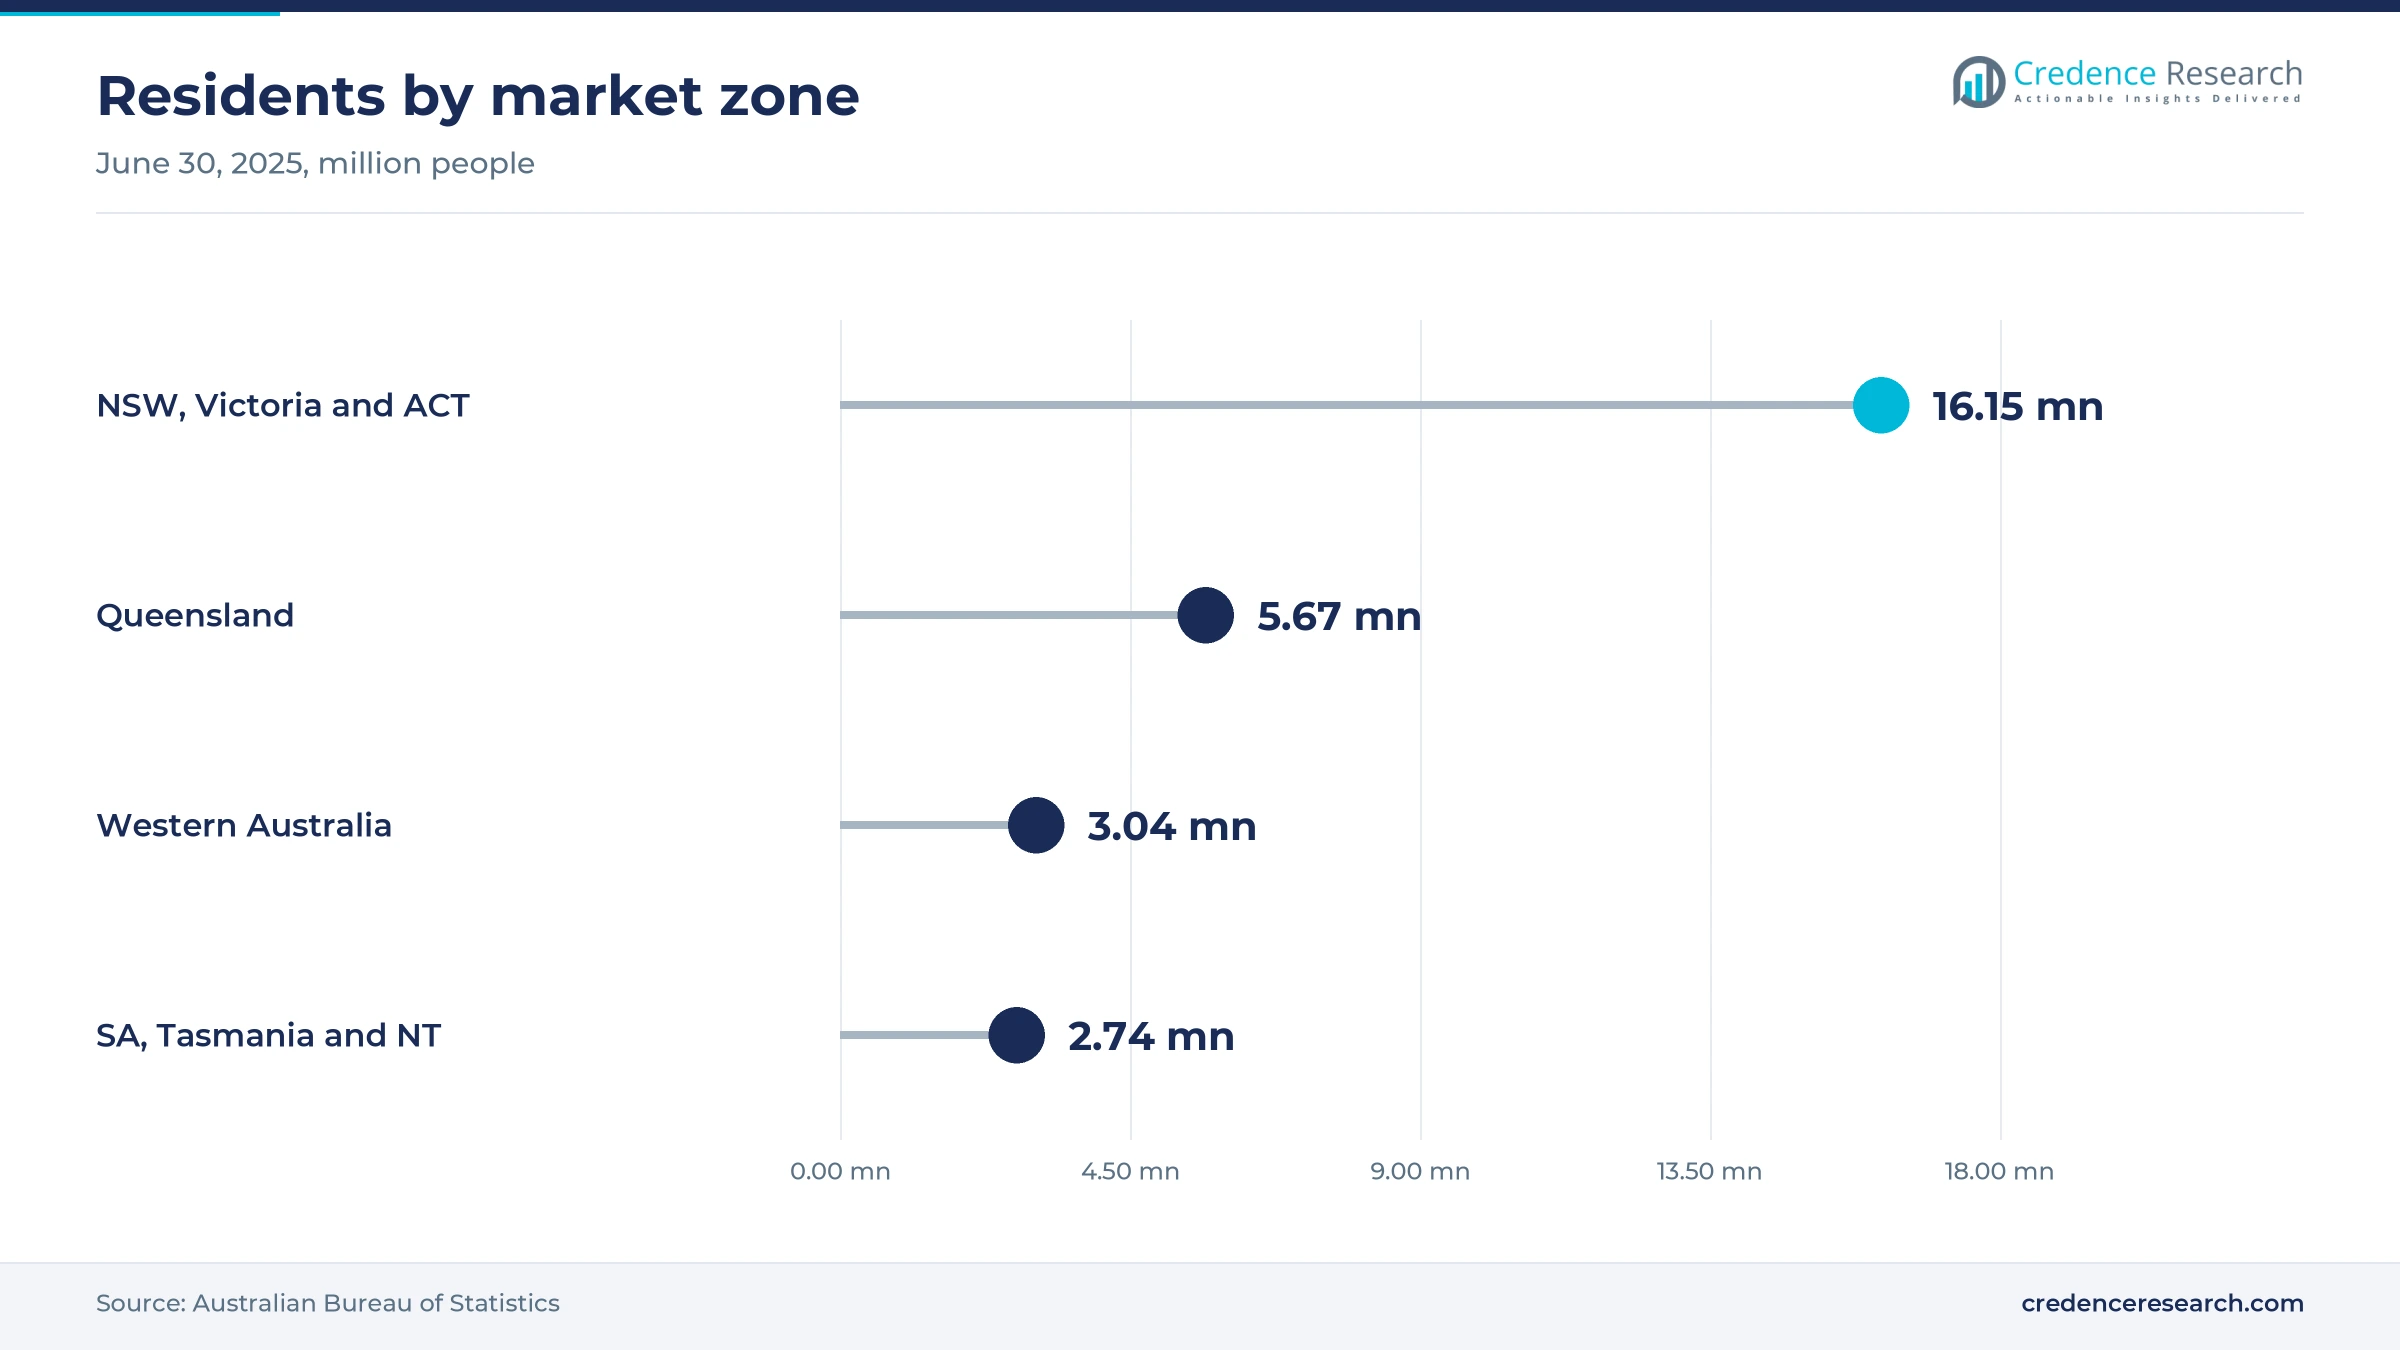
- New South Wales and Victoria held 58.0% of 2025 value, in line with Australian Bureau of Statistics population counts for that zone.
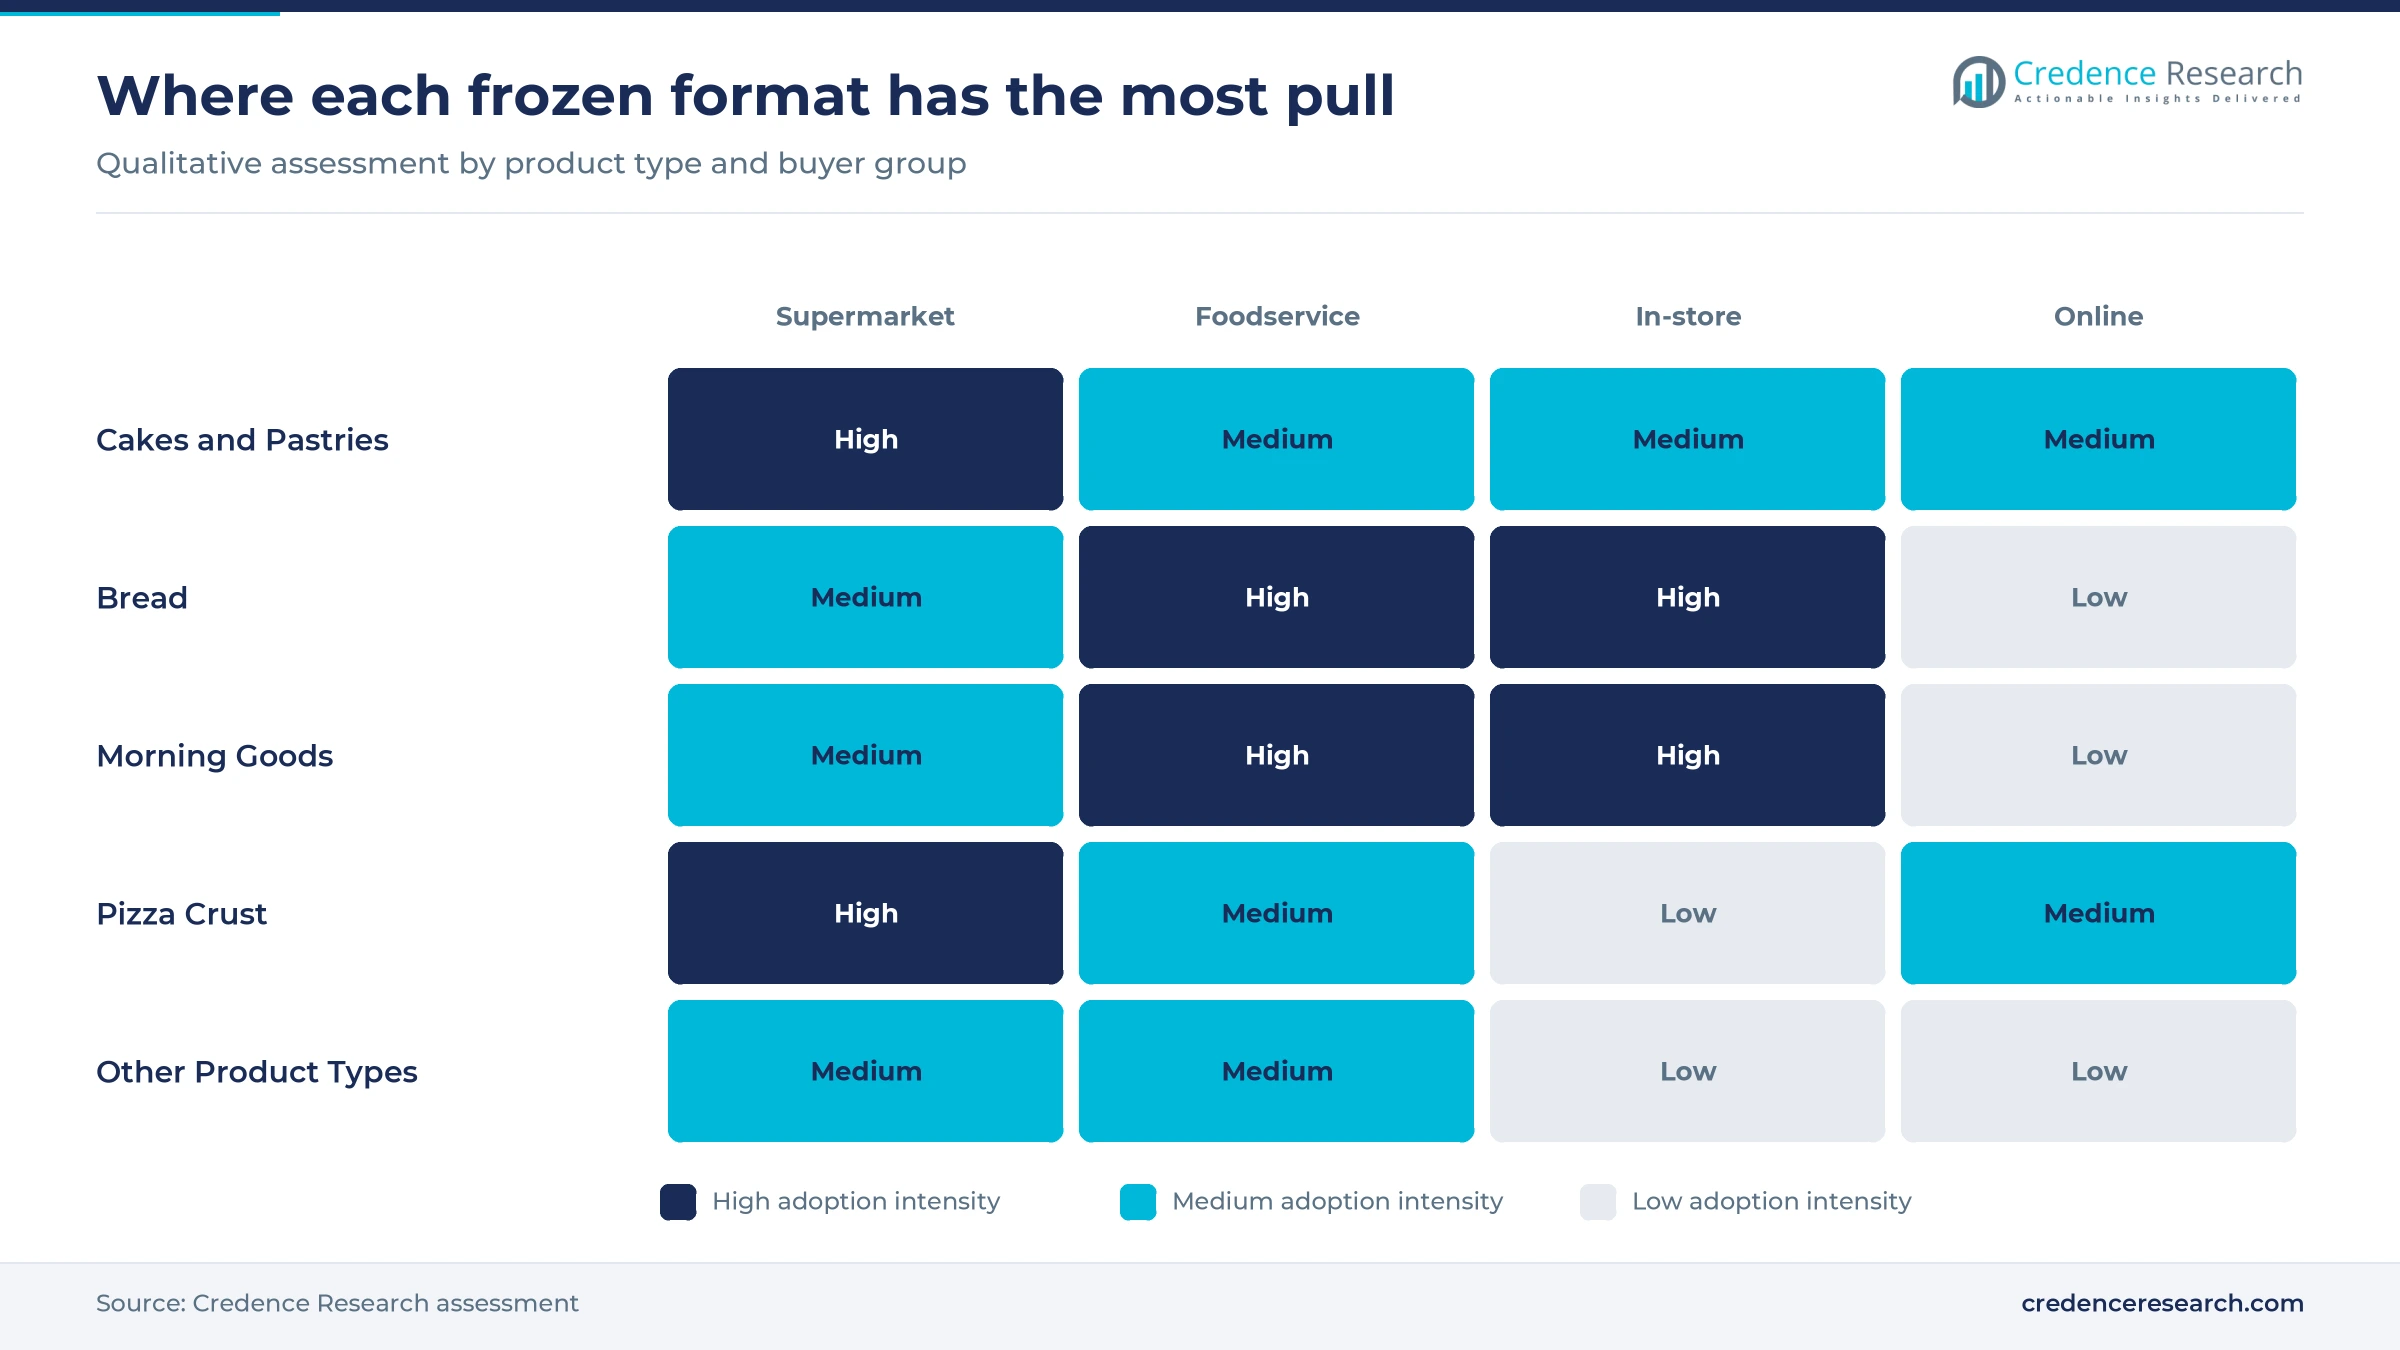
- Cakes and Pastries led product types with 38.0% of 2025 value, anchored by frozen cheesecakes, sweet pies and pastry sheets.
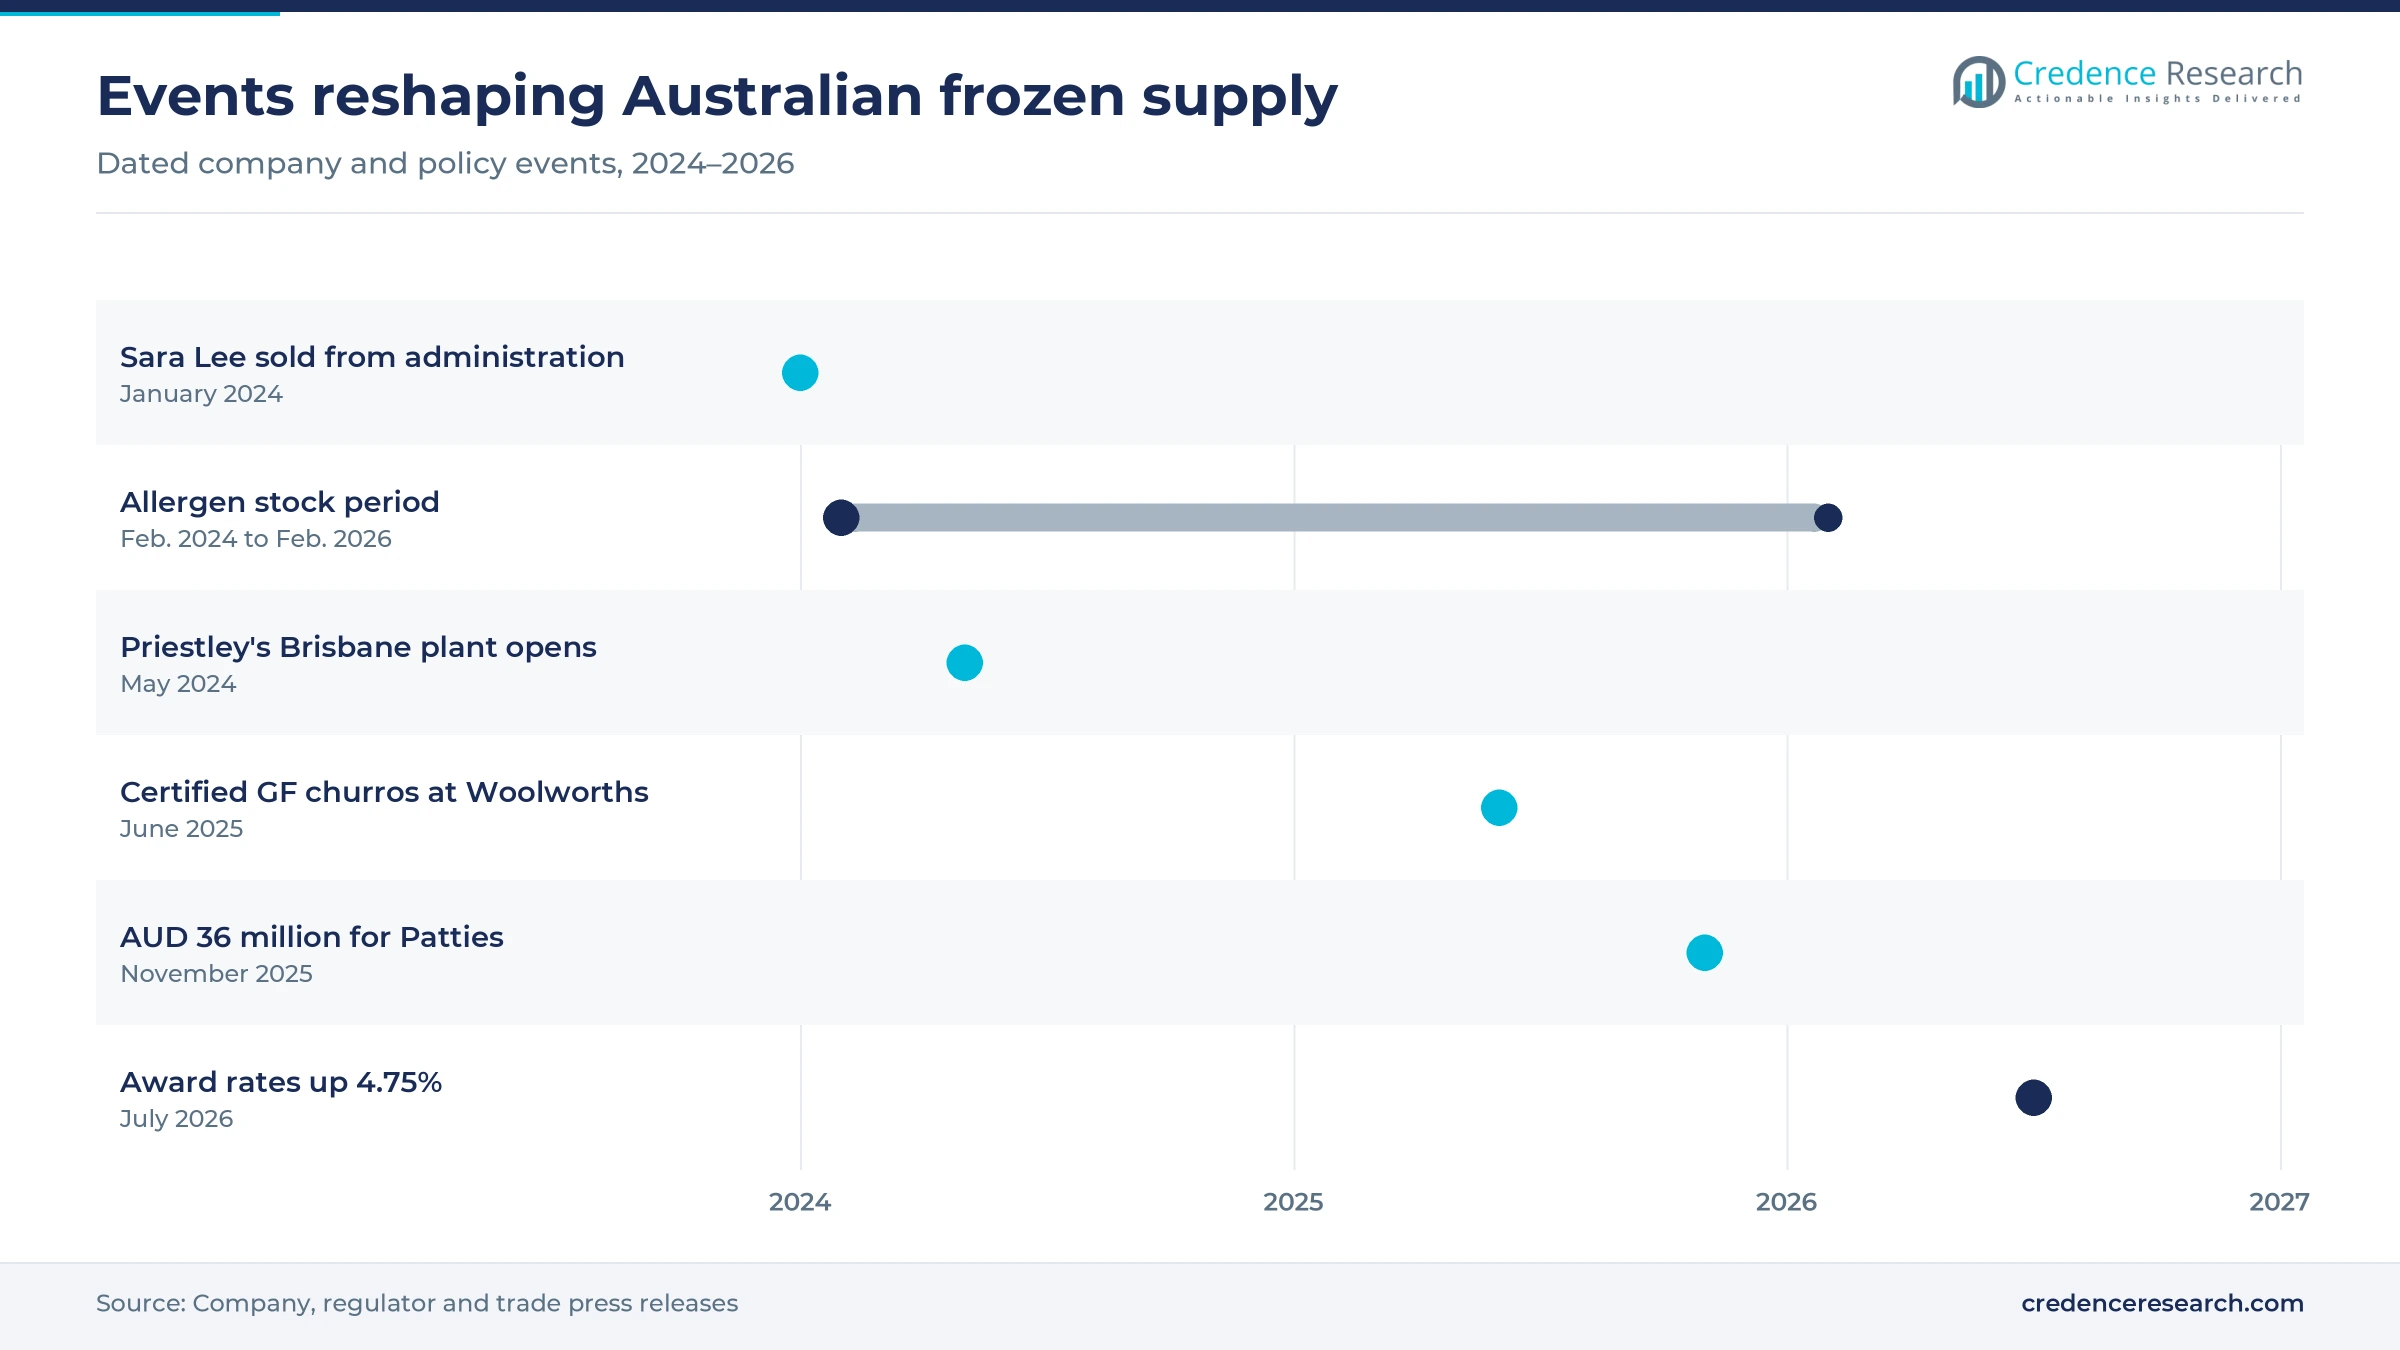
- Supply changed hands and shape after Sara Lee was sold in January 2024 and Priestley's Gourmet Delights opened its AUD 53 million Brisbane plant in May 2024.
- ARYZTA's new Perth facility, which its 2025 filing expected to remove about 1.7 million food miles, signals that freight now shapes where capacity gets built.
Sweet pastry leads while croissants climb fastest
Why do cakes and pastries lead frozen bakery value?
Based on product type, the market is categorized into bread, cakes and pastries, morning goods, pizza crust and other product types. Cakes and Pastries led with 38.0% of 2025 value, because frozen cakes and desserts now sell at scale, with Priestley's making about 100 metric tons a week and freezing desserts on site, according to Food Processing and BeanScene, and just-food noting that Sara Lee produces frozen cheesecakes, pies and crumbles. Morning Goods grow fastest at 7.36% a year, as a workforce of 34,200 bakers and pastrycooks, in Jobs and Skills Australia data, pushes cafes toward finish-on-site lines, such as the ready-to-bake croissants Bakers Maison snap-freezes in Revesby.
How much frozen bakery sells through supermarkets and online?
Based on distribution channel, the market is categorized into hypermarkets/supermarkets, specialty stores, online retailing and other distribution channels. Hypermarkets/Supermarkets led with 57.0% of 2025 value, because national freezer ranging decides volume, as Coles' October 2025 release on its 17 Product of the Year awards showed with a frozen Finest lemon meringue tart. Online Retailing grows fastest at 8.53% a year, as Coles reported in August 2025 that eCommerce penetration reached 11.2% after sales rose 24.4% in the year, which brings frozen lines into more home deliveries.
Who buys frozen bread and pastry after the retailer?
Based on end user, the market is categorized into retail households, foodservice and in-store bakeries. Retail Households led with 56.0% of 2025 value, because take-home staples sell at scale, with Goodman Fielder's 2024 foodservice brochure citing over 15 million La Famiglia garlic bread loaves sold each year on a retail basis. Foodservice grows fastest at 6.98% a year, as Goodman Fielder names hospitals, airlines, sandwich makers, schools and five-star hotels among buyers of blast-chilled artisan loaves that kitchens pull from the freezer as needed.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product Type | Cakes and Pastries | 38.0% | Morning Goods | 7.36% |
| By Distribution Channel | Hypermarkets/Supermarkets | 57.0% | Online Retailing | 8.53% |
| By End User | Retail Households | 56.0% | Foodservice | 6.98% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Baker shortages and new plants lift frozen supply
Why are kitchens replacing overnight baking with frozen stock?
Skilled baking labor is scarce and costly, so kitchens buy frozen stock instead of staffing overnight shifts. Jobs and Skills Australia counted 34,200 bakers and pastrycooks in its occupation profile, a small workforce for a national food trade. The National Baking Industry Association said in April 2022 that unsocial hours, weekend work and comparatively low pay make staff hard to attract. As a result, Food Processing reported in September 2018 that restaurants, cafes and caterers were moving from frequent fresh deliveries to par-baked and fully baked frozen lines, which also removes leftover stock. This shift supports Foodservice, the fastest-growing end user at 6.98% a year.
How do in-store bakeries pull frozen dough into supermarkets?
Supermarket bakeries are a steady outlet because finishing frozen goods on site delivers fresh aroma without a full bakery crew. The Australian Competition and Consumer Commission recorded in April 2015 that par-baked bread, frozen off site by a supplier, was sold through in-store bakeries in 637 Coles supermarkets. Inside Retail then reported in June 2017 that Coles planned bakeries for another 180 stores. A U.S. Department of Agriculture report of Nov. 19, 2025 gave Woolworths a 38.7% and Coles a 29.5% market share, so two buyers set most bake-off volumes. As a result, supermarkets gave suppliers a reliable base during 2025, holding 57.0% of market value across their aisles and bakeries.
What does population growth add to freezer demand?
More households and more meals outside the home add volume in every state, which supports steady growth without relying on price increases. The Australian Bureau of Statistics counted 27.6 million residents at June 30, 2025, up 420,100 in a year, or 1.5%. Victoria and Queensland each grew 1.8%, ahead of New South Wales at 1.2%, so growth is not evenly shared across the eastern states. Restaurant & Catering Australia, citing bureau retail data, put cafe, restaurant and takeaway turnover at AUD 66.27 billion for the year to June 2025, up 2.5%. In turn, this larger customer base supports steady volume for frozen suppliers through 2026–2035.
Which plant investments are expanding domestic supply?
Fresh capital is enlarging domestic capacity, which shortens lead times for local buyers. Food Processing reported on Nov. 19, 2025 that the National Reconstruction Fund Corporation would lend Patties Food Group AUD 36 million to modernize facilities. Priestley's Gourmet Delights opened a AUD 53 million plant at Acacia Ridge in Brisbane in May 2024. ARYZTA has opened its first Western Australian bakery at Peel Business Park, south of Perth, according to Baking Business, and its chair said in December 2023 that the site lets it make fresh and frozen products rather than ship frozen stock long distances. The Priestley's and ARYZTA projects add cake, dessert and bake-off capacity, while the Patties funding mainly supports savory lines outside this estimate, plus its Nanna's fruit pies and crumbles.
Free-from ranges, sourdough dough and Perth capacity
Shift toward certified free-from freezer ranges
Free-from ranges suit the freezer because frozen stock tolerates slower turnover without wasting costly ingredients. Coeliac Australia data cited by Australian Food News in March 2020 put coeliac disease at about 1 in 70 Australians, with more than 270,000 people undiagnosed. Woolworths had then added more than 40 lines to its Free From Gluten range over three years and reported double-digit demand growth. Food Processing reported in June 2025 that Simply Wize certified gluten-free churros were entering Woolworths freezer aisles. This activity overlaps with wider gluten-free baked goods, and it raises average pack prices above standard lines, which lifts value faster than volume.
Rise of sourdough and artisan dough in frozen form
Frozen formats are moving upmarket, as suppliers now sell craft cues that once required a skilled baker on site. Suprima Bakeries of Minto announced on Jan. 18, 2023 an artisan frozen dough range using a sourdough culture maintained for more than four years. Goodman Fielder says its frozen artisan loaves are baked on granite slabs before blast chilling, according to its 2024 foodservice brochure. McCain Foods also sold Rustica wood-fired sourdough pizzas through Coles, Woolworths and Metcash from April 2017, joining other wood-fired pizza ranges. Consequently, buyers with basic combi and deck ovens can offer a premium loaf, which supports Morning Goods and bread pricing alike.
Opportunity in western and regional production close to buyers
An opening exists for producers that make goods near western and regional customers, since cross-country freezer freight is a real cost. ARYZTA's 2025 filing expected its Perth facility to remove about 1.7 million food miles previously driven between eastern and western Australia, with all its electricity from renewable sources. Western Australia held about 3.04 million residents in June 2025 and led national growth at 2.2%, according to the Australian Bureau of Statistics. Baking Business reported that the new plant replaces baked goods transported from New South Wales and Victoria and should create 110 to 130 local jobs. Therefore, the state's faster population growth should reward producers with local lines.
Opportunity to win back imports and reopen exports
Import replacement and exports offer room beyond the home freezer, because Australia runs a wide deficit in baked goods. TrendEconomy trade data show Australia imported about USD 974 million of HS 1905 bakers' wares in 2023, a broad code that also covers biscuits and fresh bread, and exported about USD 131 million, with New Zealand taking 56% of exports. France and Italy supplied about 8.7% and 7.6% of those imports. The January 2024 Sara Lee sale included rights to sell in South East Asia and the Middle East, according to just-food. The U.S. Department of Agriculture's November 2025 retail report also ranked bakery goods among major imports, with Thailand, New Zealand and Italy as leading suppliers.
Butter, wages and refrigerant costs squeeze margins
Butter and egg prices swing pastry margins
Butter and eggs are the costliest swing inputs for pastry makers. Food Processing reported in July 2025 that eggs rose 19.1% in a year after avian flu, while RaboResearch warned that near-record global butter prices could reach Australia, a net importer. Producers of laminated goods feel this first, because butter is the core laminating ingredient. ABARES forecast a wheat crop just under 36 million metric tons for 2025–26, which steadies flour, but it does not offset dairy pressure.
Award wage rises raise the cost of every shift
Labor costs jumped when the Fair Work Commission, on June 2, 2026, raised modern award rates 4.75% from July 1, 2026, according to Clayton Utz. Plants with manual packing and depositing absorb this rise directly, and smaller producers have little pricing power against major supermarkets. The likely response is automation, as Priestley's has shown by using robots to double its capacity, although such projects need capital that independent bakers often cannot raise easily.
Refrigerant limits add cold-chain risk
Frozen supply carries a cold-chain exposure that ambient bakery lines largely avoid. Climate Control News reported in June 2023 that Australia's hydrofluorocarbon quota was stepping down, with a further 10% cut due in 2024, and that independent supermarkets still favored HFC-404A for new stores and refits. That leaves smaller grocers and distributors facing costlier retrofits over time. The Australian Energy Regulator's 2026–27 default offer eases some pressure, with small-business flat rates down 10.4% in South East Queensland, but refrigeration remains a permanent running cost.
Freshness claims and allergen labels carry legal risk
Marketing frozen goods as fresh remains a legal hazard for retailers and their suppliers. The Federal Court ordered Coles to pay AUD 2.5 million in April 2015 over "Baked Today, Sold Today" claims on par-baked bread. Labeling duties also tightened when plain English allergen stock rules ended their final period on Feb. 25, 2026, according to Foodmag. Importers and small brands therefore carry extra artwork and compliance costs.
East coast volume, western growth from Perth
| Region | Value, 2025 (USD million) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| New South Wales and Victoria | 135.7 | 58.0% | 6.21% |
| Queensland | 48.0 | 20.5% | 6.71% |
| Western Australia | 25.7 | 11.0% | 7.11% |
| South Australia and Tasmania | 24.6 | 10.5% | 6.11% |
New South Wales and Victoria hold the core of demand and supply
New South Wales and Victoria held a regional share of 58.0% in 2025 and grow at 6.21% a year. This lead reflects the 16.15 million residents who live in the zone. Supply clusters here as well, with Bakers Maison at Revesby, Suprima at Minto and Allied Mills' frozen bakery plant at Tullamarine, which a Victorian minister opened after upgrades in April 2015. Sara Lee's Australian business also began at Lisarow, New South Wales, in 1971.
Queensland adds cake capacity in Brisbane
Queensland held a regional share of 20.5% in 2025 and grows at 6.71% a year. Its 5.67 million residents and 1.8% population growth support that pace. The state's largest recent project is Priestley's Acacia Ridge plant in Brisbane, which received a AUD 2.5 million Made in Queensland grant and projected 56 more roles by 2026. Retail launch partners Drakes Supermarkets and Ritchies IGA show how independent grocers help regional brands reach shoppers. Priestley's told BeanScene in 2025 that it went from a fresh manufacturer to a frozen one to match what cafes need.
Western Australia gains from local production
Western Australia held a regional share of 11.0% in 2025 and grows fastest at 7.11% a year. Its 2.2% population growth led the states in the year to June 2025. Long haul from eastern plants has historically raised delivered costs, which makes ARYZTA's Perth facility for quick-service buyers important. Food Processing placed the site at Peel Business Park, about 60 km south of the Perth business district, in December 2023. New capacity should reduce reliance on interstate freezer freight during the forecast period.
South Australia and Tasmania stay smaller
South Australia and Tasmania held a regional share of 10.5% in 2025 and grow at 6.11% a year, the slowest pace. South Australia grew 1.1% and Tasmania just 0.2% in the year to June 2025. The Australian Bureau of Statistics counted 1.90 million South Australians and 576,000 Tasmanians at that date, which limits the scale available to a local plant. South Australian small businesses also gain from a 6.8% cut in flat-rate default power offers for 2026–27, according to the Australian Energy Regulator, which helps cold storage budgets.
Rescues, plants and funding reshaped supply since 2024
| Development | Status and market relevance |
|---|---|
| In January 2024, a private company owned by Klark and Brooke Quinn agreed to buy Sara Lee's Australian and New Zealand businesses from administrators FTI Consulting. | Saved about 200 jobs and kept a leading frozen dessert brand in local hands |
| In May 2024, Priestley's Gourmet Delights opened its AUD 53 million Acacia Ridge plant in Brisbane with mobile robots. | Opened; capacity about 100 metric tons of cakes and desserts a week |
| In June 2025, Simply Wize certified gluten-free churros entered Woolworths freezer aisles, according to Food Processing. | On shelf; widens the free-from freezer range |
| In October 2025, Coles reported 17 Product of the Year wins, including a frozen Finest French lemon meringue tart pack. | Announced; supports premium private label in the freezer |
| In November 2025, the National Reconstruction Fund Corporation agreed a AUD 36 million debt investment in Patties Food Group. | Funding for modernized facilities, mainly savory lines |
Blast freezing and robots decide who scales
- Blast chilling locks in crumb and crust straight after baking, and Goodman Fielder uses it on its granite-slab artisan loaves for foodservice.
- Snap-frozen ready-to-bake dough lets a cafe bake croissants to order, and Bakers Maison uses this method so its Luna line can ship nationally.
- Mobile autonomous robots move baking racks without manual handling, and Priestley's pairs them with a manufacturing execution system in Brisbane.
- Natural refrigerants such as carbon dioxide are spreading in supermarkets, according to HVAC&R News in May 2024, as high-warming gases come under quota.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Local brands compete with imports and private label
Competition splits between branded desserts, foodservice specialists and retailers' private labels. Sara Lee remains the best-known freezer dessert name after its 2024 rescue, while Patties Food Group brings Nanna's fruit pies and crumbles from a wider, mainly savory portfolio, plus the funding described above. Goodman Fielder competes on breadth, from Pampas pastry to La Famiglia garlic bread, which gives it leverage with both supermarkets and kitchens. Bakers Maison and Suprima Bakeries focus on cafes, caterers and in-store bakers that want finish-on-site quality. ARYZTA targets quick-service chains, and its Perth site narrows the freight gap for that work. Allied Pinnacle, owned by Nisshin Seifun since 2019, links flour and premixes and improvers with prepared bakery goods. McCain Foods has sold frozen pizza ranges through major grocers since at least April 2017. European imports add price competition, which keeps local producers focused on service, freshness and shorter lead times.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Sara Lee | Frozen dessert brand | Frozen cheesecakes, pies and crumbles; sold to the Quinn family's company in 2024 |
| Patties Food Group | Pastry and frozen foods maker | Nanna's fruit pies and crumbles; most of its range is savory |
| Goodman Fielder | Bakery and foodservice supplier | Pampas pastry, La Famiglia frozen garlic bread and frozen artisan loaves |
| Bakers Maison | Specialist bakery manufacturer | Snap-frozen croissants made at Revesby in Sydney for foodservice |
| Suprima Bakeries | Bakery supplier | Artisan frozen sourdough dough from Minto for bakers and supermarkets |
| ARYZTA | Bake-off producer | New Perth facility aimed at quick-service restaurant customers |
| Allied Pinnacle | Flour and bakery supplier | Flour, premixes and prepared bakery goods; owned by Nisshin Seifun |
| McCain Foods | Frozen food maker | Frozen pizza ranges through Coles, Woolworths and Metcash |
Capacity close to the buyer will decide the winners
Credence Research's view is that location and labor now matter more than recipe in this market. Buyers can already choose good frozen croissants, so the winning supplier will be the one that delivers reliably without a costly interstate haul. Priestley's Brisbane plant and ARYZTA's Perth site show capital following that logic. Margin pressure from butter and award wages will favor plants able to automate, and smaller brands may need partnerships or sales to fund it. Sara Lee's administration in October 2023 is a reminder that a strong brand alone does not protect a frozen dessert business.
How the 2025 value and splits were estimated
The report uses 2025 as the base year and forecasts to 2035. The 2025 value starts from the previous Credence Research model value of USD 206.70 million for 2023, advanced at its own compound rate, then tested against population statistics and disclosed company data. Segment and regional splits are Credence Research estimates, informed by population statistics, plant locations and company disclosures. Sources include government statistics, regulator releases, company filings and trade press. No interviews or surveys were conducted for this update, so splits should be read as modeled estimates.
Foodservice and online baskets shape demand to 2035
Through 2035 the market adds value steadily rather than dramatically, reaching USD 435.2 million on a 6.40% path. Foodservice should keep gaining because baker numbers remain tight and award costs keep rising. Morning goods and online baskets start small but should grow the quickest. Interest lies in how quickly new plants in Perth and Brisbane absorb imported volume. A sustained fall in butter prices would help pastry makers, while further refrigerant limits could favor larger operators that can afford modern cold storage and distribution systems.
Frequently Asked Questions
How big is the Australian frozen bakery products market?
What are bakery products?
How does frozen fit into the wider Australia bakery products market?
How large are frozen cakes and pastries in Australia?
Does this report cover the Australia frozen dessert market?
Which Australian region buys the most frozen bakery goods?
Who are the main frozen bakery companies in Australia?
Is frozen bread allowed to be called fresh in Australia?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Cakes and Pastries
- 1.2.2 Bread
- 1.2.3 Morning Goods
- 1.2.4 Pizza Crust
- 1.2.5 Other Product Types
- 1.3 By End User
- 1.3.1 Retail Households
- 1.3.2 Foodservice
- 1.3.3 In-Store Bakeries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 234.0 million → 2035: USD 435.2 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australian Frozen Bakery Products Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australian Frozen Bakery Products Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Australian Frozen Bakery Products Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Australian Frozen Bakery Products Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australian Frozen Bakery Products Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australian Frozen Bakery Products Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australian Frozen Bakery Products Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australian Frozen Bakery Products Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 234.0 million → 2035: USD 435.2 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australian Frozen Bakery Products Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Cakes and Pastries
- 12.3.7.2 Bread
- 12.3.7.3 Morning Goods
- 12.3.7.4 Pizza Crust
- 12.3.7.5 Other Product Types
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Retail Households
- 12.4.7.2 Foodservice
- 12.4.7.3 In-Store Bakeries
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Australian Frozen Bakery Products End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australian Frozen Bakery Products Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australian Frozen Bakery Products Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Australian Frozen Bakery Products Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Sara Lee
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Patties Food Group
- 18.4 Goodman Fielder
- 18.5 Bakers Maison
- 18.6 Suprima Bakeries
- 18.7 ARYZTA
- 18.8 Allied Pinnacle
- 18.9 McCain Foods
- 18.10 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

