
Market Overview:
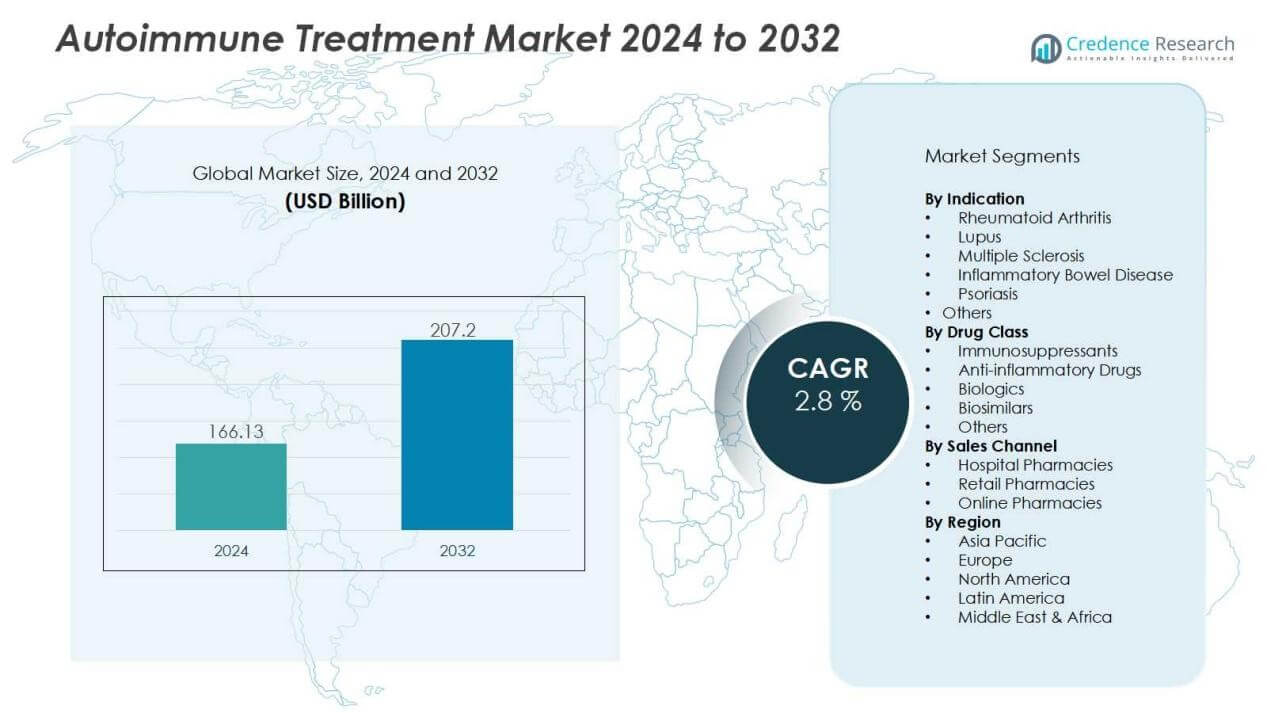
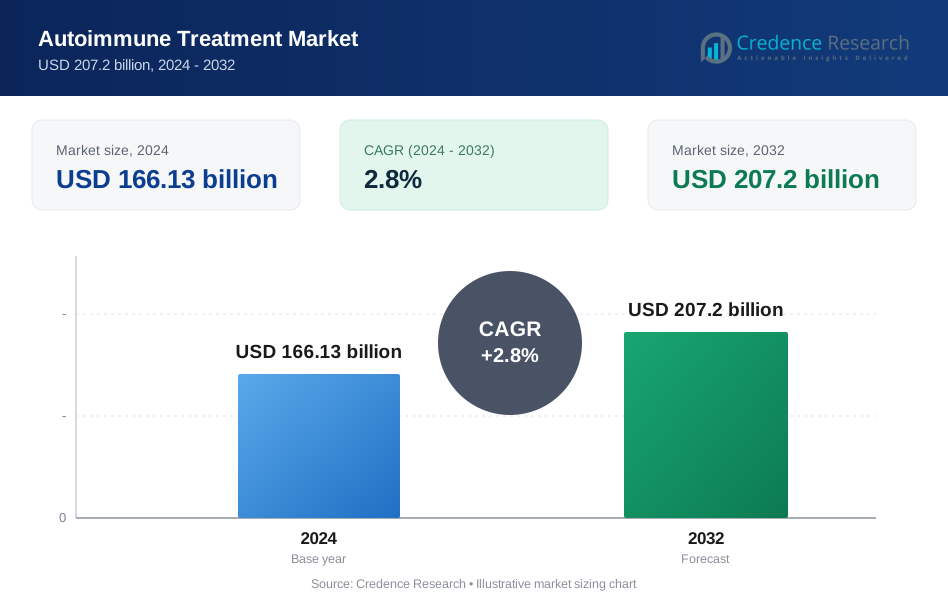
The Autoimmune Treatment Market size was valued at USD 166.13 billion in 2024 and is anticipated to reach USD 207.2 billion by 2032, at a CAGR of 2.8 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Autoimmune Treatment Market Size 2024 | USD 166.13 Billion |
| Autoimmune Treatment Market, CAGR | 2.8% |
| Autoimmune Treatment Market Size 2032 | USD 207.2 Billion |
Market drivers include the rising incidence of autoimmune disorders such as rheumatoid arthritis, lupus, multiple sclerosis, and inflammatory bowel disease. Increased awareness, early diagnosis, and technological advances in monoclonal antibodies, immunosuppressants, and biosimilars are boosting treatment adoption. Favorable reimbursement policies and strong research investments from pharmaceutical companies further strengthen the market’s momentum.
Regionally, North America dominates the autoimmune treatment market, supported by high healthcare spending, advanced diagnostic infrastructure, and strong presence of major drug developers. Europe follows closely with increasing biologics use and government initiatives supporting chronic disease management. Asia-Pacific is anticipated to register the fastest growth, driven by rising patient populations, improving healthcare access, and growing investment in innovative therapies across countries such as China and India.
Market Insights:
- The autoimmune treatment market was valued at USD 166.13 billion in 2024 and is projected to reach USD 207.2 billion by 2032, growing at a CAGR of 2.8% between 2024 and 2032.
- Rising prevalence of autoimmune disorders such as rheumatoid arthritis, lupus, multiple sclerosis, and inflammatory bowel disease continues to drive strong demand for long-term therapies.
- Advancements in biologics, monoclonal antibodies, and biosimilars are reshaping treatment practices with higher efficacy, better safety, and improved patient adherence.
- Increasing healthcare expenditure and favorable reimbursement policies are making advanced therapies more accessible across major economies, strengthening adoption rates.
- Expanding research and development investments by pharmaceutical and biotech companies are fueling innovation in precision medicine and immune-modulating therapies.
- High cost of biologics and limited accessibility in low- and middle-income regions remain key challenges, restricting treatment adoption and widening healthcare disparities.
- North America held 44.2% share in 2024, Europe followed with 29.6%, while Asia-Pacific recorded 18.5% share and is projected to grow at the fastest pace.
Market Drivers:
Rising Prevalence of Autoimmune Disorders :
The autoimmune treatment market is driven by the rising prevalence of chronic autoimmune diseases such as rheumatoid arthritis, multiple sclerosis, psoriasis, and inflammatory bowel disease. Increasing stress, lifestyle changes, and genetic predispositions contribute to growing incidence rates worldwide. With millions of new cases diagnosed each year, the demand for long-term treatment continues to expand. It has created strong momentum for pharmaceutical companies to advance therapies targeting specific disease pathways.
- For Instance, In October 2023, Novartis received FDA approval for Cosentyx (secukinumab) to treat moderate to severe hidradenitis suppurativa, making it the first biologic targeting IL-17A approved for this condition. Data from the SUNSHINE and SUNRISE trials demonstrated clinically meaningful relief as early as week 2 and sustained efficacy through week 52.
Advancements in Biologics and Targeted Therapies:
The development of biologics and targeted therapies plays a central role in driving growth. These treatments, including monoclonal antibodies and biosimilars, offer improved efficacy, reduced side effects, and higher patient adherence compared to conventional drugs. It strengthens the therapeutic pipeline and enhances adoption across both developed and emerging markets. The autoimmune treatment market benefits from ongoing innovation that addresses unmet clinical needs.
- For instance, Celltrion's Avtozma (tocilizumab-anoh), a biosimilar to Actemra, received FDA approval in January 2025 for treating rheumatoid arthritis and other autoimmune conditions. Clinical trials showed that Avtozma had similar efficacy to the reference product, with studies demonstrating a significant mean reduction in the disease activity score (DAS28-ESR) by approximately -4.279 at week 52 in rheumatoid arthritis patients.
Growing Healthcare Expenditure and Insurance Coverage:
Rising healthcare expenditure across major economies supports wider adoption of advanced autoimmune treatments. Governments and private insurers are offering favorable reimbursement policies, making high-cost biologics and specialty drugs more accessible. It enables broader patient populations to access timely treatment, which drives consistent market expansion. Improved affordability and structured healthcare systems contribute significantly to growing demand.
Expanding Research and Development Investments:
Large pharmaceutical companies and biotech firms are increasing investments in research and clinical trials to develop novel treatment options. Strong pipelines focused on precision medicine and immune-modulating therapies fuel expectations for breakthrough solutions. It highlights the industry’s commitment to tackling complex autoimmune conditions with innovative approaches. Strategic partnerships and collaborations between companies and research institutions further accelerate progress in the autoimmune treatment market.
Market Trends:
Growing Demand for Personalized and Targeted Therapies in Autoimmune Disorders:
The Autoimmune Treatment Market is shaped by increasing demand for precision and personalized medicine. Patients and healthcare providers are seeking therapies tailored to specific immune pathways and genetic profiles. It is driving development of biologics, monoclonal antibodies, and cell-based therapies that offer higher efficacy with fewer side effects. The integration of biomarkers for early diagnosis and treatment selection is also gaining traction. Pharmaceutical firms are investing in research partnerships to accelerate innovation in targeted drugs. This shift supports improved outcomes and better quality of life for patients with chronic autoimmune conditions. Rising clinical trial activity and regulatory approvals highlight the focus on precision-based treatment models.
- For instance, Provention Bio’s teplizumab demonstrated a median delay of 24 months in the onset of clinical Type 1 diabetes in its Phase III trial.
Expansion of Digital Health Integration and Advanced Treatment Delivery Models:
The market is witnessing stronger adoption of digital tools that support autoimmune therapy management. It includes remote patient monitoring, telemedicine consultations, and mobile health apps that improve treatment adherence. Pharmaceutical companies are collaborating with digital health providers to create integrated platforms for patient support. Growth in infusion centers and home-based drug delivery options is also expanding access to advanced therapies. This shift reflects patient preference for convenient and cost-effective care solutions. Enhanced delivery models help manage long-term treatment regimens, reducing hospital visits and improving compliance. Combined with digital health adoption, these innovations strengthen the efficiency and scalability of autoimmune care delivery.
- For example, Biogen Australia and New Zealand funded a home infusion nursing model that deploys highly experienced registered nurses to administer natalizumab infusions with comprehensive safety monitoring, successfully providing care at home for patients with multiple sclerosis since 2019.
Market Challenges Analysis:
High Cost of Therapies and Limited Accessibility:
The autoimmune treatment market faces significant challenges due to the high cost of biologics, biosimilars, and advanced immunotherapies. Many of these treatments require long-term administration, creating heavy financial burdens for patients and healthcare systems. Limited accessibility in low- and middle-income countries restricts adoption, leaving large patient populations underserved. It intensifies disparities in healthcare outcomes between developed and developing regions. Pricing pressures also hinder the introduction of innovative drugs, with companies balancing affordability and profitability. Delays in reimbursement approvals further complicate patient access to advanced therapies.
Complex Disease Nature and Risk of Adverse Effects:
Autoimmune disorders are complex and often poorly understood, making diagnosis and treatment challenging. Patients respond differently to therapies, which creates uncertainty in achieving consistent clinical outcomes. The autoimmune treatment market must also address concerns about long-term safety, since many drugs increase susceptibility to infections and other side effects. It places pressure on regulators to implement strict approval guidelines, which can delay new product launches. Clinical trial failures due to unpredictable immune responses add further risk for pharmaceutical companies. High attrition rates in research pipelines highlight the difficulty of developing effective and safe treatment options.
Market Opportunities:
Growing Demand for Personalized and Precision Medicine:
The autoimmune treatment market presents strong opportunities through the expansion of personalized and precision medicine. Tailored therapies based on genetic profiling and biomarker analysis are improving treatment effectiveness and patient safety. It enables physicians to prescribe targeted options that reduce trial-and-error in medication selection. The integration of artificial intelligence and advanced diagnostics further enhances precision approaches. Rising investment in companion diagnostics supports faster adoption of personalized treatment plans. Pharmaceutical companies are aligning research pipelines with these trends to capture long-term growth potential.
Expanding Role of Emerging Markets and Biosimilars:
Emerging economies offer significant growth opportunities with rising healthcare investments and expanding infrastructure. Increasing awareness and government-led initiatives improve diagnosis and treatment rates across these regions. It opens new markets for affordable biosimilars, which can replace costly biologics and improve access. Local manufacturing partnerships support cost reductions and greater availability of therapies. Rising middle-class populations in Asia-Pacific and Latin America create robust demand for effective treatment options. The autoimmune treatment market benefits from this expansion by diversifying revenue streams and reducing reliance on mature markets.
Market Segmentation Analysis:
By Indication:
The autoimmune treatment market is segmented by indication into rheumatoid arthritis, lupus, multiple sclerosis, inflammatory bowel disease, psoriasis, and others. Rheumatoid arthritis leads due to high global prevalence and strong adoption of biologics. It benefits from advanced treatment options and significant research investments. Multiple sclerosis and inflammatory bowel disease are gaining traction with the rise of targeted immunotherapies. Increasing awareness and improved diagnostic practices further support strong demand across all major indications.
- For Instance, As of March 2023, Johnson & Johnson had stated that over 500,000 patients had been treated with Stelara (ustekinumab) in the United States alone for all approved indications
By Drug Class:
Segmentation by drug class includes immunosuppressants, anti-inflammatory drugs, biologics, biosimilars, and others. Biologics dominate with higher efficacy and improved safety profiles compared to conventional therapies. It is supported by the growing introduction of biosimilars that reduce treatment costs and increase accessibility. Immunosuppressants continue to hold relevance in standard care, particularly for chronic conditions requiring long-term management. Anti-inflammatory drugs serve as first-line therapies in mild to moderate cases, creating steady demand. Continuous pipeline expansion strengthens the role of biologics and biosimilars in reshaping treatment practices.
- For Instance, In March 2025, Amgen announced positive, full results from the Phase 3 WAYPOINT trial for its biologic Tezspire, demonstrating a rapid and sustained effect in patients with chronic rhinosinusitis with nasal polyps (CRSwNP).
By Sales Channel:
By sales channel, the market is divided into hospital pharmacies, retail pharmacies, and online pharmacies. Hospital pharmacies account for the largest share due to high prescription volumes and access to specialty biologics. It benefits from integration with advanced healthcare facilities that support comprehensive treatment. Retail pharmacies remain vital for conventional drugs and maintenance therapies. Online pharmacies are expanding rapidly, driven by convenience and growing acceptance of digital healthcare platforms. Increasing patient reliance on e-commerce solutions highlights the future growth potential of this channel.
Segmentations:
By Indication:
- Rheumatoid Arthritis
- Lupus
- Multiple Sclerosis
- Inflammatory Bowel Disease
- Psoriasis
- Others
By Drug Class:
- Immunosuppressants
- Anti-inflammatory Drugs
- Biologics
- Biosimilars
- Others
By Sales Channel :
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
By Region:
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America:
North America accounted for 44.2% market share in 2024, supported by high healthcare spending and strong infrastructure. The autoimmune treatment market in this region benefits from early adoption of biologics, advanced diagnostics, and precision medicine. It is strengthened by a concentration of leading pharmaceutical companies and robust clinical trial activity. Government support through favorable reimbursement policies enhances patient access to costly therapies. Rising prevalence of autoimmune conditions such as rheumatoid arthritis and multiple sclerosis continues to drive demand. Research collaborations between academic institutions and industry further accelerate innovation in treatment options.
Europe:
Europe held 29.6% market share in 2024, driven by increased uptake of biologics and biosimilars. The autoimmune treatment market is shaped by advanced healthcare systems and strong regulatory frameworks that promote safe adoption of new therapies. It benefits from government initiatives focused on chronic disease management and sustainability in healthcare delivery. The region shows consistent demand growth from countries such as Germany, France, and the United Kingdom. Rising investment in biosimilar development is making treatments more affordable and accessible. Expanding patient awareness and diagnostic capabilities also support wider treatment adoption across diverse autoimmune conditions.
Asia-Pacific:
Asia-Pacific recorded 18.5% market share in 2024 and is expected to grow at the fastest rate. The autoimmune treatment market is expanding rapidly due to rising patient populations in China and India. It is fueled by improving healthcare infrastructure and increased investment in advanced therapies. Growing awareness and higher diagnosis rates strengthen the outlook for sustained adoption. Local partnerships between global pharmaceutical companies and regional players improve market penetration. Government-led healthcare reforms and supportive pricing policies are widening access to biologics and biosimilars. Expanding middle-class populations with higher healthcare spending power further support long-term growth.
Key Player Analysis:
- Abbott Laboratories
- DIAsource ImmunoAssays SA
- Bio-Rad Laboratories, Inc.
- Euroimmun AG (Perkin Elmer)
- Hemagen Diagnostics
- Myriad Genetics
- F. Hoffmann-la Roche Ltd.
- Quest Diagnostics
- SQI Diagnostics Inc.
- Siemens Healthineers Inc
- Thermo Fisher Scientific Inc
Competitive Analysis:
The autoimmune treatment market is highly competitive, with global and regional players focusing on innovation and expansion. Key companies include Abbott Laboratories, DIAsource ImmunoAssays SA, Bio-Rad Laboratories Inc., Euroimmun AG (Perkin Elmer), Hemagen Diagnostics, Myriad Genetics, F. Hoffmann-La Roche Ltd., Quest Diagnostics, and SQI Diagnostics Inc. It is characterized by strong investments in biologics, biosimilars, and advanced diagnostic tools that enhance accuracy and treatment outcomes. Companies are expanding their pipelines with targeted therapies and investing in research collaborations to strengthen their market positions. Strategic mergers, acquisitions, and partnerships are used to expand distribution networks and improve access to advanced therapies. Growing emphasis on personalized medicine and companion diagnostics has pushed firms to integrate technology-driven solutions. Intense competition continues to encourage product innovation, pricing strategies, and geographic expansion, ensuring that the autoimmune treatment market remains dynamic and research-focused.
Recent Developments:
- In May 2025, Abbott Laboratories received U.S. FDA approval for the Tendyne transcatheter mitral valve replacement system, a new device for treating mitral valve disease.
- In July 2025, Bio-Rad Laboratories launched four new Droplet Digital PCR platforms, including the QX Continuum ddPCR system, expanding genomic and diagnostic capabilities.
Report Coverage:
The research report offers an in-depth analysis based on Indication, Drug Class, Sales Channel and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The autoimmune treatment market will witness strong momentum from continued advancements in biologics and targeted therapies.
- Growing adoption of biosimilars will improve affordability and expand patient access to advanced treatments.
- Rising focus on personalized medicine will drive demand for biomarker-based and precision therapies.
- Integration of artificial intelligence and digital health tools will enhance diagnostics and treatment outcomes.
- Expanding research collaborations between pharmaceutical companies and academic institutions will accelerate drug discovery.
- Regulatory support for faster approvals of innovative therapies will shorten time-to-market for new products.
- Emerging economies will play a larger role with increasing healthcare investments and infrastructure growth.
- Greater emphasis on patient-centric care models will strengthen long-term treatment adherence and outcomes.
- Development of oral formulations and self-administered therapies will improve convenience for patients.
- Sustainability efforts in drug development and healthcare delivery will shape future industry practices.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the autoimmune treatment market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the autoimmune treatment market projected to grow between 2024 and 2032?
Which autoimmune treatment market segment held the largest share in 2024?
What are the primary factors fueling the growth of the autoimmune treatment market?
Who are the leading companies in the autoimmune treatment market?
Which region commanded the largest share of the autoimmune treatment market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Autoimmune Treatment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Autoimmune Treatment Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 166.13 billion → 2032: USD 207.2 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Autoimmune Treatment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Autoimmune Treatment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Autoimmune Treatment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Autoimmune Treatment Market Drivers
- 3.3 Autoimmune Treatment Market Restraints & Challenges
- 3.4 Autoimmune Treatment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Autoimmune Treatment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Autoimmune Treatment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Autoimmune Treatment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Autoimmune Treatment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Autoimmune Treatment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Autoimmune Treatment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Autoimmune Treatment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Autoimmune Treatment Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Autoimmune Treatment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Autoimmune Treatment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Autoimmune Treatment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Autoimmune Treatment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Autoimmune Treatment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Autoimmune Treatment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Autoimmune Treatment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Autoimmune Treatment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Autoimmune Treatment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Autoimmune Treatment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Autoimmune Treatment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
