
Market Overview
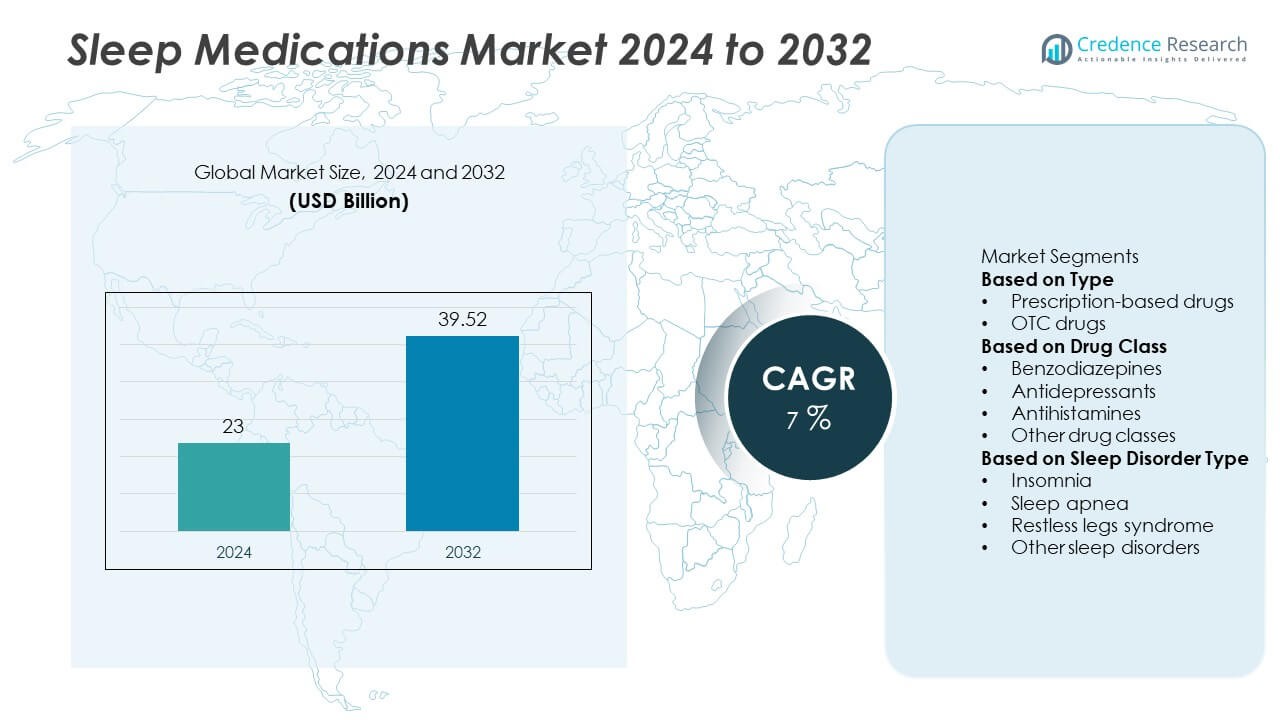
The Sleep Medications Market was valued at USD 23 billion in 2024 and is projected to reach USD 39.52 billion by 2032, growing at a CAGR of 7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Sleep Medications Market Size 2024 | USD 23 Billion |
| Sleep Medications Market, CAGR | 7% |
| Sleep Medications Market Size 2032 | USD 39.52 Billion |
The sleep medications market is led by major companies such as Teva Pharmaceuticals, Pfizer Inc., Takeda Pharmaceutical Company Limited, Sunovion Pharmaceuticals Inc., Novartis A, Johnson & Johnson, Eisai Co., Ltd., Merck and Co Inc., Sanofi SA, and Vanda Pharmaceuticals. These players dominate through strong product portfolios, continuous R&D investments, and innovations in non-addictive and extended-release formulations. Strategic partnerships and the introduction of orexin receptor antagonists have enhanced their global market presence. North America emerged as the leading region with a 41.5% market share in 2024, driven by high insomnia prevalence, advanced healthcare infrastructure, and increasing adoption of both prescription and over-the-counter sleep aids.
Market Insights
- The sleep medications market was valued at USD 23 billion in 2024 and is projected to reach USD 39.52 billion by 2032, growing at a CAGR of 7% during the forecast period.
- Increasing prevalence of insomnia, sleep apnea, and other sleep-related disorders is driving strong demand for both prescription and OTC medications worldwide.
- Market trends indicate a shift toward non-habit-forming and natural formulations, supported by advancements in digital sleep tracking and personalized treatment approaches.
- Key players such as Pfizer Inc., Teva Pharmaceuticals, and Merck & Co Inc. are focusing on new drug launches, partnerships, and R&D investments to strengthen their competitive edge.
- North America led with a 41.5% share in 2024, followed by Europe with 28.6%, while Asia-Pacific held 22.8% as the fastest-growing region; the prescription-based drugs segment dominated with a 67.4% share, driven by clinical efficacy and physician-recommended treatments.
Market Segmentation Analysis:
By Type
The prescription-based drugs segment dominated the sleep medications market with a 67.4% share in 2024, driven by rising diagnoses of chronic insomnia and sleep apnea. These medications are preferred for their clinically proven efficacy and physician-supervised use. Growing demand for targeted therapies, such as non-benzodiazepine hypnotics, supports sustained segment growth. The over-the-counter (OTC) segment is expanding steadily due to increasing consumer awareness and accessibility, especially for mild sleep disturbances. Retail pharmacies and e-commerce platforms further enhance OTC product reach across developed and emerging economies.
- For instance, Eisai Co., Ltd. distributes its prescription sleep medication Dayvigo® (lemborexant) in more than 25 countries, including the United States, with approved dosing of 5 mg and 10 mg once nightly.
By Drug Class
The benzodiazepines segment held the largest share of 38.9% in 2024, attributed to their effectiveness in treating severe insomnia and anxiety-induced sleep disorders. Despite concerns over dependency risks, their short-term therapeutic benefits maintain strong clinical demand. The antidepressant class is also witnessing growth due to dual benefits in managing depression-related sleep disturbances. Antihistamines are gaining traction as non-prescription alternatives for mild insomnia cases, supported by their safety and affordability. Continuous development of safer, extended-release formulations is driving innovation across all drug classes.
- For instance, Teva Pharmaceuticals manufactures clonazepam and temazepam formulations across its global portfolio in regulated GMP facilities. Temazepam has a mean half-life of 9 to 15 hours and is known for having a minimal "hangover effect," reducing residual next-day sedation compared to some other longer-acting benzodiazepines.
By Sleep Disorder Type
The insomnia segment led the market with a 54.7% share in 2024, reflecting the high global prevalence of this condition driven by stress, lifestyle disorders, and mental health issues. Increasing awareness about the impact of sleep quality on overall health fuels demand for effective therapies. Sleep apnea follows as the second-largest segment, supported by growing use of adjunctive medications with CPAP therapy. Treatments for restless legs syndrome and other circadian rhythm disorders are expanding, driven by better diagnosis rates and ongoing research in neuropharmacology.
Key Growth Drivers
Rising Prevalence of Sleep Disorders
The global increase in sleep disorders such as insomnia, sleep apnea, and restless legs syndrome is driving strong demand for sleep medications. Sedentary lifestyles, high stress levels, and irregular work schedules contribute to poor sleep health. According to the American Sleep Association, nearly 30% of adults experience short-term insomnia, with 10% facing chronic forms. This growing patient pool, along with rising diagnosis and treatment awareness, is boosting prescription drug sales and supporting market expansion across both developed and emerging economies.
- For instance, Merck & Co., Inc. reported in clinical trials that its dual orexin receptor antagonist Belsomra® (suvorexant) demonstrated efficacy in treating insomnia. In one study in patients with mild-to-moderate Alzheimer's disease and insomnia, Belsomra (at 10 mg or 20 mg) showed a mean increase in total sleep time of 28.2 minutes and an improvement in wake after persistent sleep onset (WASO) of 15.7 minutes compared to placebo.
Growing Awareness of Mental Health and Sleep Hygiene
Increased public awareness regarding the connection between mental health and sleep quality is fueling demand for effective therapeutic solutions. Consumers are becoming more proactive in seeking medical advice for sleep management, supported by educational campaigns and mental wellness initiatives. The inclusion of sleep health in global health policies and workplace wellness programs is also expanding market reach. Healthcare professionals increasingly recommend tailored pharmacological and behavioral therapies to manage chronic sleep disorders effectively.
- For instance, Johnson & Johnson has developed the investigational drug seltorexant for major depressive disorder with insomnia symptoms. In a Phase 3 clinical trial for adults, seltorexant was shown to improve depressive symptoms and sleep disturbances.
Advancements in Drug Development and Delivery Technologies
Pharmaceutical innovations are reshaping the sleep medications market by introducing safer, non-habit-forming alternatives. Companies are focusing on controlled-release formulations and novel mechanisms of action to enhance sleep duration and reduce dependency risks. Developments in melatonin receptor agonists and orexin antagonists offer better-tolerated treatment options. Furthermore, digital therapeutics and smart dosing systems are improving patient adherence and therapy outcomes. These advancements are expected to create long-term growth opportunities by addressing unmet clinical needs and enhancing overall sleep quality.
Key Trends & Opportunities
Shift Toward Non-Addictive and Natural Sleep Aids
Growing concerns about dependency and side effects associated with conventional sedatives are shifting consumer preference toward non-addictive and natural formulations. Melatonin-based supplements, herbal extracts, and CBD-infused sleep aids are gaining traction in both retail and online markets. Pharmaceutical companies are investing in plant-based active ingredients and low-risk compounds that provide mild sedation without withdrawal effects. This trend reflects a broader movement toward holistic and preventive sleep care, offering significant opportunities for product diversification and expansion into the wellness segment.
- For instance, Takeda Pharmaceutical Company Limited developed its investigational orexin receptor 2 agonist, Oveporexton (TAK-861), which demonstrated statistically significant and clinically meaningful improvements in excessive daytime sleepiness and cataplexy in patients with narcolepsy type 1 during Phase 3 clinical trials.
Integration of Digital Therapeutics and Personalized Sleep Solutions
The rise of digital therapeutics and wearable technology is transforming sleep disorder management. Apps and smart devices capable of tracking sleep patterns enable personalized medication schedules and behavioral insights. Pharmaceutical companies are collaborating with digital health platforms to develop integrated treatment models combining pharmacological and non-pharmacological approaches. AI-based diagnostics and predictive analytics further improve sleep disorder detection and therapy customization, opening new growth avenues for patient-centric sleep care solutions.
- For instance, digital therapeutics platform Kaia Health has demonstrated positive outcomes for sleep quality in studies related to its musculoskeletal (MSK) and Chronic Obstructive Pulmonary Disease (COPD) apps.
Key Challenges
Side Effects and Risk of Dependency
The long-term use of certain sleep medications, especially benzodiazepines and sedative-hypnotics, poses risks of tolerance, dependence, and cognitive impairment. These side effects limit prescription durations and discourage long-term usage. Healthcare authorities emphasize non-pharmacological therapies, such as cognitive behavioral therapy for insomnia (CBT-I), as first-line treatment. To overcome this, manufacturers are investing in developing safer compounds and extended-release formulations that minimize side effects while maintaining therapeutic efficacy and safety.
Stringent Regulatory Frameworks and Generic Competition
Stringent approval requirements and patent expirations challenge market growth and profitability. Regulatory agencies closely monitor the safety profiles and addiction potential of new sleep drugs, often prolonging approval timelines. Meanwhile, generic competition exerts pricing pressure on established brands, particularly in mature markets like the U.S. and Europe. Companies must balance innovation with affordability while maintaining compliance with international standards. Strategic differentiation and R&D in novel drug classes are essential to mitigate these challenges and sustain long-term competitiveness.
Regional Analysis
North America
North America dominated the sleep medications market with a 41.5% share in 2024, driven by high prevalence of insomnia and stress-related disorders. The U.S. leads the region with advanced healthcare infrastructure, strong awareness of sleep hygiene, and widespread access to prescription and OTC drugs. Rising adoption of digital health tools for sleep monitoring and increasing telemedicine consultations are further enhancing accessibility. The presence of leading pharmaceutical companies and active R&D in novel sleep therapeutics continue to strengthen North America’s position as the global leader in sleep disorder treatment.
Europe
Europe accounted for a 28.6% market share in 2024, supported by an aging population and growing cases of sleep apnea and depression-related insomnia. Countries such as Germany, France, and the U.K. are key contributors, driven by early diagnosis and healthcare reimbursement policies. The region’s strong regulatory framework promotes the development of safe and effective sleep medications. Increased focus on non-habit-forming drugs and integration of behavioral therapies alongside medication are enhancing treatment outcomes, positioning Europe as a mature and innovation-driven market for sleep-related therapeutics.
Asia-Pacific
Asia-Pacific held a 22.8% share in 2024, emerging as the fastest-growing region due to rising stress levels, changing lifestyles, and urbanization. Growing awareness of mental health, increasing healthcare access, and expanding pharmaceutical distribution networks are driving demand. China, Japan, and India lead regional growth with strong adoption of both prescription and herbal sleep aids. The rising prevalence of insomnia among working professionals and the expansion of online pharmacies are further supporting market development. Government initiatives addressing sleep health awareness continue to propel the region’s rapid expansion.
Latin America
Latin America captured a 4.5% market share in 2024, driven by growing healthcare infrastructure and increasing awareness of sleep-related health issues. Brazil and Mexico dominate the regional market, supported by rising access to over-the-counter medications and improved diagnostic capabilities. Expanding urban populations and changing work patterns are contributing to higher incidences of sleep disorders. Although pharmaceutical access remains limited in rural areas, multinational drug manufacturers are investing in market penetration strategies, offering affordable therapies and educational programs to support long-term sleep health management.
Middle East & Africa
The Middle East & Africa region accounted for a 2.6% market share in 2024, supported by rising lifestyle-related insomnia and growing awareness of mental well-being. The UAE, Saudi Arabia, and South Africa lead the market, with increasing investments in healthcare modernization and pharmacy expansion. Limited specialist availability remains a challenge; however, growing use of OTC sleep aids and herbal alternatives is boosting accessibility. Governments and healthcare providers are increasingly promoting awareness campaigns and partnerships to address sleep health, helping establish a gradual but steady market presence across the region.
Market Segmentations:
By Type
- Prescription-based drugs
- OTC drugs
By Drug Class
- Benzodiazepines
- Antidepressants
- Antihistamines
- Other drug classes
By Sleep Disorder Type
- Insomnia
- Sleep apnea
- Restless legs syndrome
- Other sleep disorders
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The sleep medications market is highly competitive, featuring key players such as Teva Pharmaceuticals, Pfizer Inc., Takeda Pharmaceutical Company Limited, Sunovion Pharmaceuticals Inc., Novartis A, Johnson & Johnson, Eisai Co., Ltd., Merck and Co Inc., Sanofi SA, and Vanda Pharmaceuticals. These companies compete through innovation in drug development, expanding product portfolios, and strategic collaborations. Leading players focus on developing safer, non-habit-forming formulations, including melatonin receptor agonists and dual orexin receptor antagonists, to address unmet needs in insomnia and other sleep disorders. Ongoing R&D investments and clinical trials aim to enhance drug efficacy, safety, and patient compliance. Partnerships with digital health platforms and healthcare providers are strengthening integrated treatment approaches. Furthermore, the rise in generic drug competition and regional expansion initiatives drive continuous innovation and price optimization across both prescription and over-the-counter sleep medication markets.
Key Player Analysis
- Teva Pharmaceuticals
- Pfizer Inc.
- Takeda Pharmaceutical Company Limited
- Sunovion Pharmaceuticals Inc.
- Novartis A
- Johnson & Johnson
- Eisai Co., Ltd.
- Merck and Co Inc.
- Sanofi SA
- Vanda Pharmaceuticals
Recent Developments
- In September 2025, Vanda Pharmaceuticals Inc. published results in PLOS One indicating that its melatonin-agonist drug HETLIOZ® (tasimelteon) improved sleep among patients with primary insomnia, based on a multicenter, randomized, double-blind, placebo-controlled trial.
- In July 2025, Takeda Pharmaceutical Company Limited announced that its oral orexin-2 receptor agonist investigational drug Oveporexton (TAK‑861) met all primary and secondary endpoints in two Phase III studies in narcolepsy type 1, conducted across 19 countries.
- In May 2025, Eisai Co., Ltd. received approval in China for its orexin receptor antagonist Dayvigo® (lemborexant) for adult insomnia characterised by sleep-onset and/or sleep-maintenance difficulties.
Report Coverage
The research report offers an in-depth analysis based on Type, Drug Class, Sleep Disorder Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for non-addictive and extended-release sleep medications will continue to rise globally.
- Pharmaceutical innovation will focus on orexin receptor antagonists and melatonin-based compounds for safer use.
- Integration of digital therapeutics and wearable devices will enhance personalized sleep treatment.
- Over-the-counter and herbal sleep aids will see strong growth among health-conscious consumers.
- Strategic collaborations between pharma and tech companies will improve drug delivery and monitoring.
- Regulatory agencies will tighten oversight on dependency risks and clinical safety.
- North America will remain dominant, while Asia-Pacific will expand fastest with growing awareness.
- Companies will emphasize R&D for dual-action therapies addressing mental health and sleep.
- Generic drug entry will increase affordability but intensify pricing competition.
- Sustainability and eco-friendly production practices will shape the future of sleep medication manufacturing.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Sleep Medications Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Sleep Medications Market projected to grow between 2025 and 2032?
Which Sleep Medications Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Sleep Medications Market?
Who are the leading companies in the Sleep Medications Market?
Which region commanded the largest share of the Sleep Medications Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 23 billion → 2032: USD 39.52 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Sleep Medications Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Sleep Medications Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Sleep Medications Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Sleep Medications Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Sleep Medications Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Sleep Medications Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Sleep Medications Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Sleep Medications Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 23 billion → 2032: USD 39.52 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Sleep Medications Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Sleep Medications Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Sleep Medications Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Sleep Medications Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

