
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Automotive Cast Iron Cylinder Head Market Size 2024 | USD 6105 million |
| Automotive Cast Iron Cylinder Head Market, CAGR | 5.4% |
| Automotive Cast Iron Cylinder Head Market Size 2032 | USD 9298.44 million |
Market Overview
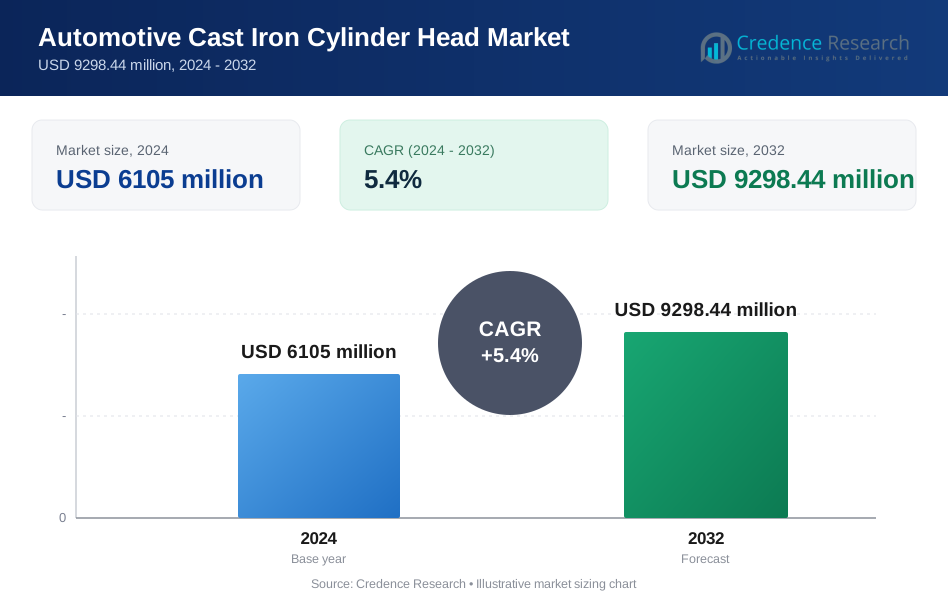
The Automotive Cast Iron Cylinder Head Market is projected to grow from USD 6105 million in 2024 to an estimated USD 9298.44 million by 2032, with a compound annual growth rate (CAGR) of 5.4% from 2024 to 2032.
Key drivers of the automotive cast iron cylinder head market include the increasing demand for high-performance engines, particularly in the automotive and commercial vehicle sectors. Cast iron cylinder heads are favored for their durability, cost-effectiveness, and ability to withstand high temperatures and pressures, which make them suitable for both gasoline and diesel engines. The growing need for efficient fuel consumption and reduced emissions is also driving innovation in engine components, including cylinder heads. Additionally, advancements in automotive manufacturing technologies are enhancing the production process, reducing costs, and improving the quality of cast iron cylinder heads.
Regionally, Asia Pacific is expected to dominate the market, primarily driven by the high production and demand for automobiles in countries like China, India, and Japan. The region’s rapid industrialization and large-scale automotive manufacturing facilities contribute significantly to the growth of the market. North America and Europe also contribute to the automotive cast iron cylinder head market, driven by the presence of key automotive manufacturers and the continued adoption of heavy-duty vehicles. Meanwhile, the Middle East and Africa are witnessing gradual growth as the automotive industry expands in the region, particularly in markets such as the UAE and South Africa.
Market Insights:
- The Automotive Cast Iron Cylinder Head Market is projected to grow from USD 6105 million in 2024 to USD 9298.44 million by 2032, with a CAGR of 5.4%.
- Increasing demand for high-performance engines and durable, cost-effective components drives market growth, especially in automotive and commercial vehicle sectors.
- The need for efficient fuel consumption, lower emissions, and advancements in engine technologies is boosting the demand for cast iron cylinder heads.
- The rising popularity of alternative materials, such as aluminium, for engine components may pose a challenge to the cast iron cylinder head market.
- High production costs and the complexity of manufacturing processes could limit the growth of the market in certain regions.
- Asia Pacific leads the market, driven by high automotive production in China, India, and Japan, along with rapid industrialization.
- North America and Europe continue to contribute significantly to the market, supported by strong automotive manufacturing bases and demand for heavy-duty vehicles.
Market Drivers:
Increasing Demand for High-Performance Engines:
The increasing demand for high-performance engines in the automotive and commercial vehicle sectors continues to drive the automotive cast iron cylinder head market. Cast iron is favored for its durability, heat resistance, and ability to withstand high pressures, making it ideal for both gasoline and diesel engines. As global automotive manufacturers strive to meet growing consumer expectations for fuel efficiency, performance, and reliability, the need for robust engine components like cast iron cylinder heads remains critical. For Instance, The International Energy Agency (IEA) reports that the global electric vehicle (EV) stock reached 10 million vehicles in 2020, with a year-on-year growth of 43%. This expansion in EVs, alongside the continued need for advanced engine technologies in traditional vehicles, significantly drives the demand for engine components, including cast iron cylinder heads. Furthermore, the IEA forecasts that by 2030, EV sales will account for 50% of global car sales, which will further contribute to the growth of engine components for both electric and hybrid vehicles.
Rising Focus on Fuel Efficiency and Reduced Emissions:
Governments worldwide are imposing stricter emissions regulations, forcing automakers to adopt more efficient and eco-friendly technologies. This growing emphasis on reducing fuel consumption and emissions presents opportunities for the automotive cast iron cylinder head market. Cast iron, being cost-effective and durable, remains a key material in meeting the performance standards required for compliance with these regulations. For Instance, in 2020, the European Union introduced a new regulation to reduce CO2 emissions from cars by 37.5% by 2030, compared to 2021 levels. The European Commission’s climate policy has been instrumental in setting ambitious targets to reduce vehicle emissions, thereby driving the demand for more efficient engine technologies, including cast iron cylinder heads. Similarly, in the U.S., the Environmental Protection Agency (EPA) estimates that the average fuel economy for new cars and light trucks was 25.7 miles per gallon (mpg) in 2020, and regulations are pushing automakers to meet more stringent fuel efficiency standards moving forward.
Technological Advancements in Automotive Manufacturing:
Advancements in manufacturing technologies, such as 3D printing, automated production, and computer-aided design (CAD), have enabled more precise, cost-effective, and high-performance cast iron cylinder heads. These innovations are playing a crucial role in improving the efficiency and quality of engine components, which is a significant factor in the growing demand for cast iron cylinder heads in the automotive industry. For Instance, In 2021, the U.S. Department of Energy (DOE) funded more than $100 million to accelerate the adoption of advanced manufacturing technologies within the automotive sector. This funding supports research into new manufacturing processes, including additive manufacturing (3D printing), which can reduce material waste and improve the production of complex components like cylinder heads. In particular, the DOE’s Advanced Manufacturing Office has been investing in technologies that enhance the performance and efficiency of automotive components, further increasing the demand for improved cast iron cylinder heads.
Expansion in Emerging Markets:
Emerging markets, particularly in Asia Pacific and Latin America, are driving significant growth in the global automotive sector. As nations like China, India, and Brazil continue to industrialize, the demand for automobiles and automotive components, including cast iron cylinder heads, has risen substantially. The increasing purchasing power and expanding middle class in these regions are fueling the growth of the automotive industry. For Instance, according to the World Bank, India’s automotive sector accounted for 7.1% of the country’s GDP in 2020, and the market is expected to grow at an annual rate of 8% over the next five years. This expansion, particularly in the automotive manufacturing sector, is expected to drive significant demand for key engine components such as cast-iron cylinder heads. Similarly, China, being the largest automobile market globally, is projected to continue growing at a compound rate of 5% annually over the next decade, creating further opportunities for cast iron cylinder head manufacturers.
Market Trends:
Increasing Adoption of Hybrid and Electric Vehicles:
As the automotive industry shifts towards electrification, there is a noticeable trend in the rising adoption of hybrid and electric vehicles (EVs). This shift is largely driven by stricter environmental regulations and growing consumer demand for more sustainable transportation options. Cast iron cylinder heads, known for their durability and cost-effectiveness, remain crucial components in hybrid and traditional internal combustion engines, while manufacturers adapt to the evolving requirements of electric and hybrid powertrains. For Instance, The U.S. Environmental Protection Agency (EPA) has been promoting the adoption of hybrid and electric vehicles through stringent fuel economy standards. In 2021, the EPA set an ambitious target to reduce the average carbon dioxide (CO2) emissions of new cars and trucks by 40% by 2030, compared to 2021 levels. As part of this initiative, the U.S. government has been encouraging automakers to adopt hybrid and fully electric vehicles, which still rely on traditional engine components such as cast-iron cylinder heads for their hybrid powertrains.
Shift Toward Lightweighting and Material Innovation:
The trend toward lightweighting and the use of innovative materials is significantly impacting the automotive industry, including the production of engine components such as cast-iron cylinder heads. Manufacturers are increasingly seeking materials that offer high strength while reducing weight to improve vehicle efficiency, fuel economy, and overall performance. While cast iron remains the material of choice for its durability, there is growing interest in material innovations that can complement or, in some cases, replace traditional cast iron components. For Instance, The U.S. Department of Energy (DOE) has been funding research into lightweight materials for the automotive sector, focusing on reducing the weight of vehicle components without compromising performance. In 2020, the DOE allocated $40 million toward projects aimed at advancing material innovation, including the development of lightweight metals and composites for use in automotive manufacturing. This trend is also reflected in the automotive industry's ongoing investment in alternative materials like aluminum and magnesium alloys, which are being used to reduce the weight of engine components while maintaining strength and performance. The DOE's commitment to promoting energy-efficient and sustainable materials will likely drive further demand for innovative solutions in the automotive cast iron cylinder head market.
Market Challenges Analysis:
Raw Material Price Fluctuations:
One of the key challenges facing the automotive cast iron cylinder head market is the fluctuation in the prices of raw materials, particularly cast iron and other alloys used in the manufacturing process. The cost of raw materials can vary significantly based on global demand, geopolitical factors, and supply chain disruptions. For instance, the prices of key materials such as iron ore and scrap metal have seen volatile shifts due to factors like mining restrictions, environmental regulations, and trade tariffs imposed by countries. This unpredictability in raw material costs can lead to increased production costs, affecting profit margins for manufacturers. Companies in the automotive cast iron cylinder head market must account for these fluctuations, which can also make long-term planning and budgeting more challenging. Furthermore, the rising demand for electric vehicles and alternative materials in the automotive industry could place additional strain on the supply of traditional cast iron and increase competition for these essential raw materials.
Technological Advancements and Production Challenges:
As the automotive industry continues to evolve with advancements in electric vehicles (EVs) and hybrid powertrains, manufacturers are facing the challenge of integrating new technologies into traditional cast iron cylinder head production. The increasing adoption of lightweight materials, such as aluminum and magnesium, for engine components puts pressure on manufacturers to either innovate or adjust to the demand for more sustainable and efficient options. Additionally, the growing trend of automation and additive manufacturing (3D printing) in engine component production requires significant investment in new technologies and production capabilities. For manufacturers of cast iron cylinder heads, adapting to these advancements while maintaining high quality and cost-effectiveness is crucial. Moreover, the complexity of modern engine designs and the need for precision casting further complicate the production process, requiring specialized skills and equipment. Failure to adapt to these technological shifts could result in higher costs, longer lead times, and reduced competitiveness in the global market.
Market Opportunities:
The automotive cast iron cylinder head market presents significant opportunities driven by technological advancements in manufacturing processes and materials. Innovations such as the development of advanced casting techniques, including high-pressure die-casting and sand casting, are improving production efficiency and product quality. These advancements enable manufacturers to produce cast iron cylinder heads that meet the increasing performance and durability demands of modern engines. Furthermore, the integration of computer-aided design (CAD) and 3D printing technologies in the production process allows for more precise engineering, optimizing the cylinder head’s functionality and reducing material waste. As the automotive industry continues to evolve, particularly with a focus on electrification and efficiency, there is ample opportunity for cast iron cylinder head manufacturers to innovate and stay competitive by leveraging these technological improvements.
Emerging markets, particularly in Asia Pacific, Africa, and Latin America, offer lucrative growth opportunities for the automotive cast iron cylinder head market. Rapid industrialization, increasing vehicle production, and rising consumer demand for automobiles are driving the need for high-quality engine components. In countries like India, China, and Brazil, a growing middle class and expanding infrastructure projects are fueling the growth of the automotive sector, thereby increasing the demand for automotive parts, including cast iron cylinder heads. Additionally, the growing trend toward electric vehicles (EVs) in these regions presents an opportunity to adapt cast iron cylinder heads to meet new engine requirements for hybrid and electric powertrains. Manufacturers can also benefit from lower labor costs and expanding local manufacturing capabilities in these emerging regions, providing opportunities for cost-effective production and market expansion.
Market Segmentation Analysis:
By Type: The market for automotive cast iron cylinder heads is primarily categorized into two types: standard and high-performance cylinder heads. Standard cast iron cylinder heads dominate the market due to their widespread use in conventional gasoline and diesel engines. They offer durability, heat resistance, and cost-effectiveness. High-performance cast iron cylinder heads, on the other hand, cater to the growing demand for enhanced engine performance, especially in sports cars, commercial vehicles, and heavy-duty engines.
By Technology: Technological advancements play a critical role in shaping the automotive cast iron cylinder head market. The production techniques used for these components include traditional sand casting, die casting, and advanced processes like 3D printing and precision casting. Sand casting is the most widely used method due to its cost-effectiveness and suitability for mass production. However, precision casting and die casting are gaining traction for their ability to produce more complex and lightweight components, improving engine performance and efficiency.
By End-User: The automotive cast iron cylinder head market serves a wide range of end-users, including automotive manufacturers, commercial vehicle manufacturers, and aftermarket suppliers. Automotive manufacturers represent the largest end-user segment, driven by the continuous demand for personal vehicles across regions. The commercial vehicle sector, which includes trucks, buses, and construction vehicles, also significantly contributes to the market due to the need for durable and high-performance engine components that can withstand heavy-duty operations.
Segmentations:
Based on Product Type:
- Standard Cast Iron Cylinder Heads
- High-Performance Cast Iron Cylinder Heads
Based on Technology:
- Sand Casting
- Die Casting
- Precision Casting
- 3D Printing
- Additive Manufacturing
Based on End-User
- Automotive Manufacturers
- Commercial Vehicle Manufacturers
- Aftermarket Suppliers
Based on Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a significant share of the automotive cast iron cylinder head market, contributing to a substantial portion of the global demand. The region is expected to maintain a strong presence due to its well-established automotive industry and the presence of leading manufacturers such as Ford, General Motors, and Fiat Chrysler. The market share for North America is estimated to be around 25% of the global market. This dominance is driven by the high demand for both light and heavy-duty vehicles, which require durable and efficient engine components, including cast iron cylinder heads. The U.S. plays a key role in North America's market, supported by its robust automotive production and strong aftermarket sector. As regulatory standards for fuel efficiency and emissions become more stringent, the demand for advanced engine technologies, including cast iron cylinder heads, is increasing. Additionally, the growing trend of adopting hybrid and electric vehicles (EVs) has prompted innovation in engine components, including hybrid powertrains that still utilize cast iron cylinder heads. Furthermore, the commercial vehicle sector, including trucks and buses, continues to drive demand, particularly in the U.S. and Canada. North America’s market is also supported by its mature automotive manufacturing facilities and advanced technologies, ensuring continued growth and expansion of the automotive cast iron cylinder head market in the region.
Europe
Europe also holds a significant share in the automotive cast iron cylinder head market, accounting for approximately 30% of the global market share. The region is home to several key automotive manufacturers such as Volkswagen, BMW, Mercedes-Benz, and Renault, which contribute to the demand for engine components. Europe’s automotive industry is highly regulated, with strict environmental standards driving automakers to focus on producing efficient and high-performance engines. As a result, cast iron cylinder heads, known for their durability and cost-effectiveness, remain crucial in meeting these performance and regulatory demands. The market in Europe is influenced by the growing emphasis on sustainable transportation and the shift towards electric and hybrid vehicles. Although the adoption of alternative materials and powertrains, such as aluminum for lightweighting, is on the rise, cast iron cylinder heads are still an essential component in many hybrid and traditional combustion engines. Germany, as a leader in the European automotive industry, continues to be a major contributor to the market, along with other countries like France and Italy. In addition, the growth of the commercial vehicle market, particularly in the transportation and logistics sectors, boosts the demand for cast iron cylinder heads in heavy-duty engines. With the continued adoption of advanced manufacturing technologies, such as precision casting and 3D printing, Europe is expected to maintain a strong position in the automotive cast iron cylinder head market.
Asia Pacific
Asia Pacific is the largest regional market for automotive cast iron cylinder heads, accounting for approximately 40% of the global market share. This dominance is driven by the rapid industrialization, high vehicle production, and increasing automotive demand in countries such as China, India, and Japan. China is the largest contributor to the market in the region, owing to its position as the world’s largest automobile producer and consumer. The region’s automotive industry has seen rapid growth due to the rising disposable incomes, expanding middle class, and the growing demand for both passenger and commercial vehicles. In Asia Pacific, cast iron cylinder heads are essential components due to their cost-effectiveness and ability to meet the requirements of both gasoline and diesel engines. The growing demand for commercial vehicles, including trucks and buses, in emerging economies like India and China is further boosting the demand for cast iron cylinder heads. In addition, the rise of electric vehicle manufacturing in China, supported by government incentives and policies, is contributing to the overall growth of the automotive component market, including engine parts. However, while the region’s vehicle production volume is high, manufacturers are also facing increasing pressure to innovate and meet environmental standards set by governments in countries like Japan and South Korea. This innovation often involves improving fuel efficiency and reducing emissions, which in turn drives demand for advanced cast iron cylinder heads. As Asia Pacific continues to expand its automotive manufacturing capabilities and production output, the market for cast iron cylinder heads in the region is poised for continued growth.
Key Player Analysis:
- General Motors
- Volkswagen
- Honda Motor Co
- Nissan Motor Corporation
- Mitsubishi Motors Corporation
- Toyota Motor Corporation
- Suzuki Motor Corporation
- SAIC Motor Corporation
- Fiat Chrysler Automobiles
- Ford Motor Company
- Daimler AG
- Hyundai Motor Company
- Mazda
- Renault
- BMW
Competitive Analysis:
The automotive cast iron cylinder head market is highly competitive, with key players focusing on innovation, cost-efficiency, and strategic partnerships to maintain their market position. Leading manufacturers such as Eagle Alloy Inc., Nemak, Linamar Corporation, and Mitsubishi Materials Corporation are dominating the market, leveraging their established expertise in casting technologies and extensive manufacturing capabilities. These companies are investing heavily in research and development to improve the quality, durability, and performance of cast iron cylinder heads, aiming to meet evolving industry demands, such as enhanced fuel efficiency, emissions reduction, and lightweighting. For instance, Strategic collaborations with automotive OEMs (original equipment manufacturers) and Tier 1 suppliers further strengthen their market presence. Additionally, companies are adopting advanced manufacturing processes, including precision casting and 3D printing, to improve production efficiency and reduce costs. However, the market also faces the challenge of increasing competition from alternative materials like aluminum and composite alloys, which offer lightweight properties and better performance for certain applications, especially in the growing electric vehicle sector. To counter this, leading players are focusing on developing hybrid solutions and high-performance cast iron cylinder heads that cater to the demands of both conventional and hybrid powertrains. Moreover, regional players in Asia Pacific, especially in countries like China and India, are becoming increasingly influential due to the surge in automotive production and the growing demand for cost-effective and durable engine components. As a result, the competition remains fierce, with manufacturers continually striving to enhance product quality, reduce lead times, and expand their global footprint.
Recent Developments:
- November 2024: Volkswagen is enhancing its research into eco-friendly alternatives to reduce emissions from traditional cast iron cylinder heads. This initiative aligns with their broader strategy to meet stringent environmental regulations.
- In October 2024, Honda Motor Co. actively researched eco-friendly alternatives to traditional cast iron cylinder heads to reduce emissions and improve fuel efficiency.
- In October 2024, Nissan Motor Corporation focused on developing eco-friendly alternatives for cast iron cylinder heads, aiming to reduce emissions and enhance vehicle performance.
- In November 2024, Mitsubishi Motors Corporation invested in advanced manufacturing technologies to improve the efficiency and performance of their cast iron cylinder heads, integrating smart materials and coatings to enhance durability.
Market Concentration & Characteristics:
The automotive cast iron cylinder head market is characterized by a moderate level of concentration, with a few key players dominating the global landscape, while regional players also hold significant shares. Major companies such as Nemak, Eagle Alloy Inc., Linamar Corporation, and Mitsubishi Materials Corporation are at the forefront, benefiting from economies of scale, extensive manufacturing capabilities, and strong relationships with automotive OEMs and Tier 1 suppliers. These companies invest heavily in research and development to enhance the durability, performance, and cost-efficiency of their cast iron cylinder heads, ensuring they meet the increasingly stringent emissions and fuel efficiency standards. While large players hold substantial market shares, the market is also marked by a number of small and medium-sized companies, especially in Asia Pacific, which contribute to the competitive dynamics by offering cost-effective solutions and catering to regional automotive demand. The market characteristics are defined by a constant push for innovation, driven by the adoption of advanced manufacturing techniques such as precision casting, 3D printing, and automation to improve production efficiency and reduce costs. Additionally, the market is influenced by the shift toward hybrid and electric vehicle powertrains, with manufacturers working to design cylinder heads that can meet the specific needs of these vehicles, including improved fuel efficiency and reduced weight. As a result, the market exhibits a blend of high competition among established players and innovation-driven growth, with an increasing emphasis on sustainable, high-performance, and cost-effective solutions to cater to the global automotive industry’s evolving needs.
Report Coverage:
This report provides a comprehensive analysis of the automotive cast iron cylinder head market, offering detailed insights into the market’s dynamics, segmentation, and regional trends. It covers key market drivers, challenges, opportunities, and future outlook, with a focus on technological advancements, such as precision casting, 3D printing, and additive manufacturing, which are shaping the production of cast iron cylinder heads. The report segments the market by type, including standard and high-performance cylinder heads, as well as by technology, highlighting the key manufacturing processes such as sand casting, die casting, and the emerging 3D printing methods. Additionally, it explores the market based on end-user categories, including automotive manufacturers, commercial vehicle manufacturers, and the aftermarket sector. Regional analysis covers key geographies including North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, with specific focus on leading markets like the U.S., Germany, China, and India. The report also delves into the competitive landscape, providing an overview of major players, their market share, strategic initiatives, and the competitive dynamics driving the market. Furthermore, it highlights market concentration and key industry characteristics, with an emphasis on the evolving landscape due to the shift toward electric vehicles and the growing demand for lightweight materials. Offering both qualitative and quantitative insights, the report is a valuable resource for industry stakeholders, including manufacturers, suppliers, investors, and market researchers, seeking to understand the current market trends, challenges, and opportunities in the automotive cast iron cylinder head market.
Future Outlook:
- The automotive cast iron cylinder head market will continue to benefit from the rising demand for high-performance and durable engine components.
- As global vehicle production expands, especially in emerging markets, the need for cast iron cylinder heads will grow steadily.
- Increased adoption of hybrid and electric vehicles will drive innovations in engine components, including cast iron cylinder heads for hybrid powertrains.
- Stringent government regulations on fuel efficiency and emissions will push automakers to invest in advanced engine technologies, benefiting the cast iron cylinder head market.
- Technological advancements in manufacturing, such as 3D printing and automation, will improve the efficiency and precision of cast iron cylinder head production.
- Emerging materials and lightweight trends will encourage further innovation in cast iron components to enhance performance and reduce vehicle weight.
- The automotive industry’s shift toward sustainability and carbon reduction will influence the design and manufacturing of engine parts, including cast iron cylinder heads.
- Demand for heavy-duty vehicles in sectors like construction and logistics will support the market, especially in North America and Europe.
- Investments in R&D by key automotive manufacturers and government initiatives will accelerate the development of high-performance engine components.
- The continued expansion of automotive manufacturing in Asia Pacific will remain a crucial factor in the growth of the cast iron cylinder head market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Automotive Cast Iron Cylinder Head Market?
What factors are driving the growth of the automotive cast iron cylinder head market?
Why are cast iron cylinder heads preferred for engine manufacturing?
How is the automotive cast iron cylinder head market performing in other regions?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Automotive Cast Iron Cylinder Head Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Automotive Cast Iron Cylinder Head Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 6105 million → 2032: USD 9298.44 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Automotive Cast Iron Cylinder Head Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Automotive Cast Iron Cylinder Head Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Automotive Cast Iron Cylinder Head Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Automotive Cast Iron Cylinder Head Market Drivers
- 3.3 Automotive Cast Iron Cylinder Head Market Restraints & Challenges
- 3.4 Automotive Cast Iron Cylinder Head Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Automotive Cast Iron Cylinder Head Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Automotive Cast Iron Cylinder Head Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Automotive Cast Iron Cylinder Head category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Automotive Cast Iron Cylinder Head Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Automotive Cast Iron Cylinder Head Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Automotive Cast Iron Cylinder Head market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Automotive Cast Iron Cylinder Head Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Automotive Cast Iron Cylinder Head Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Automotive Cast Iron Cylinder Head Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Automotive Cast Iron Cylinder Head (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Automotive Cast Iron Cylinder Head Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Automotive Cast Iron Cylinder Head Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Automotive Cast Iron Cylinder Head Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Automotive Cast Iron Cylinder Head Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Automotive Cast Iron Cylinder Head Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Automotive Cast Iron Cylinder Head Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Automotive Cast Iron Cylinder Head Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Automotive Cast Iron Cylinder Head Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Automotive Cast Iron Cylinder Head Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
