
Market overview
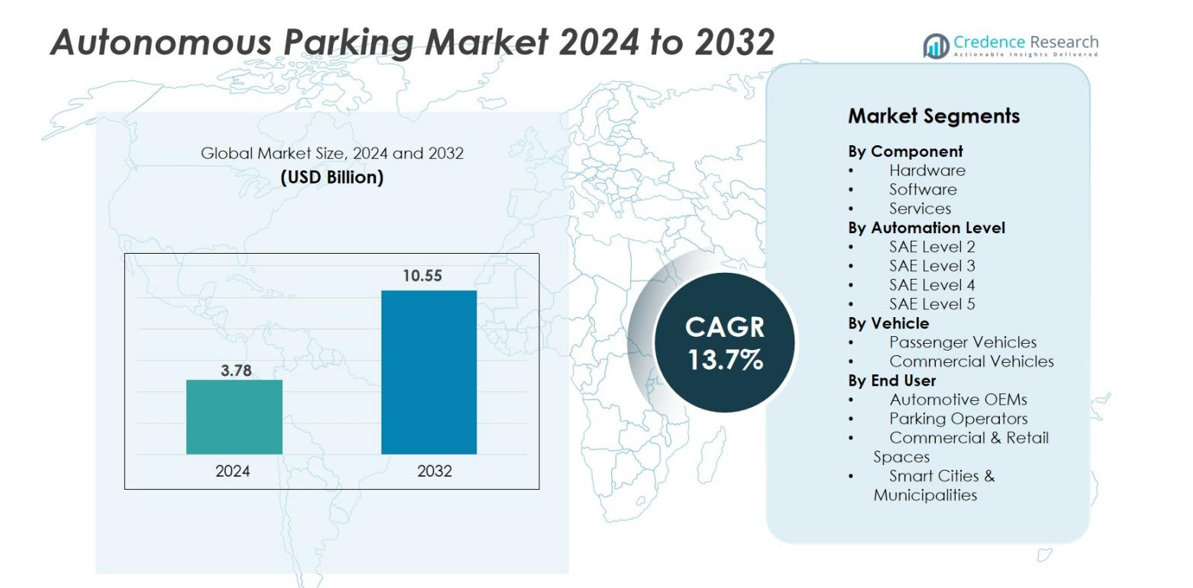
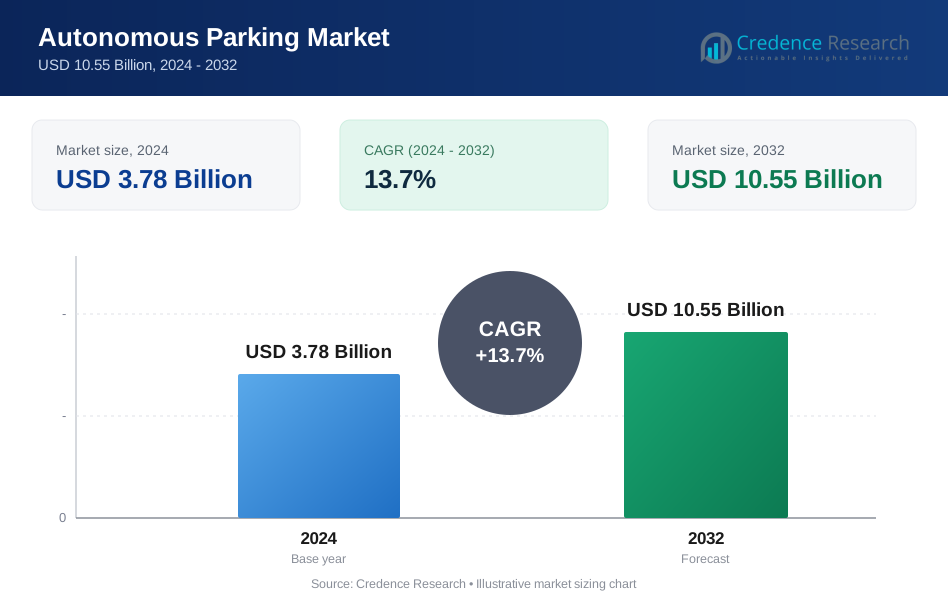
Autonomous Parking market size was valued at USD 3.78 Billion in 2024 and is anticipated to reach USD 10.55 Billion by 2032, at a CAGR of 13.7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Autonomous Parking Market Size 2024 | USD 3.78 Billion |
| Autonomous Parking Market, CAGR | 13.7% |
| Autonomous Parking Market Size 2032 | USD 10.55 Billion |
The Autonomous Parking market is driven by strong competition among global automotive and parking automation companies. Leading players include Tesla, Daimler AG, Robert Bosch GmbH, FCA USA LLC, Skyline Parking AG, Robotic Parking Systems Inc., Unitronics (1989) (R G) Ltd., Klaus Multiparking GmbH, Westfalia Parking, and City Lift Parking LLC. These companies invest in advanced sensors, AI software, and robotic lifts to improve precision and space utilization. North America leads the market with 36% share in 2024, supported by high adoption of premium vehicles and smart parking infrastructure. Europe follows with 31% share due to strong regulatory support and advanced automotive manufacturing. Asia-Pacific holds 24% share and remains the fastest-growing region due to rising urbanization and EV expansion.
Market Insights
- The market was valued at USD 3.78 billion in 2024 and is projected to reach USD 10.55 billion by 2032, growing at a CAGR of 13.7%.
- Demand rises due to higher adoption of ADAS and AI-powered parking systems that reduce collisions in crowded urban areas, while automakers add autonomous parking as a comfort and safety feature in mid-range and premium vehicles.
- SAE Level 4 leads the automation level segment with 44% share, supported by autonomous valet features in commercial complexes and residential buildings, while hardware holds 52% share due to strong usage of sensors and cameras.
- Key companies such as Tesla, Daimler AG, Bosch, and Skyline Parking AG expand adoption through advanced sensing technology, software algorithms, robotic lifts, and cloud-connected parking solutions.
- North America leads the regional share with 36%, followed by Europe at 31% and Asia-Pacific at 24%, supported by smart infrastructure, EV growth, and dense urban development.
Market Segmentation Analysis
By Component
Hardware led the Autonomous Parking market with 52% share in 2024. The hardware group includes sensors, cameras, ultrasonic modules, and radar units. These devices support precise vehicle movement and safe navigation in tight spaces. Rising adoption of sensor-rich ADAS platforms boosts demand. Software held 31% share, driven by real-time mapping and AI-based path planning. Services held 17% share, supported by system maintenance and over-the-air upgrades. Automakers invest in sensor fusion units and high-resolution cameras to improve detection accuracy.
- For instance, Volkswagen Group invested $2.33 billion in Beijing-based robotics company Horizon to advance sensor fusion technology for autonomous vehicle safety systems.
By Automation Level
SAE Level 4 held 44% share in 2024, making it the dominant level. Level 4 systems offer near-full automation without driver input inside parking zones. This segment grows due to automated valet systems in residential and commercial lots. SAE Level 3 accounted for 28%, supported by semi-autonomous steering and braking. SAE Level 2 held 18%, and SAE Level 5 captured 10%, as it is still in early testing. Advancements in AI and edge computing drive Level 4 adoption.
- For instance, Mercedes-Benz and WeRide received official approval in 2024 to test Level 4 automated driving in Beijing with sensor-rich S-Class vehicles capable of fully autonomous driving under specific scenarios.
By Vehicle
Passenger vehicles held 67% share in 2024, making it the leading vehicle category. Carmakers integrate autonomous parking to improve premium comfort and reduce parking stress in cities. Electric vehicles also support this feature due to advanced sensor suites. Commercial vehicles captured 33%, driven by automated fleet operations in logistics hubs and airports. Growing demand for space-efficient parking in urban areas pushes OEMs to add smart parking tech across mid-range and luxury passenger cars.
Key Growth Drivers
Growing Adoption of Advanced Driver Assistance Systems (ADAS)
Rising demand for advanced driver assistance systems fuels autonomous parking adoption across the automotive sector. Automakers integrate parking sensors, high-resolution cameras, and radar modules to reduce collisions in crowded parking spaces. Urban congestion increases the need for automation, especially in smart cities. Automakers also focus on hands-free parking functions to enhance comfort and reduce driver stress. Electric vehicle manufacturers deploy sensor-rich platforms that support automated movement and real-time obstacle detection. Strong investment in AI-based perception and localization improves system accuracy. These developments make autonomous parking a standard feature in premium and mid-range vehicles, supporting market growth.
- For instance, Continental has produced over 200 million radar sensors, which are pivotal in parking assistance and lane departure warnings with ranges up to 300 meters.
Expansion of Smart Infrastructure and Connected Parking Facilities
Demand rises as commercial complexes, airports, and residential towers adopt automated parking systems to maximize space. Property developers deploy smart parking garages with robotic lifts and guided paths to reduce land use and operational cost. Integration of vehicle-to-infrastructure communication ensures controlled movement through connected lanes. The shift toward autonomous valet solutions improves parking efficiency and reduces human error. Governments promote smart mobility programs to support intelligent transport networks. Cloud-based platforms help operators monitor vehicle flow and manage space in real time. This trend accelerates system deployment across developed and emerging regions.
- For instance, Los Angeles International Airport (LAX) expanded its smart parking services by integrating valet and online reservations with real-time space availability and contactless payment, improving user convenience and reducing congestion.
Rising Consumer Demand for Convenience and Safety Features
Consumers prefer features that reduce vehicle damage risks and simplify daily transport. Autonomous parking reduces minor accidents caused by tight urban spaces, poor visibility, and parallel parking challenges. Car buyers view automated parking as a high-value feature that improves comfort and increases brand appeal. Luxury and mid-range vehicle manufacturers add autonomous parking to differentiate products and improve customer experience. Fleet owners also adopt automated solutions to prevent parking-related damage. The emphasis on safety regulations and driver assistance guidelines helps accelerate market expansion. As awareness improves, more vehicle categories integrate fully automated parking technology.
Key Trends & Opportunities
Growth of Software-Driven Parking Intelligence
Software becomes a major value driver as vehicles rely on real-time mapping, AI-based decision making, and cloud connectivity. Automakers deploy algorithms that detect pedestrians, measure space, and execute parking maneuvers with little human input. Over-the-air updates improve system performance without hardware replacement. Companies integrate 3D mapping and machine learning to handle complex indoor environments. This trend shifts market focus from hardware-only solutions to intelligent software platforms. The shift also accelerates subscription-based service models, unlocking recurring revenue opportunities for automakers and parking system providers.
- For instance, BMW uses OTA technology to provide quarterly map updates to its Connected Drive system, enabling real-time navigation adjustments without dealership visits.
Surge in Autonomous Valet Parking Systems
Autonomous valet parking emerges as a high-impact trend in smart cities, airports, malls, and residential towers. Vehicles can drop passengers at the entrance and park themselves without a driver. Commercial parking operators deploy robotic platforms, conveyors, and automated lifts to maximize space. Integration with mobile apps lets drivers request vehicles remotely. Real estate developers adopt automated systems to reduce land requirements and provide premium services. These systems also support electric vehicle charging and fleet parking in restricted spaces. As costs decline and infrastructure improves, autonomous valet solutions gain wider adoption across urban mobility networks.
- For instance, companies such as Valeo and Continental have independently developed and introduced their own modular autonomous valet parking platforms that support various vehicle types and configurations, reducing integration costs and potentially accelerating deployment through separate partnerships.
Key Challenges
High System Cost and Limited Affordability in Mass-Market Vehicles
Autonomous parking systems require cameras, radar units, ultrasonic sensors, computing modules, and high-performance software. These components increase manufacturing cost, making deployment difficult in low and mid-range vehicles. OEMs face price pressure in cost-sensitive markets where buyers prioritize affordability. Infrastructure requirements in public parking lots also restrict adoption. Operators must invest in connectivity, sensors, and intelligent platforms to support automated movement. Small developers may not justify these costs, slowing market penetration. As a result, adoption remains concentrated in premium vehicle categories and metropolitan regions.
Regulatory and Safety Compliance Barriers
Regulations for autonomous driving vary across countries, delaying standardization for automated parking. Automakers must prove reliability of obstacle detection, pedestrian safety, and emergency control. Tests require complex validation across different parking layouts and climate conditions. Liability concerns arise in case of collision or system failure. Lack of unified safety standards slows commercial rollout of Level 4 and Level 5 parking systems. Public parking operators also require compliance with cybersecurity and data privacy rules, adding operational complexity. These regulatory challenges limit fast commercialization in global markets.
Regional Analysis
North America
North America led the Autonomous Parking market with 36% share in 2024. The region benefits from strong adoption of ADAS features, premium vehicles, and smart parking infrastructure. Automakers in the United States invest in AI-based parking algorithms and real-time navigation to reduce collision risks in dense urban spaces. Commercial complexes and airports deploy connected parking platforms to improve space management and reduce vehicle damage. High demand for luxury vehicles and electric cars also supports system integration. Strong presence of technology companies and early regulatory support strengthens market leadership.
Europe
Europe held 31% share in 2024, driven by rapid smart mobility adoption and strict safety standards. Germany, the U.K., and France invest in autonomous driving programs, encouraging OEMs to deploy advanced parking technologies. Urban congestion and limited parking areas push consumers toward automated valet systems and robotic platforms. Automakers integrate autonomous parking as a standard feature in premium brands. European smart city projects and EV expansion provide a strong base for system deployment. Leading automotive manufacturers also test Level 4 parking capabilities in controlled environments, supporting wider rollouts.
Asia-Pacific
Asia-Pacific accounted for 24% share in 2024 and represents the fastest-growing region. China, Japan, and South Korea lead production of sensor-rich vehicles and smart parking solutions. Growing urban populations and rising vehicle ownership increase demand for automated parking in high-density areas. Property developers adopt robotic parking systems to manage space in residential towers and commercial zones. Government programs for intelligent transport systems encourage technology adoption. Automakers collaborate with tech providers for AI-based mapping and automated valet features, expanding system deployment across mid-range vehicle categories.
Middle East & Africa
Middle East & Africa captured 5% share in 2024, supported by premium vehicle adoption and smart infrastructure investment in Gulf countries. Airports, malls, and luxury residential complexes deploy automated parking systems to provide high-end mobility services. Government focus on smart cities in the UAE and Saudi Arabia accelerates pilot projects for autonomous valet platforms. However, limited integration in mass-market vehicles and smaller automotive ecosystems restrict widespread use. Vendors target commercial hubs and tourism zones where automated parking offers strong operational efficiency.
Latin America
Latin America held 4% share in 2024. Brazil and Chile lead adoption in urban mobility programs, where congestion and shortage of parking areas drive interest in automation. Premium vehicle imports support initial deployment, while commercial complexes explore robotic parking options to optimize space. High system cost and limited infrastructure slow mass-market expansion. However, rising consumer interest in driver-assist features and growing EV presence create long-term opportunities. Regional adoption is expected to improve with declining sensor costs and increased support from smart transportation initiatives.
Market Segmentations
By Component
- Hardware
- Software
- Services
By Automation Level
- SAE Level 2
- SAE Level 3
- SAE Level 4
- SAE Level 5
By Vehicle
- Passenger Vehicles
- Commercial Vehicles
By End User
- Automotive OEMs
- Parking Operators
- Commercial & Retail Spaces
- Smart Cities & Municipalities
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Autonomous Parking market features a mix of automotive OEMs, technology developers, and robotic parking solution providers. Leading players focus on sensor integration, high-resolution cameras, and AI-driven perception systems to improve vehicle control in confined areas. Companies such as Tesla, Daimler AG, Bosch, and FCA USA LLC deploy autonomous parking as a premium feature in passenger vehicles to enhance convenience and safety. Parking automation specialists like Skyline Parking AG, Robotic Parking Systems Inc., and Klaus Multiparking GmbH develop robotic lifts and automated valet platforms for commercial complexes and residential towers. Unitronics (1989) (R G) Ltd. and City Lift Parking LLC offer smart garage solutions for space optimization and remote vehicle retrieval. Partnerships between automakers, AI developers, and infrastructure providers accelerate deployment of Level 4 parking systems. Vendors invest in real-time mapping, cloud connectivity, and machine learning to improve precision and reduce human intervention. As competition intensifies, companies differentiate through software performance, safety validation, and seamless integration with electric and connected vehicles.
Key Player Analysis
- City Lift Parking LLC
- Tesla
- Unitronics (1989) (R G) Ltd.
- Robert Bosch GmbH
- Daimler AG
- Robotic Parking Systems Inc.
- Westfalia Parking
- Skyline Parking AG
- Klaus Multiparking GmbH
- FCA USA LLC
Recent Developments
- In March 2025, Volkswagen Group, Valeo SA, and Mobileye Global Inc. announced a partnership to develop sensors, control units, and parking solutions, including “parking assist” features and higher autonomy for vehicles.
- In February 2023, BMW and Valeo signed a strategic cooperation agreement to co-develop next-generation Level 4 automated parking and valet systems, which will offer fully automated parking solutions.
- In November 2022, Bosch and Mercedes-Benz Group AG received regulatory approval in Germany for their Level 4 driverless parking system, which was implemented at Stuttgart Airport, providing a commercial solution for autonomous parking in a designated garage
Report Coverage
The research report offers an in-depth analysis based on Component, Automation Level, Vehicle, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Autonomous parking will become a standard feature in premium and mid-range vehicles.
- AI-based mapping and object detection will improve accuracy in congested areas.
- Automakers will increase investment in Level 4 systems for self-parking without driver input.
- Cloud connectivity will enable remote parking management and vehicle retrieval through mobile apps.
- Robotic parking facilities will expand in airports, malls, and residential towers.
- Over-the-air software updates will enhance system performance without hardware changes.
- Integration with electric vehicles will support automated parking and charging alignment.
- Subscription-based parking services will create new revenue opportunities for OEMs.
- Partnerships between automakers and infrastructure providers will accelerate smart parking deployment.
- Declining sensor costs will support wider adoption in mass-market vehicles.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Autonomous Parking market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Autonomous Parking market projected to grow between 2025 and 2032?
Which Autonomous Parking market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Autonomous Parking market?
Who are the leading companies in the Autonomous Parking market?
Which region commanded the largest share of the Autonomous Parking market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3.78 Billion → 2032: USD 10.55 Billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Autonomous Parking Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Autonomous Parking Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Autonomous Parking Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Autonomous Parking Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Autonomous Parking Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Autonomous Parking Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Autonomous Parking Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Autonomous Parking Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3.78 Billion → 2032: USD 10.55 Billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Autonomous Parking Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Autonomous Parking Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Autonomous Parking Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Autonomous Parking Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

