
Market Overview:
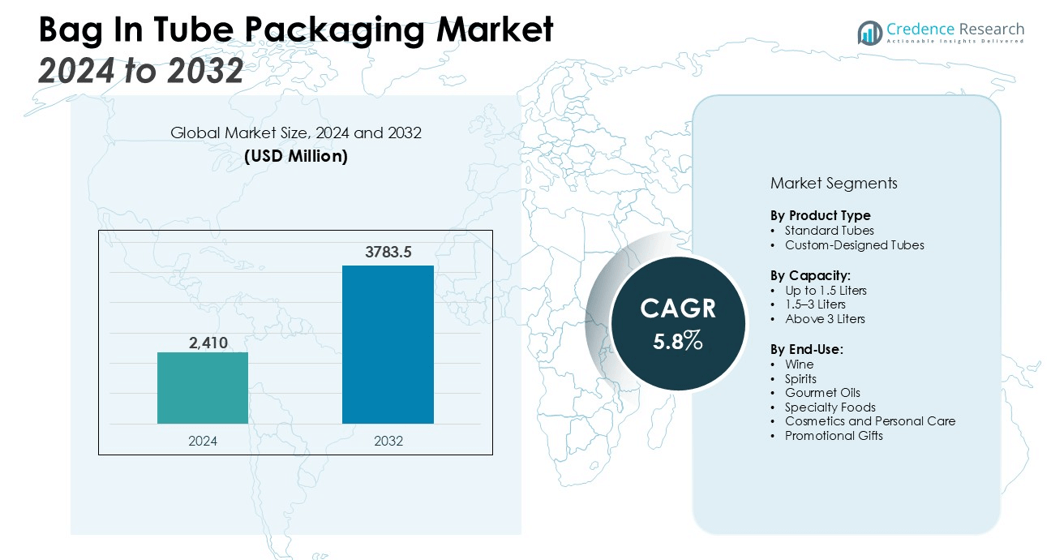
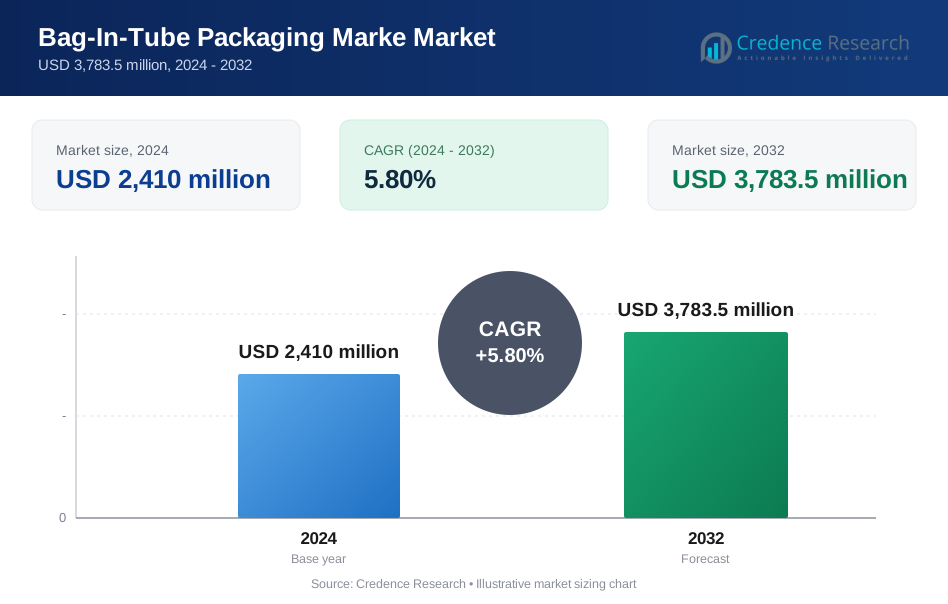
The Bag in tube packaging market size was valued at USD 2,410 million in 2024 and is anticipated to reach USD 3783.5 million by 2032, at a CAGR of 5.8 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Bag In Tube Packaging Market Size 2024 | USD 2,410 million |
| Bag In Tube Packaging Market, CAGR | 5.8% |
| Bag In Tube Packaging Market Size 2032 | USD 3783.5 million |
The primary drivers of the bag in tube packaging market include strong demand for innovative, convenient, and sustainable solutions from producers of wine, spirits, oils, and luxury foods. This packaging ensures superior product preservation, extends shelf life, and reduces the need for preservatives. It meets consumer preferences for lightweight, easy-to-use, and recyclable formats. Advances in materials and design, such as better barrier films and customizable tubes, have expanded use into cosmetics, gourmet foods, and gifting. The format supports sustainability goals by using less material and reducing transportation costs.
Regionally, Europe leads the bag in tube packaging market due to established wine and spirits industries, strong design innovation, and supportive regulations for sustainable packaging. Leading companies such as Smurfit Kappa Group PLC, Parish Manufacturing Inc, Tecnicam S.r.l, and Industri-Bag drive regional growth. France, Italy, and Spain are key markets for premium and export-oriented products. North America follows, fueled by rising demand for specialty packaging among craft beverage and luxury brands. Asia Pacific shows rapid growth, with increased demand in China, Japan, and Australia for high-quality packaging.
Market Insights:
- The bag in tube packaging market reached USD 2,410 million in 2024 and is set to reach USD 3,783.5 million by 2032.
- Premium wine, spirits, oils, and gourmet foods drive strong demand for innovative and sustainable packaging formats.
- The format ensures superior product preservation, extends shelf life, and reduces the need for preservatives.
- Recyclable, lightweight, and customizable tube packaging meets growing consumer and regulatory preferences for sustainability.
- Europe holds 55% market share, led by France, Italy, and Spain, with advanced design and sustainability standards.
- North America and Asia Pacific show fast growth, driven by specialty packaging demand and rising disposable incomes.
- Leading companies include Smurfit Kappa Group PLC, Parish Manufacturing Inc, Tecnicam S.r.l, and Industri-Bag.
Market Drivers:
Rising Demand for Premium and Differentiated Packaging Solutions:
Brand owners in the wine, spirits, and gourmet food sectors prioritize packaging formats that enhance visual appeal and customer experience. The bag in tube packaging market benefits from its ability to deliver a distinctive, elegant presentation that stands out on retail shelves. It supports high-quality graphics, custom finishes, and unique shapes, enabling brands to communicate exclusivity and quality. This premium appearance strengthens brand positioning in competitive markets. Consumers associate tube-based packaging with value, innovation, and convenience, driving adoption for luxury products. Companies leverage this format to reinforce brand loyalty and boost shelf impact.
- For instance, Smurfit Kappa’s Bag-in-Tube® solution is available in exact sizes ranging from 1.5 liters to 5 liters, using a double-layered bag and Vitop® tap designed to keep contents fresh by minimizing oxygen permeation—prolonging product shelf life after opening, as directly confirmed in official product specifications.
Growing Preference for Product Preservation and Extended Shelf Life:
Preservation of product quality remains a critical requirement in the premium beverage and specialty liquid segments. Bag in tube packaging protects contents from light, oxygen, and contaminants, ensuring freshness and minimizing spoilage. Its barrier properties reduce the need for artificial preservatives, aligning with consumer preferences for natural formulations. The packaging design prevents product wastage by enabling efficient dispensing and minimizing air exposure. Manufacturers choose this solution to extend the usability and appeal of premium liquids, resulting in higher customer satisfaction. The bag in tube packaging market sees increased uptake where product integrity is paramount.
Increasing Focus on Sustainable and Lightweight Packaging Alternatives:
Sustainability is a core driver of innovation in the packaging industry. The bag in tube packaging market addresses environmental concerns by utilizing recyclable materials and reducing overall packaging weight. This format requires fewer raw materials than traditional rigid containers and lowers carbon emissions during transportation. Companies view it as an opportunity to meet regulatory requirements and consumer expectations for eco-friendly products. It helps reduce waste across the value chain while maintaining product protection and aesthetic value. Sustainability credentials play a central role in purchasing decisions within target markets.
- For instance, a 3-liter Smurfit Kappa Bag-in-Box bag, when equipped with the Vitop Compact tap, results in a total packaging weight of only 64 grams, compared to more than 1,700 grams for an equivalent quantity of beverage packaged in standard glass bottles.
Advancements in Customization, Technology, and Material Science:
Rapid developments in packaging technology and materials have expanded the application range of bag in tube packaging. It now supports a wider array of product categories, including cosmetics, oils, and promotional gifts. Advanced manufacturing techniques enable intricate designs, improved barrier films, and greater flexibility in sizing and structure. Brands tailor the appearance and functionality to meet specific product requirements and market trends. This adaptability makes the packaging format a preferred choice for brands seeking differentiation. The bag in tube packaging market continues to evolve with new features that enhance both visual impact and performance.
Market Trends:
Increasing Emphasis on Premiumization and Visual Storytelling:
Brands now invest in packaging that delivers a luxury experience and communicates a compelling brand story. The bag in tube packaging market responds to this trend by offering options for high-definition printing, metallic foiling, and textured finishes. It allows for distinctive shapes and detailed customization that enhance product appeal and shelf visibility. Companies in the wine, spirits, and specialty food sectors use tube-based packaging to elevate unboxing experiences and support limited-edition launches. This focus on visual storytelling helps brands connect emotionally with consumers and drive repeat purchases. Enhanced aesthetics and tactile features now play a central role in packaging decisions.
- For instance, TUBES, a Dutch manufacturer, bottles and distributes wines and spirits in single-serve glass or recycled PET tubes, each with a capacity of 100ml; their tubes are commercially shelf-stable for up to 24 months when made of glass.
Expansion into New Product Categories and Functional Innovation:
Market participants increasingly explore applications beyond traditional beverages, targeting cosmetics, oils, and gourmet food products. The bag in tube packaging market supports this expansion through advancements in barrier materials, tamper-evident closures, and easy-pour designs. It appeals to brands seeking practical solutions that combine visual impact with product safety and convenience. E-commerce and gifting channels also boost demand for protective, premium, and lightweight packaging. Innovations in tube structure and fitments cater to evolving functional needs and create new opportunities across diverse market segments. Functional enhancements continue to drive adoption among forward-thinking brands seeking to differentiate.
- For instance, Amcor Flexibles launched the Shield Pack Clear High Barrier Aseptic IBC Bag, which uses a triple-barrier material of 10.8 mil thickness and achieves an Oxygen Transmission Rate of less than 0.04cc O2/100in²/24hr at 73°F, enabling the safe expansion into sensitive food and gourmet categories.
Market Challenges Analysis:
High Production Costs and Complex Manufacturing Requirements:
The bag in tube packaging market faces challenges related to elevated production costs and intricate manufacturing processes. It demands specialized machinery and skilled labor, which increase initial investment and operational expenses. Complex designs and customization requirements often extend lead times and limit scalability for small to mid-sized brands. Cost-sensitive producers may hesitate to adopt this packaging format when lower-cost alternatives exist. Maintaining consistent quality standards across diverse suppliers adds further complexity. These factors restrict broader adoption in price-driven market segments.
Limited Consumer Awareness and Adoption in Emerging Markets:
Limited consumer familiarity with tube-based packaging formats presents a hurdle for market growth, especially in emerging regions. The bag in tube packaging market relies on strong branding and effective marketing to educate buyers about its benefits. Retailers and distributors may resist new formats that require changes in shelf placement or logistics. It also competes with established rigid and flexible packaging solutions that dominate traditional retail channels. Regulatory uncertainties regarding recyclability and material compliance in some countries create additional barriers. These challenges slow the market’s penetration into new geographic areas.
Market Opportunities:
Expansion into Niche and Premium Product Segments:
The bag in tube packaging market holds significant potential in niche and premium product categories. Brands focused on limited-edition wines, craft spirits, artisanal oils, and luxury food items can leverage this format to differentiate and elevate brand perception. It offers a canvas for creative design and value-added features that attract discerning consumers. Growth in gifting, travel retail, and e-commerce channels further increases the appeal of visually striking and convenient packaging solutions. Companies can capitalize on rising demand for unique experiences by introducing tube-based packaging for seasonal and promotional launches. This approach supports premiumization and brand storytelling initiatives.
Sustainability Initiatives and Advances in Eco-Friendly Materials:
Sustainability creates compelling opportunities for the bag in tube packaging market, particularly as regulations and consumer expectations evolve. It aligns with trends toward recyclable, lightweight, and resource-efficient packaging solutions. Advances in bio-based films and renewable materials will further enhance the market’s environmental profile. Brands adopting green packaging solutions strengthen their value proposition and address growing demand for responsible sourcing. Collaborative efforts between suppliers and manufacturers can accelerate development of innovative, sustainable tube formats. These opportunities position the market to attract environmentally conscious brands and consumers.
Market Segmentation Analysis:
By Product Type:
The bag in tube packaging market features two primary product types: standard and custom-designed tubes. Standard tubes dominate volume sales due to their cost-effectiveness and suitability for mass-market applications. Custom-designed tubes appeal to premium brands seeking unique aesthetics, advanced finishes, and enhanced branding opportunities. Manufacturers provide a variety of closures, dispensing mechanisms, and surface treatments, allowing brands to align packaging with product positioning. Custom tubes find high adoption in luxury beverages, specialty foods, and gifting segments.
- For instance, Amcor Flexibles supplies over 15 closure types—including flip-top and threaded caps—that are tailored for beauty, wine, spirits, and pharmaceutical packaging to meet specific brand and product needs.
By Capacity:
Capacity segmentation covers small (up to 1.5 liters), medium (1.5–3 liters), and large (above 3 liters) formats. Small-capacity tubes are preferred for high-value products, limited editions, and trial sizes, offering convenience and portability. Medium-sized tubes serve core beverage categories and gourmet oils, balancing storage efficiency with user-friendly handling. Large-capacity tubes meet the needs of institutional and hospitality clients who require bulk dispensing and extended shelf life.
- For instance, The Packaging Company supplies 50ml cosmetic squeeze tubes engineered with multi-layered laminate structures that safely store travel-size creams, gels, and serums for high-frequency consumer use.
By End-Use:
End-use segmentation spans wine, spirits, gourmet oils, specialty foods, cosmetics, and promotional gifts. The bag in tube packaging market finds its largest demand in the wine and spirits sector, where shelf differentiation and product protection drive uptake. Gourmet oils and specialty foods leverage tube packaging for premium positioning and extended freshness. Cosmetic and personal care brands adopt tube formats to support branding and gifting initiatives, while promotional gift markets benefit from the format’s customizability and visual appeal.
Segmentations:
By Product Type:
- Standard Tubes
- Custom-Designed Tubes
By Capacity:
- Up to 1.5 Liters
- 5–3 Liters
- Above 3 Liters
By End-Use:
- Wine
- Spirits
- Gourmet Oils
- Specialty Foods
- Cosmetics and Personal Care
- Promotional Gifts
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Europe:
Europe holds 55% of the global bag in tube packaging market, driven by strong design innovation and advanced sustainability practices. It benefits from a well-established wine and spirits industry, where leading brands consistently adopt tube-based formats for premium and export products. Regulatory frameworks in France, Italy, and Spain encourage the use of recyclable and eco-friendly packaging materials. Design agencies and converters in the region set global trends in aesthetics and functionality. Regional consumers value unique packaging and support responsible sourcing, reinforcing demand for tube-based solutions. Continuous investment in technology and production capacity supports the region’s dominance.
North America:
North America accounts for 22% of the bag in tube packaging market, supported by increasing demand for differentiated and value-added packaging. Producers of craft beverages, gourmet foods, and cosmetics embrace tube-based formats to create shelf distinction and enhance customer experience. U.S. and Canadian brands leverage the packaging’s premium look to strengthen brand loyalty in competitive markets. E-commerce growth and changing consumer lifestyles accelerate adoption of convenient, lightweight solutions. Regulatory guidance in both countries aligns with industry sustainability targets, facilitating market expansion. Strategic collaborations between brands and packaging suppliers foster innovation in this region.
Asia Pacific:
Asia Pacific represents 17% of the bag in tube packaging market, with rapid growth fueled by rising disposable incomes and evolving consumer preferences. Key markets such as China, Japan, and Australia drive adoption, supported by demand for premium packaging in beverages and personal care. Local manufacturers invest in advanced machinery and materials to match global quality standards. Awareness of sustainable packaging increases among regional brands, influencing purchasing decisions. Product launches for festivals and gift-giving occasions further boost interest in visually appealing tube formats. The region’s dynamic retail sector and strong export activity contribute to ongoing market expansion.
Key Player Analysis:
- Smurfit Kappa Group PLC;
- Parish Manufacturing Inc;
- Tecnicam S.r.l;
- Industri-Bag;
- Grafica Rovellosa SL;
- Sunpack Industries;
- Uline; Master Packaging Inc;
- SKS Packaging Pvt. Ltd;
- DS Smith
Competitive Analysis:
The bag in tube packaging market features a competitive landscape with a mix of global leaders and specialized regional players. Key companies such as Smurfit Kappa Group PLC, Parish Manufacturing Inc, Tecnicam S.r.l, and Industri-Bag hold prominent positions through strong technological capabilities, diverse portfolios, and established client relationships. It values innovation in materials, design, and sustainability, driving continuous investment in research and development. Leading firms collaborate closely with luxury brands to deliver customized, premium solutions. Smaller players compete by offering flexible production, rapid turnaround times, and niche product expertise. Strategic partnerships, product launches, and expansions into new regions strengthen competitive positions and support market growth.
Recent Developments:
- In November 2024, Smurfit Westrock launched the EasySplit Bag-in-Box design, a new packaging innovation developed to help customers meet forthcoming EU recyclability regulations.
- In April 2025, Sun Chemical (a major ink supplier to packaging) launched SunPak PowerPace, an advanced vegetable-oil-based sheetfed offset printing ink for sustainability, though the brand is not identical to Sunpack Industries but is a leading partner in print packaging.
- In April 2025, DS Smith, now under International Paper, launched the GoChill Cooler, a 100% recyclable, wax-free corrugated board cooler designed as a sustainable alternative to traditional coolers. The GoChill is part of DS Smith’s circular economy strategy and responds to strong consumer demand for eco-friendly options.
Market Concentration & Characteristics:
The bag in tube packaging market features a moderate to high level of concentration, with a select group of specialized manufacturers and converters dominating global supply. It relies on advanced production technology, design expertise, and access to premium materials, which create high entry barriers for new participants. Leading players set benchmarks for quality, innovation, and sustainability, while smaller firms compete through niche applications and custom designs. The market prioritizes reliability, short lead times, and collaboration between brands and packaging specialists. Continuous investment in R&D and exclusive partnerships with luxury brands further strengthen the position of established suppliers.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Capacity, End-Use and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- Manufacturers continue to explore new barrier technologies to enhance product protection and longevity.
- Brands aim to integrate customizable finishes and digital printing to improve shelf appeal.
- Designers focus on ergonomic closures and easy-dispense features to enhance user experience.
- Suppliers collaborate to develop fully recyclable and bio-based tube materials.
- Companies implement lightweight tube formats to reduce logistical and carbon footprint.
- Brands prioritize limited-edition packaging for seasonal and promotional campaigns.
- Innovation hubs drive material science breakthroughs that support tube durability and flexibility.
- Labels and fitments evolve to ensure tamper evidence and meet regulatory standards.
- Retailers request packaging that supports e-commerce and direct-to-consumer shipping.
- The bag in tube packaging market embraces data-driven customization, enabling small-batch personalization.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Bag in tube packaging market?
What are the key segments within the Bag in tube packaging market?
What are some challenges faced by the Bag in tube packaging market?
Who are the major players in the Bag in tube packaging market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Bag-In-Tube Packaging Marke Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Bag-In-Tube Packaging Marke Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2,410 million → 2032: USD 3,783.5 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Bag-In-Tube Packaging Marke Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Bag-In-Tube Packaging Marke Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Bag-In-Tube Packaging Marke Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Bag-In-Tube Packaging Marke Market Drivers
- 3.3 Bag-In-Tube Packaging Marke Market Restraints & Challenges
- 3.4 Bag-In-Tube Packaging Marke Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Bag-In-Tube Packaging Marke Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Bag-In-Tube Packaging Marke Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Bag-In-Tube Packaging Marke category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Bag-In-Tube Packaging Marke Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Bag-In-Tube Packaging Marke Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Bag-In-Tube Packaging Marke market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Bag-In-Tube Packaging Marke Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Bag-In-Tube Packaging Marke Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Bag-In-Tube Packaging Marke Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Bag-In-Tube Packaging Marke (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Bag-In-Tube Packaging Marke Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Bag-In-Tube Packaging Marke Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Bag-In-Tube Packaging Marke Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Bag-In-Tube Packaging Marke Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Bag-In-Tube Packaging Marke Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Bag-In-Tube Packaging Marke Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Bag-In-Tube Packaging Marke Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Bag-In-Tube Packaging Marke Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Bag-In-Tube Packaging Marke Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
