
Market Overview:
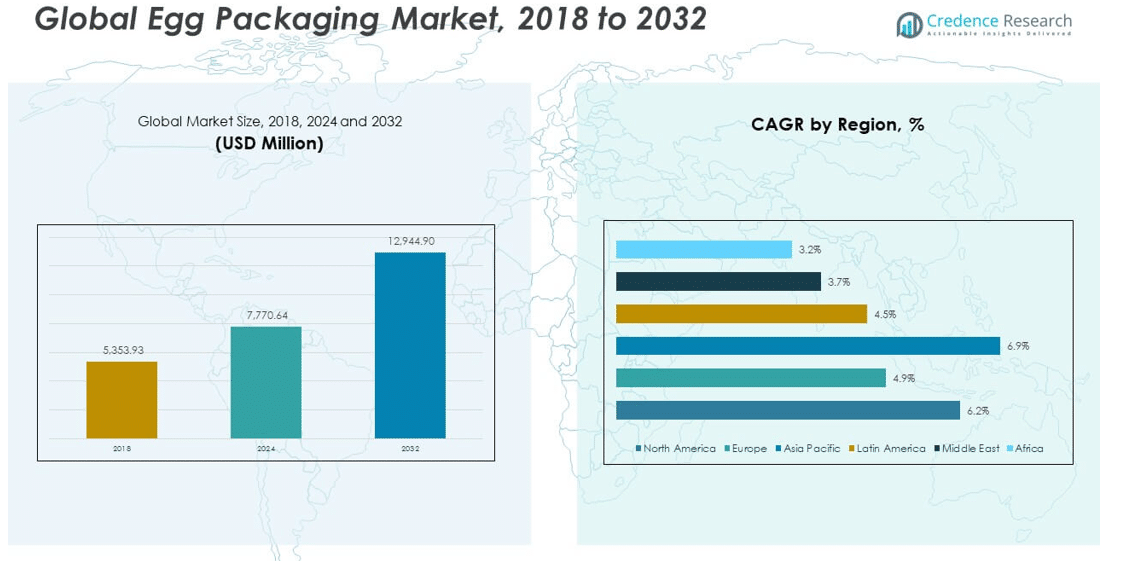
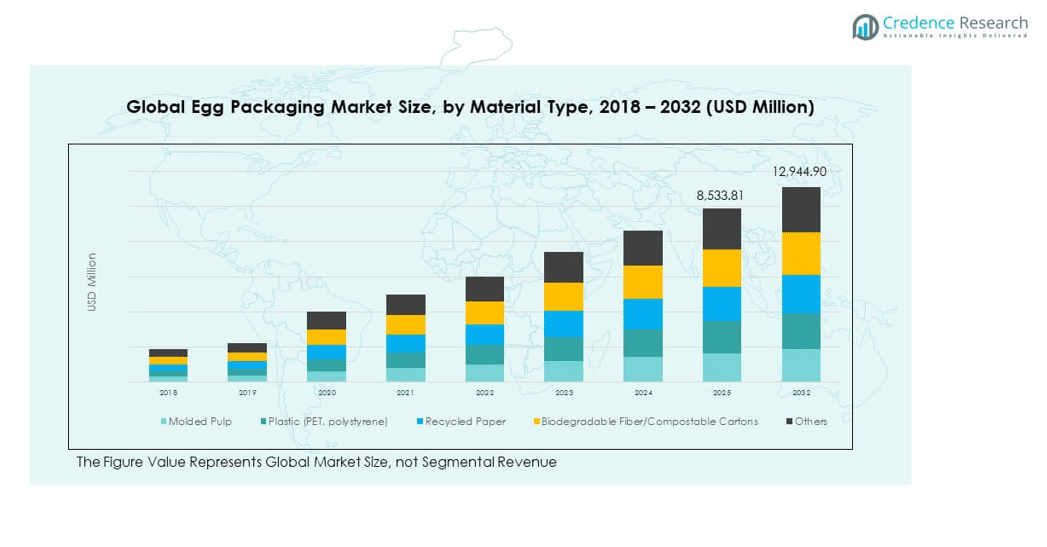
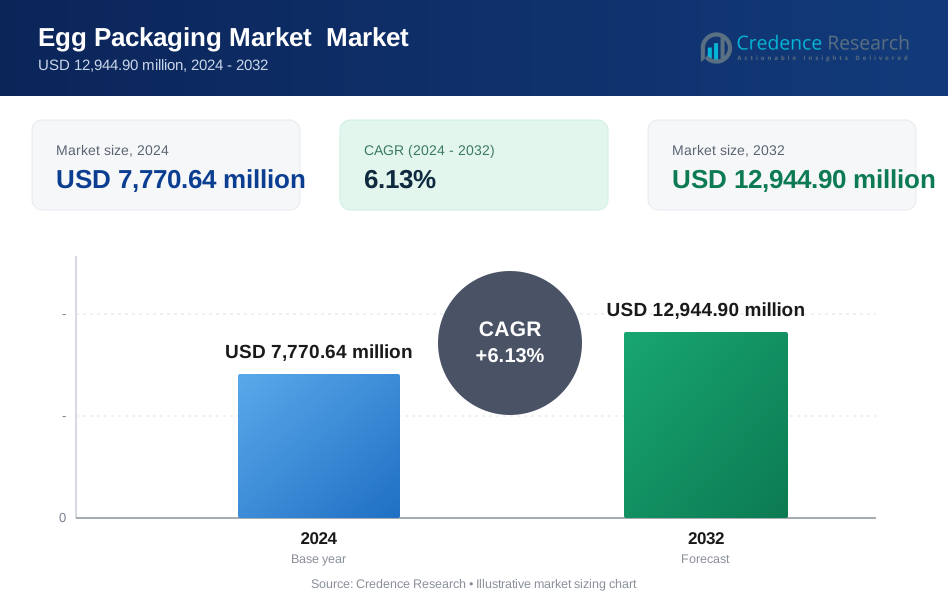
The Global Egg Packaging Market size was valued at USD 5,353.93 million in 2018 to USD 7,770.64 million in 2024 and is anticipated to reach USD 12,944.90 million by 2032, at a CAGR of 6.13% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Egg Packaging Market Size 2024 | USD 7,770.64 million |
| Egg Packaging Market, CAGR | 6.13% |
| Egg Packaging Market Size 2032 | USD 12,944.90 million |
Growth in the Global Egg Packaging Market is driven by rising egg consumption, expanding poultry farming, and strict food safety standards. Consumers demand packaging that ensures product safety, durability, and hygiene across supply chains. Sustainability has become a major driver, pushing producers to adopt molded pulp and biodegradable solutions over plastic. Innovations in material design and retail-friendly packaging formats further enhance value. Retail expansion and e-commerce penetration strengthen the need for protective, branded, and traceable egg packaging solutions.
Regionally, Asia Pacific leads the Global Egg Packaging Market, supported by high egg consumption, rapid urbanization, and modern retail development. North America and Europe maintain strong positions due to advanced packaging technologies and strict food safety regulations. Emerging markets in Latin America show growth through expanding poultry farming and improving retail infrastructure. The Middle East and Africa present opportunities with rising consumer awareness and modernization of supply chains, although adoption is gradual compared to developed regions.\
Market Insights:
- The Global Egg Packaging Market size was valued at USD 5,353.93 million in 2018, reached USD 7,770.64 million in 2024, and is projected to reach USD 12,944.90 million by 2032, growing at a CAGR of 6.13%.
- Asia Pacific held the largest regional share of 45.45% in 2024, followed by North America with 28.26% and Europe with 17.49%, driven by strong egg consumption, advanced retail structures, and strict food safety standards.
- Asia Pacific is the fastest-growing region with 45.45% share in 2024, fueled by rapid urbanization, retail expansion, and rising protein intake across China, India, and Southeast Asia.
- Molded pulp accounted for the largest segment share in 2024 at 41%, reflecting sustainability trends and regulatory support for eco-friendly materials.
- Plastic packaging, including PET and polystyrene, represented 26% in 2024, maintaining relevance due to durability and visibility, especially in retail and foodservice supply chains.
Market Drivers
Rising Global Egg Consumption Driving Consistent Demand for Packaging Solutions
The Global Egg Packaging Market benefits from increasing egg consumption across both developed and emerging nations. Consumers prefer eggs for their affordability and nutritional benefits, creating consistent demand. Higher egg production requires packaging solutions that ensure safety, hygiene, and durability during storage and transportation. Foodservice industries and retail chains further drive consumption, amplifying packaging needs. Governments emphasize food security, boosting regulated egg distribution channels that depend on reliable packaging. The market sees steady volume growth from protein-rich diet adoption. Large-scale poultry farming accelerates supply chain expansion, creating opportunities for manufacturers. Demand stability supports long-term growth and investment.
Growing Preference for Sustainable and Recyclable Packaging Materials Across Industries
Sustainability concerns push manufacturers to focus on recyclable and biodegradable materials in egg packaging. Rising awareness about environmental impact influences consumer purchase behavior toward eco-friendly options. Regulations on single-use plastics enforce transitions to molded pulp, paper-based, or plant-derived alternatives. The Global Egg Packaging Market reflects this shift with companies investing in greener production methods. Pulp packaging offers both strength and compostability, addressing waste reduction goals. Retailers promote eco-labeled packaging to meet evolving consumer expectations. The sustainability trend drives innovation pipelines and reshapes competitive strategies. It encourages global brands to differentiate products with certified sustainable solutions.
Expansion of Retail Chains and Supermarkets Strengthening Packaging Requirements Globally
Expanding retail and supermarket penetration worldwide strengthens packaging requirements for eggs. Organized retail formats demand standardized, durable packaging with high stacking strength. Branding opportunities through printed packaging designs increase retail shelf appeal. The Global Egg Packaging Market benefits from advanced labeling technologies that enhance traceability. Consumers demand clear nutritional information and freshness indicators, requiring innovative packaging. Retailers prefer tamper-evident features that reassure buyers of product safety. Growing e-commerce in food delivery highlights the importance of protective packaging formats. Distribution efficiency and customer trust grow through standardized egg packaging systems.
- For instance, TekniPlex Consumer Products announced a 200,000-square-foot specialty molded fiber facility in Ohio, planned to commence operations in early 2024, as part of its USD 350 million investment in high-performance molded fiber solutions for egg cartons and other applications.
Stringent Food Safety Regulations and Hygiene Standards Elevating Packaging Standards
Governments enforce strict regulations around food safety and contamination prevention. The Global Egg Packaging Market adapts through compliance with hygiene standards that reduce health risks. Packaging designs integrate barriers that protect against moisture, dust, and bacterial exposure. Producers invest in technologies that extend shelf life while reducing waste. Regulators encourage traceable packaging with batch codes to ensure accountability. Rising consumer awareness reinforces demand for packaging aligned with certified safety standards. It supports innovations in both material design and structural integrity. Compliance investments by manufacturers strengthen industry reliability and global trade opportunities.
- For instance, Hartmann Group renewed its ISO 14001 environmental management and ISO 50001 energy management certifications in 2023, underscoring its commitment to sustainability and operational efficiency.
Market Trends
Adoption of Smart Packaging Technologies Enhancing Consumer Engagement and Safety
The Global Egg Packaging Market integrates smart technologies that improve safety and consumer interaction. QR codes and NFC tags allow instant access to product details and traceability. Smart labeling supports transparency on sourcing and expiry dates. Producers explore embedded freshness indicators to enhance trust and reduce wastage. Retailers use digital tools for inventory monitoring, ensuring efficient supply. Smart packaging enables differentiation in competitive retail settings. It builds stronger consumer confidence in product quality. The trend strengthens loyalty and sets higher industry benchmarks.
- For instance, Vita Coco added a QR code to in-store displays for its “Vita Coco Pressed” line, launched via Blue Bite, which let consumers access a money-back guarantee and product content directly from their phones before purchasing
Shift Toward Premium Packaging Designs for Retail Differentiation and Brand Identity
Premium packaging emerges as a trend to attract urban and quality-conscious buyers. The Global Egg Packaging Market adopts designs with enhanced aesthetics and superior protective features. Printed graphics, branded logos, and appealing colors increase shelf presence. Premium packaging highlights freshness, animal welfare, and farm origin claims. Retailers use it to target health-conscious and high-income groups. Stronger designs with rigid materials also reduce damage during long supply chains. Premium packaging creates value perception beyond functional protection. It positions eggs as both affordable and quality-assured products.
- For instance, Cascades Inc. launched Fresh GUARD EnVision™ egg packaging in June 2024, delivering triple the rigidity and double the stacking strength versus standard 12-egg cartons, all validated through internal R&D and third-party recyclability certification.
Rising Popularity of Customized Packaging Formats Across Food Distribution Channels
Customized packaging formats grow in demand as producers target diverse retail and foodservice channels. The Global Egg Packaging Market offers multiple pack sizes ranging from six to thirty eggs. Smaller urban households prefer compact packs, while wholesale buyers opt for bulk trays. Retailers push customized branding to strengthen market positioning. Foodservice businesses demand specialized designs for efficient storage and delivery. Producers explore tailored printing options that highlight sustainability certifications. It allows companies to align packaging with evolving customer requirements. Customization drives flexibility and competitive advantage.
Increasing Integration of Automation and Robotics in Egg Packaging Processes
Automation dominates production as manufacturers seek efficiency and cost reduction. The Global Egg Packaging Market incorporates robotic handling, automated case packing, and palletizing. These technologies reduce breakage rates and improve consistency. Automated systems lower dependency on manual labor, minimizing human error. Higher output capacity strengthens supply chain responsiveness. Automation also aligns with hygiene standards by reducing contamination risks. It fosters scalability for large-scale egg producers. The integration sets a new standard for global packaging operations.
Market Challenges Analysis
Fluctuating Raw Material Costs and Volatility in Supply Chain Operations
The Global Egg Packaging Market faces challenges due to fluctuating raw material prices. Costs of plastics and pulp vary with oil price trends and supply disruptions. Volatility impacts profitability for packaging producers dependent on large-scale inputs. It pressures manufacturers to optimize procurement strategies and explore local sourcing. Currency fluctuations further affect global trade and margins. Supply chain disruptions from logistics delays add to operational risks. It creates uncertainty for companies managing high-volume production cycles. These fluctuations limit stability and influence investment decisions.
Environmental Regulations and Pressure to Transition From Plastic to Eco-Friendly Alternatives
Tighter regulations on plastic usage present major challenges for packaging producers. The Global Egg Packaging Market must adapt by shifting toward recyclable and biodegradable options. Transitioning requires capital investments in new technologies and facilities. High costs of eco-friendly raw materials strain small and mid-size manufacturers. Market fragmentation creates uneven adoption rates across regions. It risks widening the gap between advanced and emerging markets. Companies unable to comply risk losing market access. Pressure to innovate within environmental guidelines adds complexity to competitive strategies.
Market Opportunities
Growing Demand in Emerging Economies Offering New Avenues for Packaging Expansion
Rising consumption in emerging economies strengthens opportunities for growth. The Global Egg Packaging Market benefits from rising protein intake and urbanization in Asia-Pacific and Latin America. Expanding supermarket chains and modern retail formats create wider packaging requirements. Governments support poultry farming to meet nutrition goals. E-commerce platforms accelerate egg distribution through secure packaging. It enables access to larger consumer bases across new demographics. Companies expanding in these regions capture higher growth potential. Early entrants establish stronger market presence.
Innovation in Biodegradable Materials and Advanced Packaging Formats Creating Market Differentiation
Sustainability drives innovation in biodegradable pulp, paper, and plant-based materials. The Global Egg Packaging Market sees opportunities in lightweight, compostable packaging formats. Producers invest in R&D to create durable yet eco-friendly solutions. Advanced printing and labeling enhance branding opportunities. Recyclable packaging designs meet regulatory expectations and consumer demand. Companies offering certified sustainable packaging gain competitive advantage. It allows differentiation in markets shifting toward circular economies. Innovation opens premium product categories for forward-looking manufacturers.
Market Segmentation Analysis:
By material type, molded pulp dominates the Global Egg Packaging Market due to its cost-effectiveness, strength, and eco-friendly profile. It is widely used by producers seeking sustainable options that align with regulatory standards. Plastic, including PET and polystyrene, retains demand for its durability and transparency, particularly in regions with strong retail presence. Recycled paper and biodegradable fiber cartons gain traction as sustainability targets reshape procurement practices.
- For instance, in January 2025, Pactiv Evergreen received Forest Stewardship Council® (FSC) certification for its molded fiber egg cartons and filler flats made from 100% recycled materials across facilities in Georgia, California, Minnesota, and Mexico.
By product type, cartons lead the Global Egg Packaging Market, supported by their versatility, labeling potential, and ability to protect eggs in smaller retail packs. Trays maintain importance in wholesale and bulk distribution, offering high stacking efficiency. Cases and clamshells serve specialized needs for logistics and premium retail packaging, while other niche formats target diverse market requirements.
By end user, poultry farms remain the primary demand drivers, requiring bulk packaging for large-scale supply chains. Supermarkets and grocery stores influence design innovation through retail presentation standards. E-commerce and home delivery platforms expand steadily, demanding tamper-proof and protective packaging for direct-to-consumer distribution.
- For instance, in November 2023, Huhtamaki Americas introduced fiber-based egg cartons made exclusively from 100% recycled materials at its expanded plant in Indiana, USA. These cartons serve leading US retailers and are documented as an eco-friendly alternative to polystyrene foam.
Segmentation:
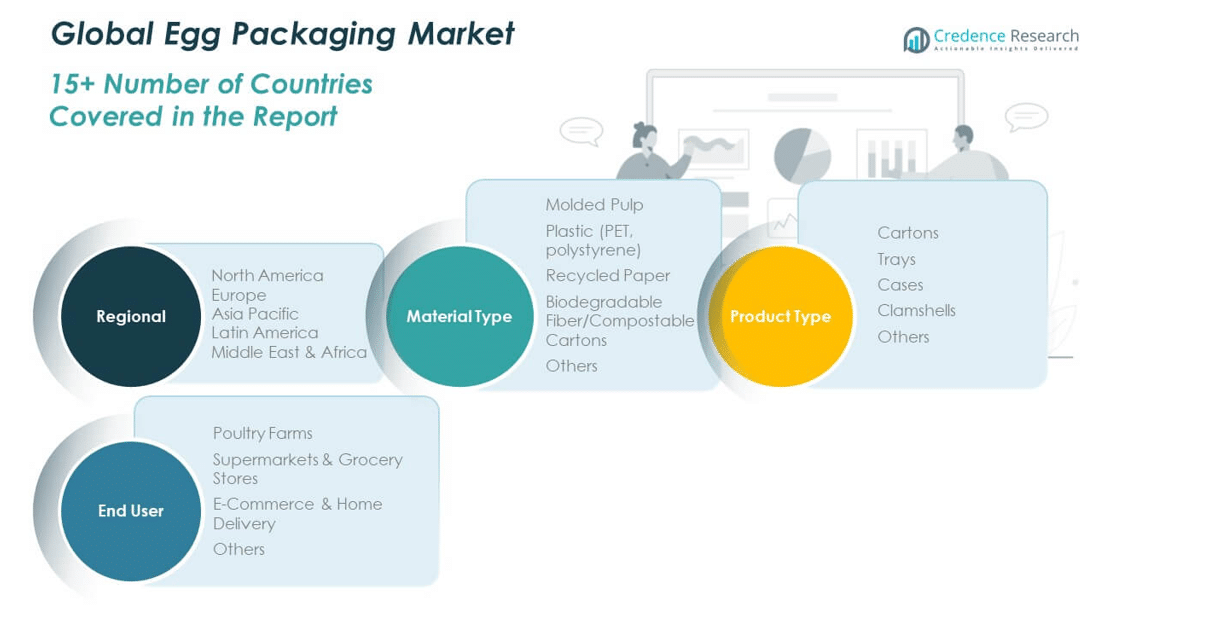
By Material Type
- Molded Pulp
- Plastic (PET, Polystyrene)
- Recycled Paper
- Biodegradable Fiber/Compostable Cartons
- Others
By Product Type
- Cartons
- Trays
- Cases
- Clamshells
- Others
By End User
- Poultry Farms
- Supermarkets & Grocery Stores
- E-Commerce & Home Delivery
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Global Egg Packaging Market size was valued at USD 1,537.83 million in 2018 to USD 2,196.76 million in 2024 and is anticipated to reach USD 3,675.05 million by 2032, at a CAGR of 6.2% during the forecast period. North America holds 28.26% of the global share in 2024, supported by strong demand for packaged eggs across supermarkets and retail outlets. The region benefits from advanced packaging technologies that prioritize sustainability and shelf-life extension. High consumer spending on premium packaging formats enhances growth. The Global Egg Packaging Market in North America also gains from strict food safety regulations requiring tamper-proof and traceable packaging. Expansion of quick-service restaurants and e-commerce channels strengthens demand for safe egg transport solutions. Poultry farming efficiency across the U.S. and Canada further drives packaging needs. The region demonstrates strong adoption of molded pulp and recyclable solutions.
Europe
The Europe Global Egg Packaging Market size was valued at USD 991.73 million in 2018 to USD 1,359.91 million in 2024 and is anticipated to reach USD 2,058.33 million by 2032, at a CAGR of 4.9% during the forecast period. Europe represents 17.49% of the global share in 2024, driven by regulatory frameworks supporting eco-friendly packaging. Countries such as Germany, France, and the UK adopt strict sustainability guidelines that reshape packaging practices. Consumer preferences favor recyclable pulp and biodegradable cartons, limiting plastic use. The Global Egg Packaging Market in Europe also reflects rising organic egg sales, boosting demand for natural packaging solutions. Retail chains prioritize clear labeling and traceability across packaging formats. E-commerce food delivery models accelerate adoption of protective packaging designs. Producers focus on premium branding and farm-origin labeling to meet rising demand.
Asia Pacific
The Asia Pacific Global Egg Packaging Market size was valued at USD 2,346.87 million in 2018 to USD 3,531.60 million in 2024 and is anticipated to reach USD 6,241.00 million by 2032, at a CAGR of 6.9% during the forecast period. Asia Pacific dominates with 45.45% of the global share in 2024, reflecting large-scale egg consumption across China, India, and Southeast Asia. Rising urbanization and growing middle-class populations drive demand for packaged eggs. The Global Egg Packaging Market in Asia Pacific expands through supermarkets, hypermarkets, and fast-growing e-commerce. Poultry farming modernization improves supply chain efficiency, requiring durable packaging formats. Governments promote food safety compliance, boosting demand for tamper-proof solutions. Manufacturers invest in automation and cost-effective molded pulp packaging. The region’s strong retail penetration supports significant market expansion.
Latin America
The Latin America Global Egg Packaging Market size was valued at USD 252.89 million in 2018 to USD 362.48 million in 2024 and is anticipated to reach USD 534.46 million by 2032, at a CAGR of 4.5% during the forecast period. Latin America accounts for 4.67% of the global share in 2024, driven by rising poultry farming and protein-rich diets. Brazil and Argentina are key contributors, with increasing adoption of packaged eggs in retail chains. The Global Egg Packaging Market in Latin America grows with modern retail expansion and growing consumer awareness of food safety. Demand for molded pulp packaging rises due to cost-effectiveness and sustainability benefits. E-commerce platforms strengthen urban distribution of eggs. Rural areas create opportunities for low-cost packaging adoption. Government policies support local egg production, enhancing packaging requirements.
Middle East
The Middle East Global Egg Packaging Market size was valued at USD 140.46 million in 2018 to USD 185.16 million in 2024 and is anticipated to reach USD 256.67 million by 2032, at a CAGR of 3.7% during the forecast period. The Middle East represents 2.38% of the global share in 2024, supported by growing poultry farming across GCC countries and Turkey. Rising demand for safe food packaging aligns with consumer preference for hygiene. The Global Egg Packaging Market in the Middle East advances with urban retail infrastructure and rising foodservice sector activity. Imports of packaged eggs also drive regional packaging adoption. Demand for recyclable and eco-friendly materials grows under government sustainability targets. Producers seek cost-effective packaging to manage competitive pricing in the region. Emerging online grocery channels increase reliance on protective packaging formats.
Africa
The Africa Global Egg Packaging Market size was valued at USD 84.15 million in 2018 to USD 134.73 million in 2024 and is anticipated to reach USD 179.40 million by 2032, at a CAGR of 3.2% during the forecast period. Africa contributes 1.74% of the global share in 2024, with South Africa and Egypt leading adoption. Urbanization and rising disposable incomes increase packaged egg consumption. The Global Egg Packaging Market in Africa faces infrastructure challenges but shows potential in urban centers. Demand for low-cost molded pulp packaging is strong among local producers. Governments encourage food safety practices, boosting packaged distribution. Informal markets still limit full adoption of standardized packaging. Investment in supply chain networks creates opportunities for broader reach. Growth potential remains high with modernization of retail and poultry industries.
Key Player Analysis:
- Huhtamaki Oyj
- CDL (CDL Omni-Pac)
- Europack
- Hartmann
- Tekni-Plex
- Ovotherm International Handels GmbH
- Dispak
- DFM Packaging Solutions
- Pactiv LLC
- Eco-Products
Competitive Analysis:
The Global Egg Packaging Market is highly competitive, with established companies and regional players driving innovation and market penetration. Leading companies such as Huhtamaki Oyj, Hartmann, Tekni-Plex, Ovotherm International Handels GmbH, and Pactiv LLC invest in sustainable materials and advanced packaging technologies to strengthen their portfolios. It is shaped by continuous innovation in molded pulp, recyclable plastics, and biodegradable solutions that meet regulatory and consumer demands. Companies expand geographically through partnerships, mergers, and acquisitions to secure stronger distribution networks. Regional players focus on cost-effective solutions to serve local markets, creating a balance between premium and mass-market packaging. Competitive intensity increases as e-commerce and retail chains demand packaging with higher durability, branding potential, and traceability. The industry’s growth relies on manufacturers aligning with food safety standards and sustainability targets, while offering differentiated designs that enhance shelf appeal and meet diverse consumer preferences.
Recent Developments:
- In April 2025, Huhtamaki acquired Zellwin Farms Company, a privately-owned business located in Zellwood, Florida for USD 18 million enterprise value. This acquisition supports Huhtamaki's growth within the molded fiber industry, specifically for egg cartons and egg flats, as North American legislation continues to shift packaging choices toward more renewable and recyclable options.
- In January 2025, Pactiv Evergreen achieved Forest Stewardship Council (FSC) certification for its molded fiber egg cartons and filler flats made from 100% recycled material, covering its production sites in Macon, Georgia; City of Industry, California; Moorhead, Minnesota; and Chihuahua, Mexico.
- In August 2024, Hartmann North America, a subsidiary of Hartmann Packaging A/S, announced a major expansion of its egg packaging production facilities in Rolla, Missouri, and Brantford, Ontario. The expansion aims to install new production lines and increase both manufacturing and warehouse capacity, with phased completion from summer 2024 through the end of 2025.
Report Coverage:
The research report offers an in-depth analysis based on Material Type, Product Type and End User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Sustainable packaging solutions will dominate, with strong adoption of molded pulp and biodegradable formats.
- Automation and robotics in packaging processes will increase operational efficiency and reduce waste.
- Rising global egg consumption will maintain steady demand for innovative and protective packaging.
- Retail expansion across urban areas will drive higher use of branded and premium packaging designs.
- E-commerce growth will enhance the need for durable and tamper-proof egg packaging formats.
- Regulatory pressure on plastics will accelerate investment in recyclable and eco-certified packaging.
- Customizable packaging formats will expand, targeting varied household sizes and commercial needs.
- Technological integration with smart labels will improve product traceability and consumer engagement.
- Emerging economies will deliver strong growth due to urbanization and rising protein intake.
- Competitive intensity will rise as global players and regional firms invest in sustainable innovations.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Egg Packaging Market?
What is the projected growth rate of the Egg Packaging Market?
What factors are driving the growth of the Egg Packaging Market?
What are the key segments within the Egg Packaging Market?
What are some challenges faced by the Egg Packaging Market?
Who are the major players in the Egg Packaging Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Egg Packaging Market Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Egg Packaging Market Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 7,770.64 million → 2032: USD 12,944.90 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Egg Packaging Market Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Egg Packaging Market Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Egg Packaging Market Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Egg Packaging Market Market Drivers
- 3.3 Egg Packaging Market Market Restraints & Challenges
- 3.4 Egg Packaging Market Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Egg Packaging Market Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Egg Packaging Market Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Egg Packaging Market category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Egg Packaging Market Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Egg Packaging Market Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Egg Packaging Market market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Egg Packaging Market Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Egg Packaging Market Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Egg Packaging Market Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Egg Packaging Market (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Egg Packaging Market Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Egg Packaging Market Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Egg Packaging Market Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Egg Packaging Market Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Egg Packaging Market Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Egg Packaging Market Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Egg Packaging Market Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Egg Packaging Market Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Egg Packaging Market Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
