
Market Overview:
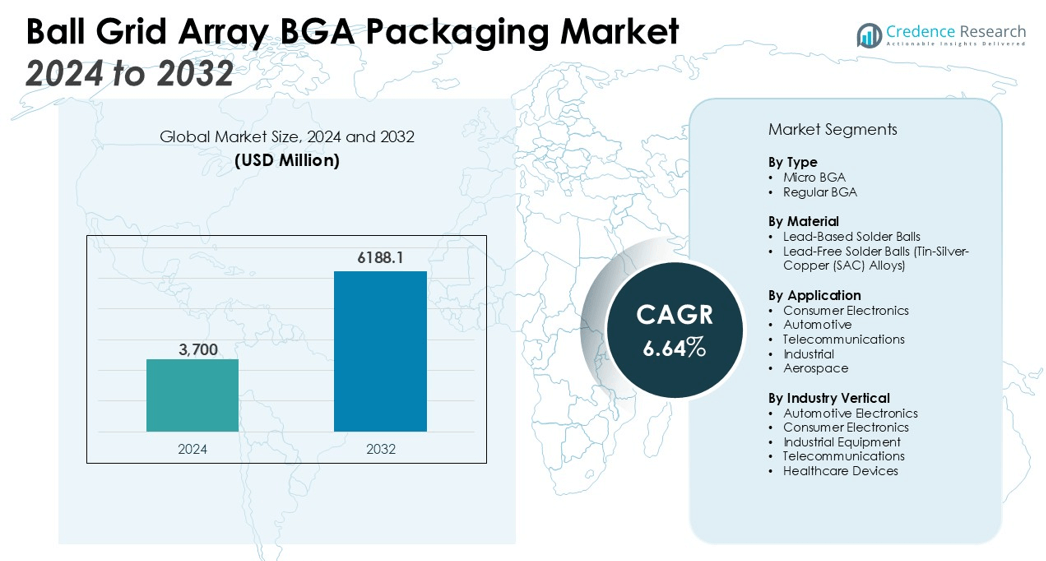
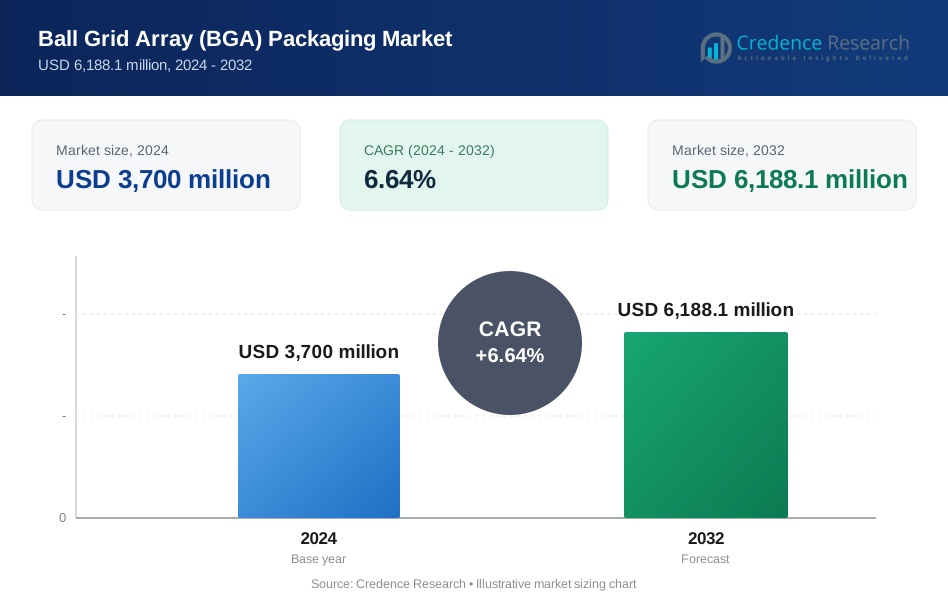
The Ball Grid Array BGA Packaging Market size was valued at USD 3,700 million in 2024 and is anticipated to reach USD 6188.1 million by 2032, at a CAGR of 6.64% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Ball Grid Array BGA Packaging Market Size 2024 | USD 3,700 million |
| Ball Grid Array BGA Packaging Market, CAGR | 6.64% |
| Ball Grid Array BGA Packaging Market Size 2032 | USD 6188.1 million |
The market is fueled by several factors, including the rising demand for compact and efficient semiconductor packaging solutions, the shift toward advanced electronics, and the growing adoption of consumer electronics like smartphones, laptops, and wearables. BGA packaging provides advantages such as enhanced heat dissipation, higher input/output (I/O) density, and reliability, making it ideal for applications requiring high performance and miniaturization. Additionally, the increasing trend of automation in manufacturing and the integration of 5G technology further supports market growth. The growing need for high-density interconnects in emerging technologies such as artificial intelligence (AI) and the Internet of Things (IoT) also significantly contributes to the demand for BGA packaging.
Regionally, North America holds a significant market share due to its robust electronics industry and technological advancements. The Asia Pacific region is expected to witness the highest growth rate, driven by the strong presence of semiconductor manufacturers in countries such as China, Japan, and South Korea. Europe is also experiencing steady demand, especially with the increasing focus on automotive and industrial applications.
Market Insights:
- The Ball Grid Array (BGA) Packaging Market is projected to grow from USD 3,700 million in 2024 to USD 6,188.1 million by 2032, at a CAGR of 6.64%.
- Rising demand for miniaturized electronic devices, such as smartphones, laptops, and wearables, is a key driver for BGA packaging, offering compact and efficient solutions with high performance.
- The market faces challenges due to the high cost of advanced BGA packaging solutions, which involve complex manufacturing processes, specialized materials, and high upfront investments.
- The increasing adoption of BGA packaging in automotive and industrial sectors is fueling market growth, driven by the need for durable, reliable packaging to withstand harsh conditions.
- The ongoing expansion of 5G technology and IoT devices is boosting demand for BGA packaging solutions that support high-speed data transmission and low signal loss for enhanced performance.
- North America holds a 35% market share, benefiting from its strong semiconductor industry and high adoption of advanced technologies like 5G and artificial intelligence.
- The Asia Pacific region leads the market with a 40% share, driven by a robust manufacturing base in countries like China, Japan, and South Korea, along with the growing demand from consumer electronics and IoT applications.
Market Drivers:
Rising Demand for Miniaturization in Electronic Devices
The Ball Grid Array (BGA) Packaging Market is being driven by the increasing demand for miniaturization in electronic devices. Consumer electronics, particularly smartphones, laptops, and wearables, require smaller and more efficient packaging solutions. BGA packaging provides a high-density interconnect, which allows for the miniaturization of components without compromising performance. This trend is crucial as electronic devices become more compact while retaining enhanced functionality and performance. The need for efficient heat dissipation and robust electrical performance in smaller packages continues to boost the market for BGA solutions.
- For instance, Motorola’s plastic BGA (PBGA) packages are produced with up to 357 I/O pins, and their 15mm x 15mm PBGA sample package houses exactly 196 solder balls in a 14x14 grid array, allowing for reduced footprint and improved electrical performance in surface-mount applications.
Advancements in Semiconductor Technology
Advancements in semiconductor technology also play a significant role in the growth of the BGA packaging market. As integrated circuits become more complex, the demand for packaging solutions that can support high-performance and high-density configurations increases. BGA packaging meets these requirements by offering superior thermal and mechanical performance, allowing for the integration of more powerful semiconductors. These improvements support the expansion of applications in industries like telecommunications, automotive, and computing, where cutting-edge technology and performance are paramount.
Growth in the Automotive and Industrial Sectors
The growing adoption of BGA packaging in the automotive and industrial sectors further fuels market demand. These industries require durable and reliable packaging to withstand harsh conditions, such as high temperatures and mechanical stress. BGA packaging's ability to deliver reliable performance under extreme conditions makes it ideal for automotive electronics, including sensors, infotainment systems, and electric vehicle components. The trend of increasing electronics content in vehicles is anticipated to drive further demand for BGA solutions in the automotive industry.
- For instance, NXP Semiconductors utilizes flip-chip BGA (FCBGA) packages with over 500 I/O pins in its engine management systems, providing reliable operation across a –40°C to +150°C temperature range and achieving a 99.97% performance reliability over 200,000km of vehicle lifespan.
Expansion of 5G Technology and IoT Devices
The ongoing expansion of 5G technology and the proliferation of IoT devices also contribute to the growth of the BGA packaging market. These technologies require advanced packaging solutions that can handle high-speed data transmission and support complex network architectures. BGA packaging's high I/O density and low signal loss characteristics make it well-suited for 5G infrastructure and IoT applications. As these technologies continue to grow, the demand for packaging solutions that can support their performance and scalability will keep increasing, driving the BGA packaging market forward.
Market Trends:
Shift Towards Advanced Packaging Solutions for High-Performance Devices
The Ball Grid Array (BGA) Packaging Market is witnessing a shift toward more advanced packaging solutions to meet the growing demands of high-performance electronic devices. With the increasing complexity of semiconductor devices, traditional packaging methods struggle to support the required miniaturization and performance levels. BGA packaging offers superior electrical and thermal performance, allowing it to meet the needs of high-performance processors and memory chips. This trend is particularly evident in sectors like telecommunications, automotive, and computing, where the focus is on enhancing device performance while reducing size. The ongoing demand for smaller, faster, and more efficient devices continues to drive the evolution of BGA packaging.
- For instance, Amkor Technology’s Double-Sided Molded Ball Grid Array (DSMBGA) enables assembly of active, passive, and antenna tuner components on both sides of a module substrate.
Rise of Environmentally Sustainable Packaging Solutions
Sustainability is becoming a key focus in the Ball Grid Array packaging market. Growing environmental concerns are prompting manufacturers to seek eco-friendly packaging materials and production processes. BGA packaging is moving towards the use of lead-free solder balls and recyclable materials to align with global environmental regulations. The push for reduced carbon footprints and compliance with environmental standards in the electronics industry has accelerated the adoption of sustainable packaging solutions. This shift is not only driven by regulatory requirements but also by consumer preference for environmentally conscious products, further enhancing the demand for greener packaging options in the market.
- For instance, Nippon Steel Corporation has successfully developed and commercialized lead-free solder spheres for BGA packages with a diameter as small as 300μm, contributing to reduced use of hazardous materials while maintaining high joint reliability for portable devices.
Market Challenges Analysis:
High Cost of Advanced Packaging Solutions
The Ball Grid Array (BGA) Packaging Market faces significant challenges due to the high cost associated with advanced packaging solutions. The complexity of BGA packaging, particularly for high-density and high-performance applications, increases production costs. Specialized materials, precise manufacturing processes, and the need for advanced equipment contribute to the overall expense. Small and mid-sized manufacturers, in particular, may find it difficult to invest in these high-cost solutions, potentially limiting market growth. While BGA packaging offers numerous advantages, the upfront investment and cost of implementation remain significant hurdles for broader adoption.
Complexity in Manufacturing and Scaling
Another challenge in the BGA packaging market lies in the complexity of manufacturing and scaling production. The process involves intricate steps, including precise placement of solder balls and high-temperature reflow processes. Achieving consistent quality and reliability across large production volumes is difficult and requires advanced technologies and stringent quality control. As demand for BGA packaging increases, manufacturers must invest in new technologies and optimize production lines to scale efficiently. This added complexity can slow down market growth and limit the ability of smaller players to compete with larger, more established manufacturers.
Market Opportunities:
Increasing Demand for High-Performance Electronics
The Ball Grid Array (BGA) Packaging Market is well-positioned to capitalize on the growing demand for high-performance electronics. With the rise of advanced technologies such as artificial intelligence (AI), machine learning (ML), and 5G, the need for efficient and reliable semiconductor packaging continues to grow. BGA packaging is ideal for these applications due to its ability to handle high-density interconnections and thermal management. The increasing complexity of electronic devices in sectors such as telecommunications, automotive, and consumer electronics presents significant opportunities for BGA packaging solutions. Manufacturers can leverage this demand by offering advanced BGA packaging tailored to meet the evolving needs of these high-performance systems.
Expansion of Emerging Markets and Industries
Emerging markets and industries provide substantial growth opportunities for the BGA packaging market. The rapid expansion of the automotive, IoT, and wearable technology sectors is driving the need for smaller, more efficient semiconductor packaging. BGA packaging offers a competitive edge in these applications by delivering compact and high-performance solutions. Moreover, the ongoing advancements in electric vehicles (EVs) and autonomous driving technologies are creating a surge in demand for specialized semiconductor components, further boosting the potential for BGA packaging. Manufacturers can expand their reach by targeting these rapidly growing sectors, capitalizing on the increasing adoption of cutting-edge technologies in emerging markets.
Market Segmentation Analysis:
By Type
The Ball Grid Array (BGA) Packaging Market is primarily segmented into micro BGA and regular BGA. Micro BGA packaging is becoming increasingly popular due to its compact size, making it ideal for miniaturized electronic devices. It provides higher density, better performance, and is particularly suited for high-speed applications. Regular BGA, however, remains the dominant segment, as it is widely used across various industries, including consumer electronics and automotive, where a balance of size and performance is necessary.
- For instance, Tessera Technologies developed micro BGAs with solder balls as small as 50µm in diameter, enabling ultra-compact packaging for next-generation mobile and wearable devices.
By Material
BGA packaging materials are categorized into lead-based and lead-free solder balls. Lead-free solder balls, made from alloys like tin-silver-copper (SAC), are becoming the preferred choice due to growing environmental concerns and stricter regulations. These materials offer enhanced thermal performance and reliability. As industries push for sustainability and compliance with environmental standards, the demand for lead-free materials continues to rise, gradually replacing traditional lead-based solder options.
- For instance, Motorola qualified the near-eutectic SAC387 solder balls, and field data over ten years and more than 100 million mobile phones confirmed that their lead-free solder balls provided reliability equal to or better than lead-based options.
By Application
The BGA packaging market serves a variety of applications, including consumer electronics, automotive, telecommunications, and industrial sectors. In consumer electronics, the demand for high-performance smartphones, laptops, and wearables is a significant driver of BGA adoption. Automotive applications, particularly in advanced driver assistance systems (ADAS) and electric vehicles (EVs), require reliable BGA solutions for their robust performance. The telecommunications industry also utilizes BGA packaging in high-speed data transmission devices, supporting the ongoing expansion of 5G and IoT networks.
Segmentations:
By Type
- Micro BGA
- Regular BGA
By Material
- Lead-Based Solder Balls
- Lead-Free Solder Balls (Tin-Silver-Copper (SAC) Alloys)
By Application
- Consumer Electronics
- Automotive
- Telecommunications
- Industrial
- Aerospace
By Industry Vertical
- Automotive Electronics
- Consumer Electronics
- Industrial Equipment
- Telecommunications
- Healthcare Devices
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America: Leading the Market with Technological Advancements
North America holds a market share of 35% in the Ball Grid Array (BGA) Packaging Market, driven by its strong electronics and semiconductor industry. The region is home to several key players in the electronics, automotive, and telecommunications sectors, all of which rely heavily on advanced packaging solutions for their high-performance products. The widespread adoption of cutting-edge technologies such as 5G and artificial intelligence (AI) continues to fuel the demand for BGA packaging in the region. The presence of leading semiconductor manufacturers and continuous investments in R&D further support the region’s growth in the market. North America is expected to maintain a significant share as companies increasingly adopt BGA packaging for more compact and efficient solutions.
Asia Pacific: Rapid Growth Driven by Manufacturing and Consumer Electronics
Asia Pacific commands a 40% share of the Ball Grid Array packaging market, fueled by the strong manufacturing base in countries like China, Japan, and South Korea. The region is a global hub for semiconductor production, with major manufacturers actively adopting BGA packaging solutions to meet the increasing demand for high-performance electronics. The growing consumer electronics market, along with the rise of the automotive and IoT sectors, is fueling the need for compact, reliable, and high-density packaging. As these sectors expand, so will the adoption of BGA packaging to support advanced electronic systems.
Europe: Steady Demand from Automotive and Industrial Sectors
Europe accounts for 18% of the Ball Grid Array packaging market, with demand driven by the automotive and industrial sectors. The region’s focus on automotive electronics, such as advanced driver-assistance systems (ADAS) and electric vehicles (EVs), drives the need for reliable and efficient semiconductor packaging solutions. BGA packaging’s ability to provide superior thermal management and reliability in harsh conditions makes it an ideal choice for these applications. Furthermore, Europe's commitment to technological advancements and its emphasis on sustainability are creating new opportunities for BGA packaging in various industrial applications, reinforcing its steady market growth.
Key Player Analysis:
- ASE Technology Holding
- Infineon Technologies AG
- Amkor Technology
- Corintech Ltd.
- Integrated Circuit Engineering Corp.
- STATS ChipPAC
- NXP Semiconductors NV
- Jiangsu Changjiang Electronics Technology
- Cypress Semiconductor Corp.
- TriQuint Semiconductor Inc.
Competitive Analysis:
The Ball Grid Array (BGA) Packaging Market is highly competitive, with key players constantly innovating to meet the increasing demand for advanced semiconductor packaging solutions. Leading companies such as Intel Corporation, Amkor Technology, and ASE Group dominate the market, leveraging their extensive technological expertise and manufacturing capabilities. These players focus on enhancing product performance, reducing costs, and improving thermal management through continuous R&D and process improvements. Emerging players are also making strides, offering cost-effective solutions and targeting niche markets within automotive and consumer electronics sectors. Strategic collaborations, mergers, and acquisitions are prevalent as companies seek to expand their product portfolios and strengthen their market presence. The competition is further intensified by the growing demand for miniaturized and high-performance devices, driving players to adopt cutting-edge technologies and meet evolving customer needs. Market growth depends on innovation, efficiency, and the ability to adapt to rapidly changing industry trends.
Market Concentration & Characteristics:
The Ball Grid Array (BGA) Packaging Market exhibits moderate concentration, with a few dominant players holding significant market share. Leading companies such as Intel Corporation, Amkor Technology, and ASE Group drive innovation and technological advancements in the market. Smaller and emerging players focus on providing cost-effective solutions and targeting niche applications, particularly in the automotive and consumer electronics sectors. The market is characterized by rapid technological advancements, high demand for miniaturized electronic devices, and a growing emphasis on sustainable and eco-friendly packaging materials. The competitive landscape is shaped by strong R&D capabilities, partnerships, and the ability to meet the evolving demands of industries like telecommunications, automotive, and industrial electronics. Companies that can adapt to the need for higher performance, reliability, and reduced production costs continue to lead in this market.
Report Coverage:
The research report offers an in-depth analysis based on Type, Material, Application, vertical Industry and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Ball Grid Array (BGA) Packaging Market is projected to witness significant growth, driven by the increasing demand for miniaturized electronic devices.
- Asia Pacific is expected to maintain its leadership in the market due to a strong manufacturing base and high adoption rates in consumer electronics and telecommunications.
- North America continues to hold a significant market share, supported by technological advancements and strong demand across industries like automotive, telecommunications, and consumer electronics.
- The automotive sector's adoption of BGA packaging is on the rise, driven by the need for advanced driver-assistance systems (ADAS) and electric vehicle components.
- Consumer electronics, including smartphones, laptops, and wearables, remain a dominant application area, driving the demand for compact and efficient packaging solutions.
- The expansion of 5G networks is significantly increasing the demand for high-performance BGA packaging in the telecommunications industry.
- Ongoing advancements in semiconductor technology are driving the demand for BGA packaging solutions that can support high-density and high-performance configurations.
- The shift towards lead-free and eco-friendly materials in BGA packaging is in line with global environmental regulations and sustainability trends.
- The growth of Internet of Things (IoT) devices is contributing to the increasing demand for reliable, high-performance BGA packaging solutions.
- Key market players are focusing on strategic collaborations, mergers, and acquisitions to enhance their product offerings and expand their market reach.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Ball Grid Array BGA Packaging Market?
What are the key segments within the Ball Grid Array BGA Packaging Market?
Who are the major players in the Ball Grid Array BGA Packaging Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Ball Grid Array (BGA) Packaging Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Ball Grid Array (BGA) Packaging Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,700 million → 2032: USD 6,188.1 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Ball Grid Array (BGA) Packaging Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Ball Grid Array (BGA) Packaging Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Ball Grid Array (BGA) Packaging Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Ball Grid Array (BGA) Packaging Market Drivers
- 3.3 Ball Grid Array (BGA) Packaging Market Restraints & Challenges
- 3.4 Ball Grid Array (BGA) Packaging Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Ball Grid Array (BGA) Packaging Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Ball Grid Array (BGA) Packaging Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Ball Grid Array (BGA) Packaging category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Ball Grid Array (BGA) Packaging Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Ball Grid Array (BGA) Packaging Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Ball Grid Array (BGA) Packaging market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Ball Grid Array (BGA) Packaging Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Ball Grid Array (BGA) Packaging Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Ball Grid Array (BGA) Packaging Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Ball Grid Array (BGA) Packaging (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Ball Grid Array (BGA) Packaging Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Ball Grid Array (BGA) Packaging Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Ball Grid Array (BGA) Packaging Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Ball Grid Array (BGA) Packaging Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Ball Grid Array (BGA) Packaging Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Ball Grid Array (BGA) Packaging Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Ball Grid Array (BGA) Packaging Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Ball Grid Array (BGA) Packaging Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Ball Grid Array (BGA) Packaging Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
