
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Banana Flour Market Size 2024 | USD 1,059.76 million |
| Banana Flour Market, CAGR | 6.73% |
| Banana Flour Market Size 2032 | USD 1,852.73 million |
Market Overview
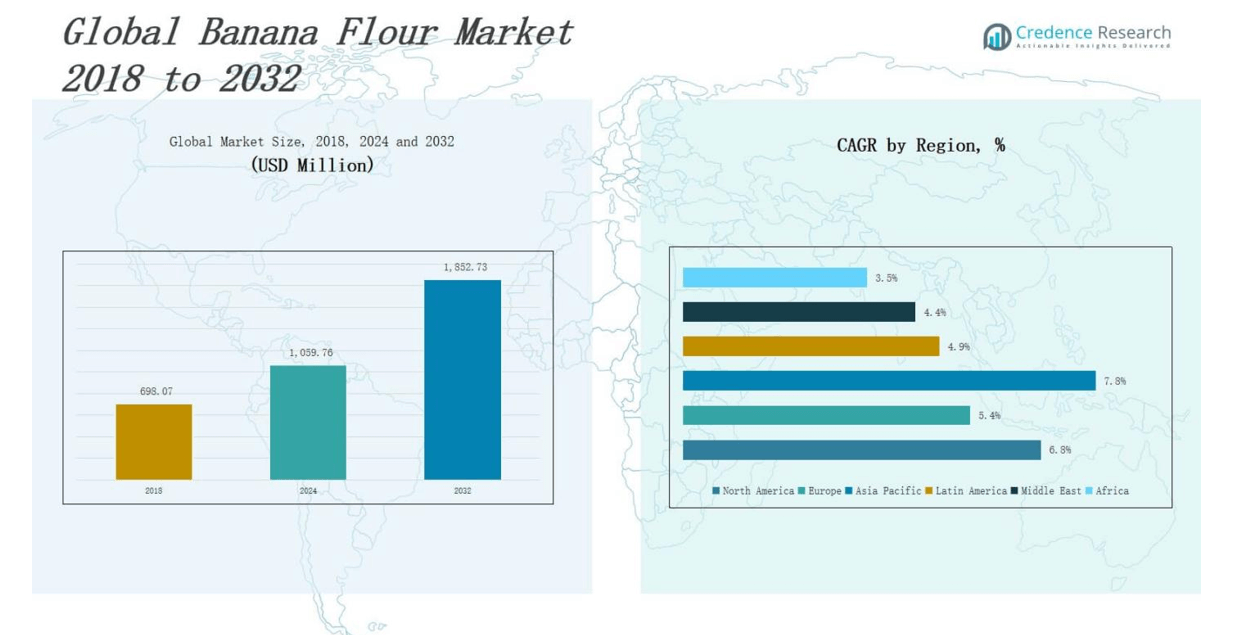
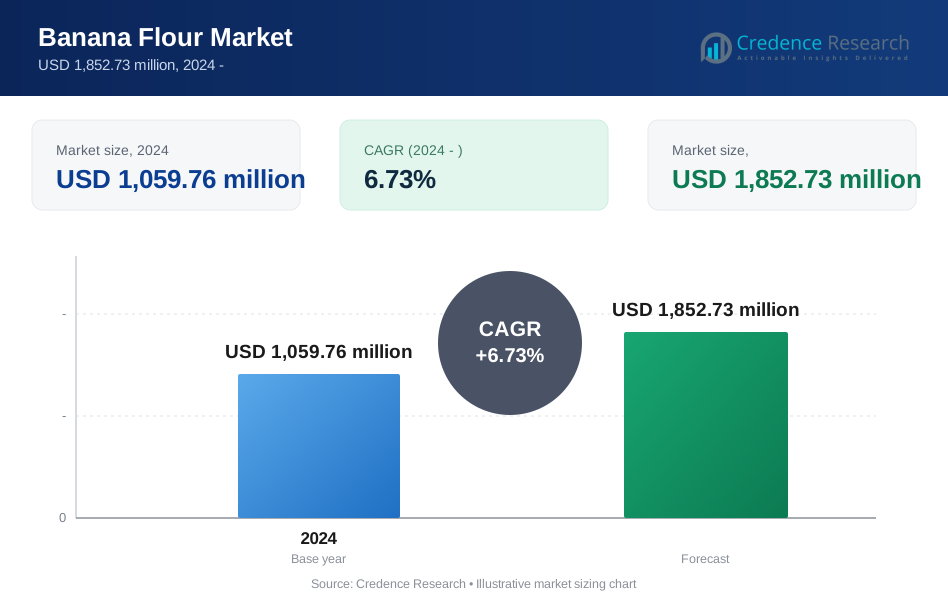
The Banana Flour Market size was valued at USD 698.07 million in 2018 to USD 1,059.76 million in 2024 and is anticipated to reach USD 1,852.73 million by 2032, at a CAGR of 6.73 % during the forecast period.
The banana flour market is driven by rising consumer demand for gluten-free and paleo-friendly alternatives, growing awareness of the nutritional benefits of green banana flour—such as high resistant starch content and low glycemic index—and increased application across bakery, snacks, infant food, and functional food industries. Manufacturers are leveraging its cost-effectiveness and sustainability, as banana flour utilizes surplus or imperfect bananas that would otherwise go to waste, aligning with the global push for food waste reduction. Additionally, emerging economies are boosting production and export due to favorable climatic conditions and government support for agricultural value addition. Key trends include product innovation in ready-to-mix formulations, clean-label positioning, and expansion in plant-based and keto product lines. The market is also witnessing rising demand from sports nutrition and diabetic food sectors due to its natural fiber content and digestive health benefits. E-commerce platforms are further accelerating market reach, especially in North America and Europe, by enabling easy access to niche health-oriented products.
The Banana Flour Market spans key regions including North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa. North America leads in consumption due to high demand for gluten-free and functional foods, while Europe follows with strong interest in organic and clean-label products. Asia Pacific shows the fastest growth, driven by abundant banana production and expanding health food sectors. Latin America, Africa, and the Middle East serve as emerging markets and sourcing hubs, supported by agricultural output and export opportunities. Leading players in the global Banana Flour Market include Nestlé, Kellogg’s, General Mills, Dr. Oetker, Bunge Limited, SVZ International B.V., Kanegrade Limited, Van Drunen Farms, and Natural Evolution Food. These companies compete through innovation, sustainable sourcing, and product diversification to capture both developed and developing markets. Regional and global strategies continue shaping the competitive landscape across all geographies.
Market Insights
- The Banana Flour Market size was valued at USD 698.07 million in 2018, reached USD 1,059.76 million in 2024, and is projected to hit USD 1,852.73 million by 2032, growing at a CAGR of 6.73% during the forecast period.
- Rising demand for gluten-free, paleo, and low-glycemic food options is driving the market, with banana flour gaining popularity in bakery, infant food, and functional food industries for its nutritional value and versatility.
- Banana flour aligns with sustainability goals by utilizing surplus or imperfect bananas, reducing food waste and offering cost-efficient raw material options for manufacturers.
- E-commerce and specialty health food stores are expanding product reach, especially in North America and Europe, where consumers are actively seeking natural, clean-label alternatives.
- Asia Pacific is the fastest-growing region, supported by favorable climatic conditions, government incentives, and large-scale banana production in countries like India and the Philippines.
- Despite growth, the market faces challenges such as limited mainstream consumer awareness and inconsistent quality due to fragmented supply chains in developing regions.
- Key players in the Banana Flour Market include Nestlé, Kellogg’s, General Mills, Dr. Oetker, Bunge Limited, SVZ International B.V., Kanegrade Limited, Van Drunen Farms, and Natural Evolution Food, competing on innovation, sourcing, and product diversification.
Market Drivers
Rising Demand for Gluten-Free and Functional Food Products
The Banana Flour Market is gaining traction due to increasing consumer demand for gluten-free, allergen-free, and clean-label food alternatives. With a growing number of people diagnosed with celiac disease or adopting gluten-free diets for lifestyle reasons, banana flour offers a natural solution. It contains resistant starch that supports digestive health and blood sugar control. Food manufacturers are incorporating it into bakery products, snacks, and health supplements to cater to health-conscious consumers. It supports gut health and satiety, attracting those focused on weight management. The market benefits from these evolving dietary preferences and health trends.
- For instance, Bob’s Red Mill introduced banana flour as a gluten-free baking ingredient, highlighting its use in pancakes and muffins for those with celiac disease.
Sustainability and Reduction of Agricultural Waste
The Banana Flour Market is supported by its alignment with global sustainability goals. It uses surplus or imperfect bananas that would otherwise go to waste, transforming agricultural by-products into valuable ingredients. Producers can extend banana shelf life and minimize post-harvest losses, which is critical in banana-producing regions. This sustainable aspect appeals to both food manufacturers and eco-aware consumers. It supports circular economy models, enhancing brand value and consumer trust. The environmentally friendly image of banana flour strengthens its market position.
- For instance, Natural Evolution Limited in Australia pioneered the commercial production of green banana flour by upcycling bananas rejected for cosmetic reasons, preventing thousands of tonnes of bananas from going to landfill each year.
Increasing Application Across Diverse Food Industries
The Banana Flour Market is expanding rapidly due to its versatility in food and beverage applications. It functions well in baking, thickening sauces, and producing infant foods or meal replacements. Food processors use it to improve texture, shelf stability, and nutritional content without chemical additives. Its neutral taste and high dietary fiber make it a preferred substitute for wheat flour. It helps product developers meet clean-label demands and functional ingredient targets. Its use in sports nutrition and diabetic-friendly formulations continues to grow.
Government Support and Export Opportunities in Emerging Economies
The Banana Flour Market benefits from agricultural development policies and infrastructure support in countries like India, the Philippines, and Uganda. Governments are encouraging local processing to add value to banana production and increase farmer incomes. Export demand from North America and Europe is growing due to rising awareness of its nutritional and functional benefits. It allows producers in developing regions to tap into premium health food markets. It supports rural employment and drives agro-industrial diversification. These initiatives fuel supply chain expansion and market access.
Market Trends
Product Innovation Focused on Clean-Label and Plant-Based Formulations
The Banana Flour Market is witnessing a strong trend toward clean-label and plant-based innovation across product lines. Brands are launching gluten-free baking mixes, protein bars, and pancake blends using banana flour to meet growing demand for simple, recognizable ingredients. It fits seamlessly into vegan and paleo formulations due to its plant-based origin and functional performance. Manufacturers are highlighting its high fiber and low sugar profile on product labels to appeal to health-driven consumers. This trend is prompting broader adoption across both premium and mainstream food categories. It supports clear marketing messages tied to natural wellness and dietary simplicity.
- For instance, Givaudan’s Sense Texture Green Banana Powder is featured in clean-label savory crackers and fruit preparations, where it replaces modified starches and thickeners, allowing products to remain additive-free and suitable for vegan or paleo diets.
Expansion in E-Commerce and Health-Focused Retail Channels
The Banana Flour Market is gaining visibility through digital retail platforms and specialized health food stores. E-commerce platforms are enabling small and mid-sized brands to reach health-conscious consumers without the need for traditional retail distribution. It allows niche producers to market banana flour as a versatile, gut-friendly, and gluten-free ingredient with measurable benefits. Online product listings often emphasize its resistant starch content and low glycemic load, which resonates with diabetic and fitness-focused buyers. Retailers are also dedicating shelf space to alternative flours in response to rising consumer interest. This trend supports market access and accelerates global adoption.
Growing Interest from Sports Nutrition and Clinical Nutrition Segments
The Banana Flour Market is seeing increased demand from sports and clinical nutrition sectors seeking carbohydrate sources with digestive and energy-related benefits. Resistant starch in banana flour supports sustained energy release, making it ideal for pre- and post-workout nutrition. Its high potassium content and ease of digestion offer added value in medical or dietary recovery formulas. Product developers use it in bars, shakes, and medical nutrition products aimed at digestive health or blood sugar regulation. It meets nutrient density requirements without synthetic ingredients. These benefits drive its uptake in performance and therapeutic food categories.
- For instance, NuNaturals launched a Green Banana Flour that is promoted for use in energy bars and shakes, highlighting its resistant starch content for sustained energy release and digestive health.
Integration into Mainstream Food Manufacturing and Private Labels
The Banana Flour Market is becoming more integrated into large-scale food manufacturing, including private label and ready-to-eat product segments. Food companies are formulating cereals, snack puffs, baby foods, and bakery items using banana flour to improve nutritional value and cater to clean-label standards. It enhances texture, binding, and shelf-life stability without chemical additives. Retailers are launching store brands that feature banana flour in affordable health food lines. It appeals to both cost-conscious and nutrition-aware consumers seeking accessible wellness options. This integration supports commercial scalability and long-term product positioning.
Market Challenges Analysis
Limited Consumer Awareness and Perceived Niche Appeal
The Banana Flour Market faces a key challenge in limited consumer awareness outside health-conscious and specialty food segments. Many mainstream consumers are unfamiliar with its functional benefits or how to use it in daily cooking. It often competes with more established gluten-free alternatives such as almond, coconut, and rice flours. Retailers may hesitate to allocate shelf space due to its niche appeal and slower turnover in general grocery channels. Educating consumers on its nutritional value and versatility remains a hurdle for market penetration. It requires targeted marketing and recipe-focused outreach to expand adoption.
Inconsistent Supply Chain and Quality Variability
The Banana Flour Market is challenged by fragmented supply chains and inconsistent raw material availability, especially in regions with limited processing infrastructure. Climatic conditions, post-harvest losses, and lack of standardization affect banana flour quality and shelf stability. It can lead to variable performance in commercial food formulations, limiting trust among manufacturers. Small-scale producers may lack certifications required for exports or bulk contracts. Ensuring reliable sourcing and uniform processing standards is essential for scaling operations. It demands investment in logistics, quality control, and farmer training to meet international specifications.
Market Opportunities
Rising Demand for Gut-Health and Low-Glycemic Foods
The Banana Flour Market has a strong opportunity in the expanding functional food and wellness segments. Consumers are increasingly prioritizing digestive health and stable energy levels, creating demand for ingredients rich in resistant starch. It naturally supports gut microbiome balance and blood sugar regulation, making it ideal for diabetic-friendly and weight management products. Health brands can position banana flour as a clean, plant-based solution with multiple physiological benefits. It fits evolving consumer preferences for high-fiber, low-glycemic foods. This health-driven demand opens growth channels in premium and therapeutic food categories.
Expansion into Infant, Geriatric, and Clinical Nutrition
The Banana Flour Market can expand into specialized nutrition segments such as infant food, geriatric diets, and medical nutrition. Its smooth texture, nutrient density, and digestibility make it suitable for sensitive populations. Food formulators can incorporate it into porridges, meal replacements, or therapeutic diets requiring simple, hypoallergenic ingredients. It meets rising interest in natural, additive-free nutrition in regulated sectors. Institutional buyers and healthcare providers are seeking alternative ingredients that combine functionality with safety. This opportunity enables long-term positioning beyond retail health food trends.
Market Segmentation Analysis:
By Type
The Banana Flour Market is segmented into green banana flour and ripe banana flour. Green banana flour dominates the segment due to its high resistant starch content, making it suitable for gluten-free and diabetic-friendly products. It is widely used in functional foods and health supplements for digestive and metabolic benefits. Ripe banana flour finds use in confectionery and bakery products due to its natural sweetness and smoother texture. It offers flavor enhancement without added sugar. Both types meet distinct consumer and industrial needs, supporting category expansion.
- For instance, NuNaturals launched a green banana flour in the U.S. that contains over 60% resistant starch, specifically marketed for gut health and blood sugar management.
By Nature
The Banana Flour Market is categorized into organic and conventional segments. Organic banana flour is gaining popularity among health-conscious and environmentally aware consumers. It aligns with clean-label trends and often commands premium pricing in international markets. Conventional banana flour maintains higher volume due to wider availability and cost efficiency. It remains a preferred choice for large-scale manufacturers and developing regions. The dual nature segmentation allows flexibility across pricing and distribution strategies.
- For instance, Natural Evolution Foods offers organic green banana flour produced from unripe Cavendish bananas in Australia, emphasizing chemical-free farming and high resistant starch content.
By Application
The Banana Flour Market spans a broad range of applications, including bakery products, dietary supplements, baby food, functional beverages, snacks, and others. Bakery products lead the segment, where banana flour acts as a gluten-free alternative to wheat flour. It enhances the nutritional profile of bread, muffins, and pancakes. Dietary supplements and baby food segments use it for its high fiber and easy digestibility. It also finds growing usage in smoothies and health drinks under functional beverages. Its versatility continues to drive innovation in snacks and niche applications.
Segments:
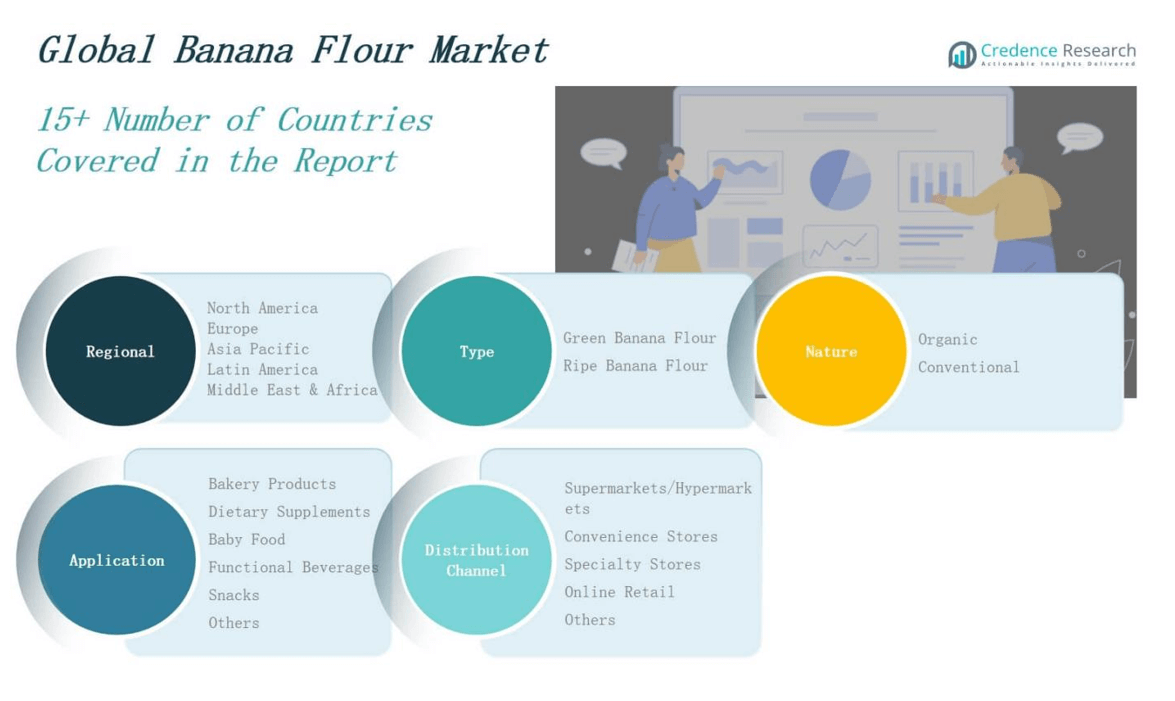
Based on Type
- Green Banana Flour
- Ripe Banana Flour
Based on Nature
- Organic
- Conventional
Based on Application
- Bakery Products
- Dietary Supplements
- Baby Food
- Functional Beverages
- Snacks
- Others
Based on Distribution Channel
- Supermarkets/Hypermarkets
- Convenience Stores
- Specialty Stores
- Online Retail
- Others
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
The North America Banana Flour Market size was valued at USD 294.10 million in 2018 to USD 441.67 million in 2024 and is anticipated to reach USD 774.38 million by 2032, at a CAGR of 6.8% during the forecast period. North America holds the largest share in the Banana Flour Market, driven by strong demand for gluten-free, functional, and plant-based ingredients. Consumers in the U.S. and Canada actively seek alternatives to traditional flours, especially in sports nutrition and diabetic-friendly products. It is widely used across bakery, snacks, and supplement industries due to its clean-label appeal and nutritional profile. The region benefits from well-established retail and e-commerce distribution, making banana flour more accessible to niche and mainstream buyers. Food brands continue to invest in product innovation and formulation using banana flour, reinforcing its growth momentum.
Europe
The Europe Banana Flour Market size was valued at USD 127.29 million in 2018 to USD 182.40 million in 2024 and is anticipated to reach USD 289.23 million by 2032, at a CAGR of 5.4% during the forecast period. Europe accounts for a significant share in the Banana Flour Market, supported by increasing regulatory push toward clean-label and allergen-free food products. Consumers in countries like Germany, France, and the UK are adopting banana flour in both home baking and commercial food sectors. It is used in vegan, paleo, and low-carb product ranges, particularly in organic formulations. Growth is also driven by demand for low-glycemic and fiber-rich alternatives. The market benefits from structured retail systems and rising interest in nutritional transparency. Manufacturers are expanding their product lines to cater to this evolving demand.
Asia Pacific
The Asia Pacific Banana Flour Market size was valued at USD 218.66 million in 2018 to USD 349.05 million in 2024 and is anticipated to reach USD 661.43 million by 2032, at a CAGR of 7.8% during the forecast period. Asia Pacific is the fastest-growing region in the Banana Flour Market, led by major banana-producing countries like India, the Philippines, and Indonesia. Government support for agri-processing, rising exports, and increasing domestic consumption drive market expansion. It is gaining traction in health-conscious urban centers for its affordability, versatility, and nutritional benefits. Food manufacturers are incorporating it into snacks, baby food, and bakery mixes. Demand from both export markets and local consumers fuels consistent growth. The region benefits from low-cost production and growing health awareness.
Latin America
The Latin America Banana Flour Market size was valued at USD 28.86 million in 2018 to USD 43.19 million in 2024 and is anticipated to reach USD 65.57 million by 2032, at a CAGR of 4.9% during the forecast period. Latin America is emerging as a production and export hub in the Banana Flour Market. Countries like Ecuador, Colombia, and Brazil are leveraging banana surplus to produce flour for international buyers. It supports rural economies by offering value-added income streams. Domestic demand is modest but increasing in urban centers. The market is gradually adopting banana flour across snack and bakery categories. Export-oriented strategies and sustainable farming practices are shaping regional dynamics.
Middle East
The Middle East Banana Flour Market size was valued at USD 19.09 million in 2018 to USD 26.42 million in 2024 and is anticipated to reach USD 38.78 million by 2032, at a CAGR of 4.4% during the forecast period. The Middle East represents a niche but growing market in the Banana Flour Market. Health trends focused on sugar reduction and high-fiber diets are encouraging the adoption of banana flour in specialty foods. It finds use in diabetic-friendly products and nutritional supplements. Countries like the UAE and Saudi Arabia are importing banana flour to meet the needs of health-conscious consumers. Growth is supported by expanding health food retail and awareness campaigns. Demand remains concentrated in premium segments.
Africa
The Africa Banana Flour Market size was valued at USD 10.09 million in 2018 to USD 17.03 million in 2024 and is anticipated to reach USD 23.33 million by 2032, at a CAGR of 3.5% during the forecast period. Africa holds potential for both production and consumption in the Banana Flour Market. Uganda and Tanzania are utilizing banana abundance to produce flour for local use and export. It supports food security initiatives by providing an affordable, shelf-stable, and nutritious alternative to imported flours. Domestic adoption is seen in institutional feeding and school meal programs. Market growth is slow but steady due to limited processing infrastructure. Development programs and private investment can enhance regional competitiveness.
Key Player Analysis
- General Mills
- Kanegrade Limited
- Nestlé
- SVZ International B.V.
- Natural Evolution Food
- Bunge Limited
- Van Drunen Farms
- Oetker
- Kellogg’s
Competitive Analysis
The Banana Flour Market is characterized by a mix of multinational food corporations and specialized ingredient manufacturers competing on innovation, quality, and sourcing efficiency. Key players such as Nestlé, General Mills, and Kellogg’s are integrating banana flour into health-focused product lines to meet clean-label and dietary trends. It sees strong competition from companies like Natural Evolution Food and Kanegrade Limited, which emphasize sustainability and product purity. Firms are investing in research to enhance functional performance in gluten-free and high-fiber formulations. Branding strategies highlight origin traceability and nutritional superiority. It requires players to maintain reliable supply chains, consistent quality, and regulatory compliance to secure global distribution. Partnerships with banana producers and local processors help control costs and support scalability. The market continues to reward brands that align with consumer expectations around health, transparency, and minimal processing. Competitive advantage depends on blending technical expertise with strategic sourcing and product diversification.
Recent Developments
- In November 2023, Fyffes entered a public-private partnership with the Belize Ministry of Agriculture to supply banana flour porridge for a national school feeding program in Bella Vista.
- In February 2023, Fresh Del Monte and Talc Investment announced a banana-based partnership in Somalia to enhance production capabilities and value-added applications.
- In July 2024, International Agriculture Group launched NuBana N200 green banana flour featuring 65% resistant starch, targeting powders, beverage mixes, and bars
- In February 2025, Givaudan entered a strategic partnership with Dole Specialty Ingredients to distribute upcycled green banana powder through its Sense Texture range, targeting clean-label emulsification and functional texture applications in the food industry
Market Concentration & Characteristics
The Banana Flour Market exhibits a moderately fragmented structure, with a mix of global food conglomerates and regional producers competing across various price and quality tiers. It features strong involvement from established players like Nestlé, General Mills, and Kellogg’s, alongside specialized firms such as Natural Evolution Food and Kanegrade Limited. The market is characterized by a growing preference for clean-label, gluten-free, and functional ingredients, driving innovation in formulation and packaging. It relies heavily on agricultural supply chains, particularly in banana-producing countries, making sourcing efficiency and quality control critical success factors. Companies are investing in regional processing units and export capabilities to meet rising global demand. The presence of both organic and conventional product segments creates diverse opportunities across mass and premium markets. It continues to evolve with the expansion of e-commerce platforms, private label offerings, and rising consumer education around health-focused ingredients. Branding, sustainability practices, and origin traceability are emerging as key differentiators.
Report Coverage
The research report offers an in-depth analysis based on Type, Nature, Application, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for banana flour will continue to grow due to rising interest in gluten-free and plant-based diets.
- Food manufacturers will expand product development using banana flour in bakery, snacks, and baby food categories.
- Green banana flour will gain more traction for its resistant starch and health benefits.
- E-commerce will play a larger role in market expansion by increasing access to niche health products.
- Innovation in ready-to-mix and clean-label formulations will drive consumer adoption.
- Banana-producing countries will strengthen their role as suppliers through investments in processing infrastructure.
- More retailers will include banana flour under private label brands targeting wellness-focused consumers.
- Organic banana flour will see rising demand in premium and export-focused segments.
- Supply chain improvements will enhance product consistency and boost manufacturer confidence.
- Sustainability and circular economy practices will influence branding and sourcing strategies across the industry.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the banana flour market size?
What are the key segments within the banana flour market size?
What are some challenges faced by the banana flour market size?
Who are the major players in the banana flour market size?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Banana Flour Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Banana Flour Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 1,059.76 million → forecast year: USD 1,852.73 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Banana Flour Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Banana Flour Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Banana Flour Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Banana Flour Market Drivers
- 3.3 Banana Flour Market Restraints & Challenges
- 3.4 Banana Flour Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Banana Flour Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Banana Flour Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Banana Flour category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Banana Flour Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Banana Flour Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Banana Flour market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Banana Flour Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Banana Flour Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Banana Flour Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Banana Flour (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Banana Flour Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Banana Flour Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Banana Flour Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Banana Flour Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Banana Flour Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Banana Flour Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Banana Flour Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Banana Flour Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Banana Flour Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
