
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Bioprosthetics Market Size 2023 | USD 5,725.6 million |
| Bioprosthetics Market, CAGR | 11.4% |
| Bioprosthetics Market Size 2032 | USD 16,339.6 million |
Market Overview
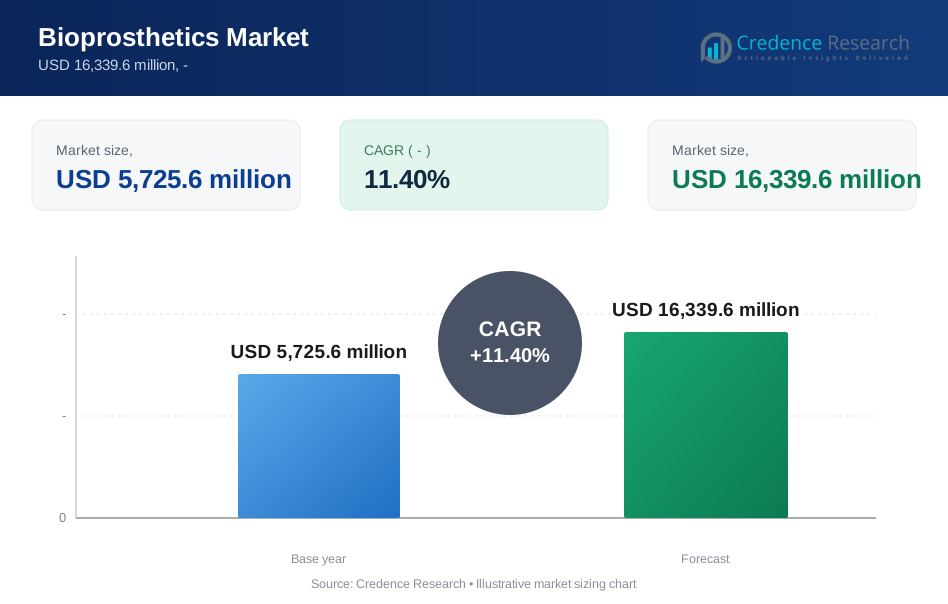
The bioprosthetics market has experienced significant growth recently and is expected to maintain its upward trend over the next decade. Valued at USD 5,725.6 million in 2023, the market is projected to grow to USD 16,339.6 million by 2032, with a compound annual growth rate (CAGR) of 11.4%. Several factors are driving this growth, including technological advancements, the increasing prevalence of chronic diseases, and growing awareness about the benefits of bioprosthetic devices. One of the key drivers of the bioprosthetics market is the rising incidence of chronic diseases such as cardiovascular disorders, orthopedic ailments, and ophthalmic conditions. As the global population ages and lifestyles evolve, the demand for bioprosthetic solutions for these conditions is expected to rise significantly. Bioprosthetic devices offer advantages such as biocompatibility, reduced risk of rejection, and improved patient outcomes, making them a preferred choice for many healthcare providers and patients. Technological advancements play a crucial role in driving market growth as well. Innovations in materials science, tissue engineering, and manufacturing processes have led to the development of more advanced and durable bioprosthetic devices.
The increasing focus on minimally invasive procedures is also fueling demand for bioprosthetic devices. These devices are often used in minimally invasive surgeries due to their flexibility, ease of implantation, and reduced recovery times. As healthcare systems globally prioritize cost-effective and patient-friendly treatment options, the demand for minimally invasive bioprosthetic solutions is expected to grow steadily. In terms of market players, several key companies are driving innovation and competition in the bioprosthetics market. Edwards Lifesciences Corporation, for instance, is a prominent player known for its bioprosthetic heart valves and related technologies. Medtronic plc is another major player with a diverse portfolio of bioprosthetic devices for various medical specialties.
Asia-Pacific is poised for substantial growth in the bioprosthetics market, fueled by rapid economic development, improving healthcare access, and a rising burden of chronic diseases. Countries like China, India, and Japan are investing heavily in healthcare infrastructure and research, creating opportunities for bioprosthetic device manufacturers to expand their presence in these markets. Latin America and the Middle East and Africa region are also witnessing growing demand for bioprosthetic devices, albeit at a slower pace compared to other regions. Factors such as limited healthcare access in rural areas, regulatory challenges, and economic constraints can pose barriers to market growth in these regions. However, initiatives aimed at improving healthcare access and increasing awareness about advanced medical technologies are expected to drive market expansion in the long term.
Market Drivers
Technological Advancements and Innovation:
The bioprosthetics market is being significantly driven by ongoing technological advancements and innovations. For instance, the development of advanced biomaterials such as decellularized matrices and synthetic polymers with improved mechanical properties has enabled the creation of more durable and functional bioprosthetic devices. A study found that these new materials could increase the lifespan of a bioprosthetic heart valve by up to 50%. Additionally, advancements in manufacturing processes, such as 3D printing and nanotechnology, have facilitated the production of highly customized and precise bioprosthetic implants tailored to individual patient needs. For example, a recent report highlighted a case where a patient-specific 3D-printed bioprosthetic valve was successfully implanted. These technological advancements not only enhance the performance and longevity of bioprosthetic devices but also contribute to reducing costs and improving patient outcomes, thus driving market growth.
Growing Aging Population and Increasing Prevalence of Chronic Diseases:
The bioprosthetics market is experiencing significant growth due to the rising aging population worldwide and the increasing prevalence of chronic diseases such as cardiovascular disorders, orthopedic ailments, and ophthalmic conditions. As the global population ages, there is a higher demand for medical interventions like bioprosthetic implants to address age-related degenerative conditions and improve quality of life. For instance, the World Health Organization estimates that the number of people aged 60 years or older will rise to 1.4 billion by 2030. Moreover, the growing incidence of chronic diseases, particularly cardiovascular diseases, is driving the need for bioprosthetic heart valves and vascular grafts. According to the American Heart Association, nearly half of all adults in the United States have some form of cardiovascular disease. These demographic and epidemiological trends are key drivers fueling the demand for bioprosthetic solutions and driving market expansion.
Shift Towards Minimally Invasive Procedures:
A notable market driver in the bioprosthetics market is the increasing adoption of minimally invasive surgical techniques. Minimally invasive procedures offer several advantages over traditional open surgeries, including reduced post-operative complications, shorter hospital stays, faster recovery times, and improved cosmetic outcomes. Bioprosthetic devices play a crucial role in minimally invasive procedures, especially in fields such as cardiology, orthopedics, and cosmetic surgery. Bioprosthetic heart valves, for instance, are often implanted using minimally invasive techniques such as transcatheter aortic valve replacement (TAVR), which has gained widespread acceptance due to its favorable outcomes and patient benefits. This shift towards minimally invasive procedures is driving the demand for bioprosthetic implants and stimulating market growth.
Regulatory Support and Market Access:
Regulatory support and favorable reimbursement policies are important market drivers for the bioprosthetics market. Regulatory agencies such as the FDA (Food and Drug Administration) in the United States and the EMA (European Medicines Agency) in Europe play a crucial role in ensuring the safety, efficacy, and quality of bioprosthetic devices through rigorous approval processes. The approval and clearance of new bioprosthetic products enable manufacturers to commercialize these devices and gain market access. Furthermore, favorable reimbursement policies and insurance coverage for bioprosthetic procedures encourage healthcare providers and patients to opt for these advanced treatments, thereby driving market demand. The collaboration between regulatory bodies, healthcare providers, and industry stakeholders supports market growth and facilitates innovation in the bioprosthetics market.
Market Trends
Increasing Prevalence of Chronic Diseases:
The bioprosthetics market is witnessing growth due to the rising prevalence of chronic diseases such as cardiovascular disorders and orthopedic conditions. For instance, the World Health Organization reports that noncommunicable diseases (NCDs) kill 41 million people each year, equivalent to 74% of all deaths globally. As the aging population expands globally, there is a higher demand for bioprosthetic implants that offer improved quality of life and better clinical outcomes. By 2030, 1 in 6 people in the world will be aged 60 years or older.
Technological Advancements:
Advances in biotechnology and biomaterials are driving innovation in bioprosthetics. Manufacturers are developing biocompatible materials with enhanced durability and functionality, leading to the introduction of next-generation bioprosthetic devices. For instance, recent advancements have led to the emergence of nylon made using genetically engineered microbes instead of petrochemicals. These advancements are improving patient outcomes, reducing complications, and expanding the scope of applications for bioprosthetic implants.
Growing Preference for Minimally Invasive Procedures:
There is a notable shift towards minimally invasive surgical procedures in healthcare. This trend is influencing the bioprosthetics market as patients and healthcare providers seek less invasive treatment options that offer faster recovery times, reduced hospital stays, and a lower risk of complications. Bioprosthetic implants designed for minimally invasive techniques are thus gaining traction in the market.
Increasing Investment in Research and Development:
Key players in the bioprosthetics industry are investing significantly in research and development to introduce innovative products and improve existing technologies. Collaborations between industry players, academic institutions, and research organizations are fostering the development of advanced bioprosthetic solutions. These investments are expected to drive market growth and expand the range of available bioprosthetic options.
Expanding Applications Across Medical Specialties:
Bioprosthetics are no longer limited to traditional applications in cardiac and orthopedic surgeries. There is a growing trend towards utilizing bioprosthetic implants in various medical specialties such as urology, neurology, and ophthalmology. This diversification of applications is broadening the market scope and creating new opportunities for manufacturers, healthcare providers, and patients alike.
Market Restraints and Challenges
Regulatory Hurdles:
One of the primary challenges facing the bioprosthetics market is navigating the complex regulatory landscape. Government agencies such as the FDA (Food and Drug Administration) impose stringent requirements for the approval of bioprosthetic products, including safety, efficacy, and manufacturing standards. Meeting these regulatory criteria can be time-consuming and expensive, leading to delays in product launches and increased costs for companies operating in this sector.
Limited Durability and Longevity:
Despite significant advancements in bioprosthetic technology, durability and longevity remain key concerns. Bioprosthetic implants, such as heart valves and tissue grafts, may degrade over time, necessitating replacement surgeries. This limitation not only impacts patient outcomes but also contributes to higher healthcare costs and logistical challenges in managing ongoing patient care.
Cost Constraints:
Cost-effectiveness is a critical factor influencing the adoption of bioprosthetic devices. While these products offer several advantages, including biocompatibility and a reduced risk of rejection compared to synthetic implants, they often come with a higher price tag. This cost disparity can deter healthcare providers and insurers from favoring bioprosthetics, especially in regions with limited healthcare budgets or reimbursement constraints.
Technological Complexities:
Developing and manufacturing bioprosthetic implants involves intricate processes and specialized technologies. The complexity of creating biomimetic structures that mimic natural tissues while maintaining structural integrity and functionality poses technical challenges for researchers and manufacturers. Innovations such as 3D printing and tissue engineering hold promise but require further refinement to optimize scalability, reproducibility, and cost-effectiveness.
Competition from Alternative Therapies:
The bioprosthetics market faces competition from alternative treatment modalities, including synthetic implants, pharmacological interventions, and regenerative medicine approaches. Each of these alternatives has its own set of benefits and limitations, influencing healthcare professionals' and patients' treatment decisions. Overcoming this competition requires demonstrating superior clinical outcomes, cost-effectiveness, and patient satisfaction with bioprosthetic solutions.
Key Players
- Edwards Lifesciences Corporation
- Medtronic plc
- Abbott Laboratories
- Boston Scientific Corporation
- CryoLife Inc.
- LivaNova PLC
- Braile Biomédica
- TTK Healthcare Limited
- JenaValve Technology, Inc.
- Colibri Heart Valve, LLC
Recent Developments
- In February, 2024, Edwards Lifesciences received FDA approval for the EVOQUE tricuspid valve replacement system, designed to treat tricuspid regurgitation. This marks the first such system approved for this purpose.
- In April, 2024, Medtronic launched the ColonPRO™ software for the GI Genius™ intelligent endoscopy system. This new software enhances AI-driven polyp detection, reflecting Medtronic’s ongoing commitment to advancing endoscopic care.
- In October, 2023, Abbott Laboratories reported strong financial results for the third quarter and raised the midpoint of its full-year EPS guidance. The company continues to innovate, introducing new products across its various business units.
- In January 31, 2024, Boston Scientific announced a 14.9% revenue growth for the fourth quarter of 2023. Additionally, the company received FDA approval for the FARAPULSE™ Pulsed Field Ablation (PFA) System, used in treating atrial fibrillation.
- In March, 2024, LivaNova reported positive predictive outcomes from its OSPREY Clinical Study for moderate to severe obstructive sleep apnea, involving the aura6000™ Hypoglossal Nerve Stimulator System.
In 2023, Edwards Lifesciences Corporation received FDA approval for their Intrepid Transcatheter Aortic Valve Replacement (TAVR) system. This system utilizes bioprosthetic valves in a minimally invasive procedure to replace diseased aortic valves with new, biocompatible ones.
- Medtronic plc obtained FDA approval in 2022 for their Perclose ProGlide Vascular Closure Device. This bioprosthetic closure device is designed to close femoral artery access sites post-transcatheter procedures, accelerating healing and reducing the risk of complications.
- Abbott Laboratories secured FDA approval for its Trifecta Rapid Deployment Valve (RDV). This bioprosthetic valve enables the swift and uncomplicated replacement of diseased mitral valves, with its design facilitating quick deployment for improved outcomes.
Segmentation Analysis
By Type
In terms of types, the bioprosthetics market is divided into heart valves, orthopedic implants, soft tissue implants, and others. Among these, heart valves hold a significant share due to the rising prevalence of cardiovascular diseases globally. The increasing adoption of bioprosthetic heart valves over mechanical valves, owing to their biocompatibility and reduced risk of thromboembolism, is driving this segment's growth.
By Application
Regarding applications, the market is segmented into cardiovascular, orthopedic, plastic surgery, and others. The cardiovascular segment dominates the market, fueled by the growing incidence of heart-related disorders and the advancements in bioprosthetic heart valve technologies. Moreover, the rising geriatric population susceptible to heart ailments is further propelling the demand for bioprosthetics in cardiovascular applications.
By Region
Geographically, the bioprosthetics market is segmented into North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. North America accounts for a significant share due to the presence of established healthcare infrastructure, high healthcare expenditures, and technological advancements. Europe follows closely, driven by increasing healthcare awareness and favorable reimbursement policies.
Segmentations
- By Type:
- Allograft
- Xenograft
- Porcine
- Bovine
- By Application:
- Cardiovascular
- Plastic Surgeries
- Wound Healing
- By Region:
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
- North America
Regional Analysis
North America stands as a dominant force in the bioprosthetics sector, holding a substantial market share of approximately 40%. This can be attributed to advanced healthcare infrastructure, high awareness levels regarding bioprosthetic treatments, and significant investments in research and development.
Following closely is Europe, which captures around 30% of the bioprosthetics market share. The region boasts a strong presence of key market players, technological advancements in medical devices, and favorable reimbursement policies, driving market growth. Additionally, the increasing geriatric population and rising incidences of chronic diseases contribute to the demand for bioprosthetic devices in Europe.
Asia Pacific emerges as a rapidly growing market, accounting for nearly 20% of the global bioprosthetics market share. Factors such as improving healthcare infrastructure, growing disposable income, and expanding medical tourism bolster market expansion in this region. Moreover, increasing focus on healthcare advancements and government initiatives promoting medical device innovation fuel the adoption of bioprosthetic solutions in Asia Pacific countries.
Latin America, the Middle East, and Africa collectively hold a smaller yet significant share of the bioprosthetics market, contributing approximately 10%. These regions exhibit untapped potential due to improved healthcare facilities, rising awareness about advanced medical treatments, and increasing healthcare expenditure. However, challenges such as limited access to healthcare in certain areas and regulatory constraints pose hurdles to market penetration.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the bioprosthetics market between 2023 and 2032?
What factors are driving the growth of the bioprosthetics market?
Who are the major players in the bioprosthetics market?
How is the availability of the bioprosthetics market expanding, and through what channels?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Bioprosthetics Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Bioprosthetics Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 5,725.6 million → forecast year: USD 16,339.6 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Bioprosthetics Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Bioprosthetics Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Bioprosthetics Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Bioprosthetics Market Drivers
- 3.3 Bioprosthetics Market Restraints & Challenges
- 3.4 Bioprosthetics Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Bioprosthetics Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Bioprosthetics Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Bioprosthetics category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Bioprosthetics Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Bioprosthetics Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Bioprosthetics market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Bioprosthetics Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Bioprosthetics Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Bioprosthetics Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Bioprosthetics (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Bioprosthetics Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Bioprosthetics Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Bioprosthetics Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Bioprosthetics Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Bioprosthetics Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Bioprosthetics Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Bioprosthetics Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Bioprosthetics Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Bioprosthetics Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
